Company Coverage
Gas Malaysia (GMB MK): Beneficiary Of Malaysia’s NG Supply Reform
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
RM5.35
RM7.00
+30.8%
RM6.00
Analyst
Highlights
- We upgrade the stock to BUY with a higher DDM-based target price of RM7.00. We raised long-term growth from 2% to 3%, suggesting that the stock will benefit from higher NG volumes as Malaysia races towards clean energy transition while housing 13GW of data centre power demand.
- We believe the stock is set to benefit from two key themes: a) energy transition requiring 8GW of gas-fired power plants to be built by 2031; and b) potential liberalisation of power sector NG supply chain – allowing power plants to secure NG independently from shippers such as Gas Malaysia. In addition, Gas Malaysia may also benefit from off-grid cogen opportunities as DCs “search” for more power supply in Malaysia.
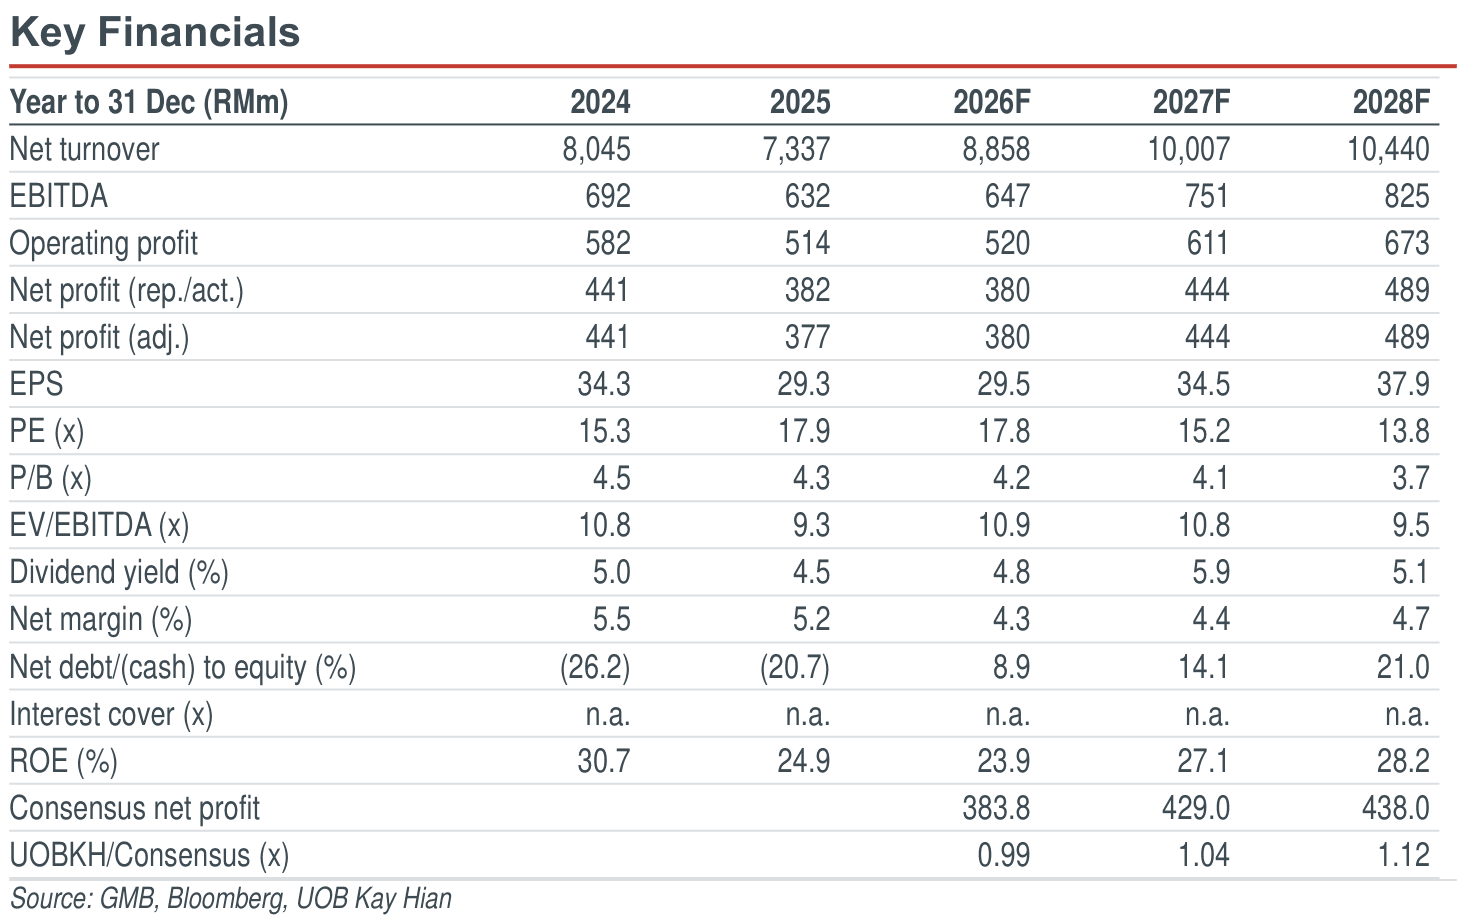
- Yan RGT is expected to reach commercial operations by 1Q31 with a capacity of 500 mmscfd. We gather that up to 90% of the capacity may have been secured as we expect the project to lift EBITDA by 13% with a net present value (equity value) of RM0.58/share.
Analysis
- NG reforms in Peninsular Malaysia… Against the backdrop of energy transition (towards net-zero greenhouse gas emission by 2050) and Malaysia’s aggressive 13GW data centre (DC) plant up, we identify Gas Malaysia as a thematic winner in Malaysia’s natural gas (NG) supply chain reform. As a key transition fuel, NG is projected to account for 56% of Malaysia’s total primary energy supply by 2050, up from 47% in 1H26.
- ….to benefit Gas Malaysia. Key re-rating catalysts for the stock: a) earnings recovery in 2027; b) benefits from the government’s NG roadmap, which is expected to be announced in 1H27; and c) ability to capture unregulated business opportunity as the Data Centre Task Force is now pushing DC operators to secure off-grid power supply. We note that Gas Malaysia has experience operating cogen plant in Penang. We upgrade the stock to BUY with a higher DDM-based target price of RM7.00, based on 3% growth rate vs 2% growth rate.
Highlights
- We upgrade the stock to BUY with a higher DDM-based target price of RM7.00. We raised long-term growth from 2% to 3%, suggesting that the stock will benefit from higher NG volumes as Malaysia races towards clean energy transition while housing 13GW of data centre power demand.
- We believe the stock is set to benefit from two key themes: a) energy transition requiring 8GW of gas-fired power plants to be built by 2031; and b) potential liberalisation of power sector NG supply chain – allowing power plants to secure NG independently from shippers such as Gas Malaysia. In addition, Gas Malaysia may also benefit from off-grid cogen opportunities as DCs “search” for more power supply in Malaysia.
- Yan RGT is expected to reach commercial operations by 1Q31 with a capacity of 500 mmscfd. We gather that up to 90% of the capacity may have been secured as we expect the project to lift EBITDA by 13% with a net present value (equity value) of RM0.58/share.
Analysis
- NG reforms in Peninsular Malaysia… Against the backdrop of energy transition (towards net-zero greenhouse gas emission by 2050) and Malaysia’s aggressive 13GW data centre (DC) plant up, we identify Gas Malaysia as a thematic winner in Malaysia’s natural gas (NG) supply chain reform. As a key transition fuel, NG is projected to account for 56% of Malaysia’s total primary energy supply by 2050, up from 47% in 1H26.
- ….to benefit Gas Malaysia. Key re-rating catalysts for the stock: a) earnings recovery in 2027; b) benefits from the government’s NG roadmap, which is expected to be announced in 1H27; and c) ability to capture unregulated business opportunity as the Data Centre Task Force is now pushing DC operators to secure off-grid power supply. We note that Gas Malaysia has experience operating cogen plant in Penang. We upgrade the stock to BUY with a higher DDM-based target price of RM7.00, based on 3% growth rate vs 2% growth rate.
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
RM5.35
RM7.00
+30.8%
RM6.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Oct 2026
Telekom Malaysia (T MK): On Stronger Footing

2 Oct 2026
VS Industry (VSI MK): Gradual Recovery; Diversifying For Growth

8 Oct 2026
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility
Our latest research

26 Oct 2026
PPB Group (PEP MK): Resilient Wilmar Contributions Support Overall Performance

23 Oct 2026
Hartalega (HART MK): Tides Turning But Headwinds Persist

22 Oct 2026