Company Coverage
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.56
RM0.74
+32.1%
RM0.80
Analyst
Highlights
- 3Q26 results exceeded expectations on interest savings from loan refinancing.
- Shopper traffic (+8.2% yoy) and tenant sales psf (+4.5% yoy) accelerated in 3Q26 due to thematic campaigns and AEI initiatives.
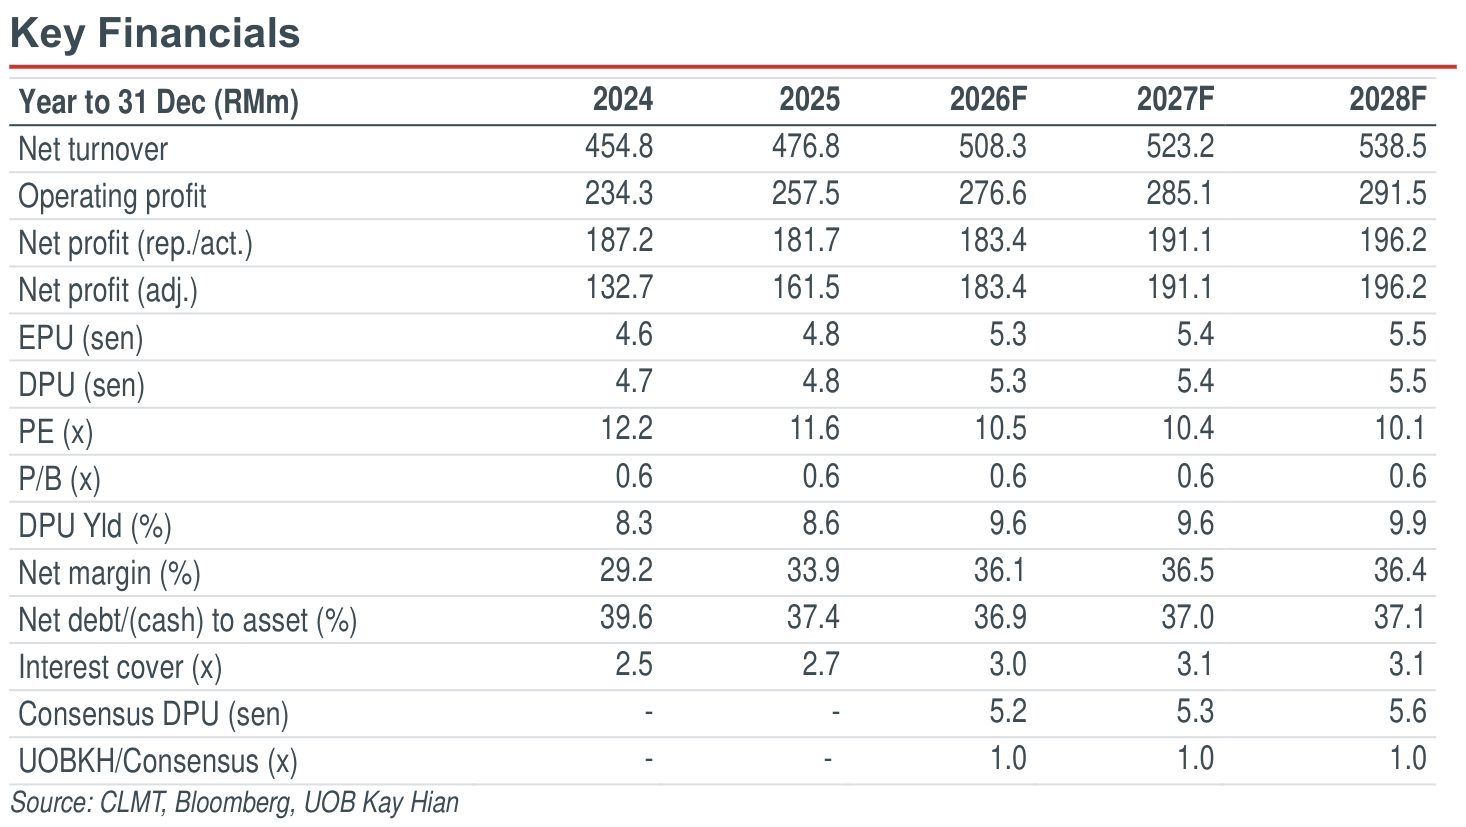
- Maintain BUY with a lower target price of RM0.74 as we roll over our valuation base and increased our cost of equity assumption. CLMT remains our top pick in the REIT sector due to its attractive yield of 9.6% for 2027.
Analysis
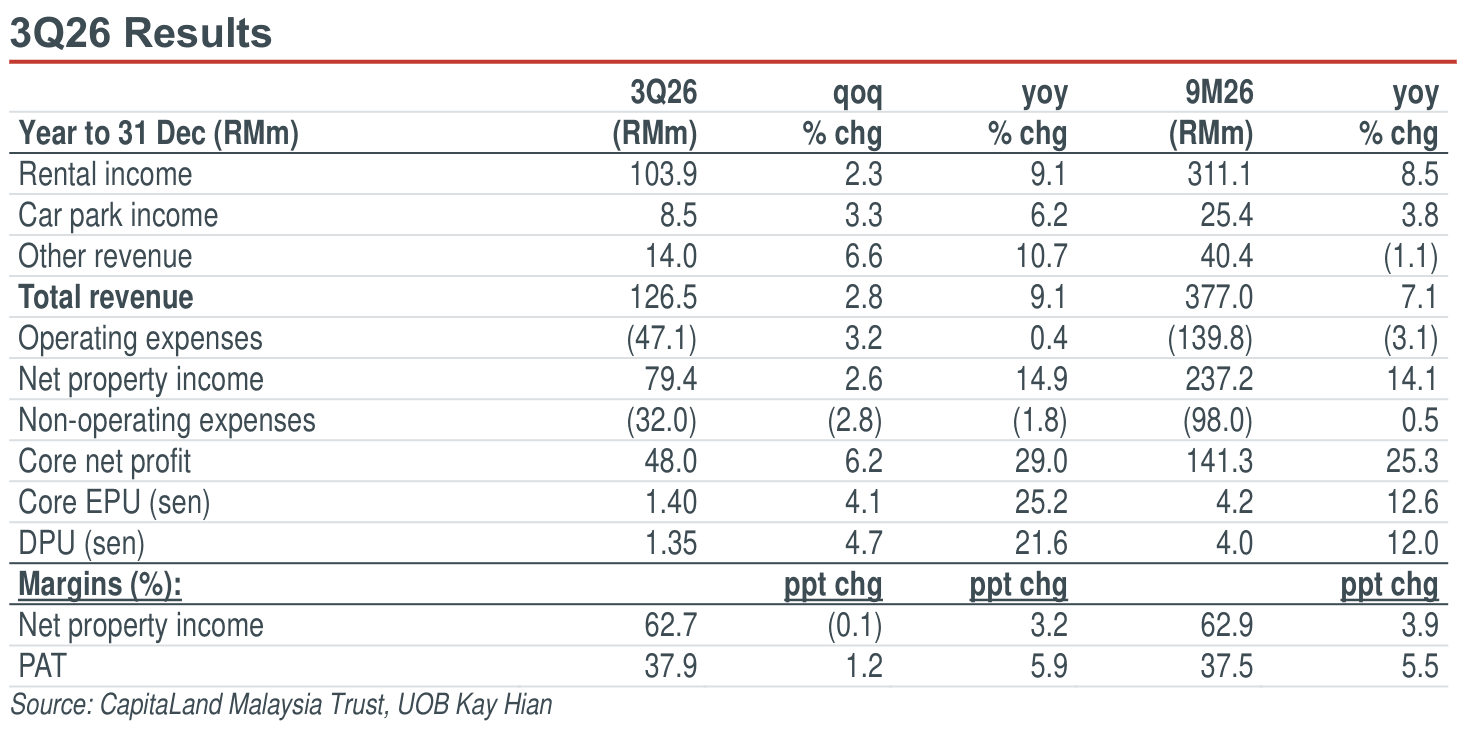
- Results above expectations. CapitaLand Malaysia Trust (CLMT) reported 3Q26 revenue of RM126.5m (+2.8% qoq, +9.1% yoy) and core net profit of RM48.0m (+6.2% qoq, +29.0% yoy). This brings 9M26 core net profit to RM141.3m, accounting for 78.6% and 80.4% of our and consensus full-year estimates respectively. The results exceeded our expectation due to interest savings arising from MTN refinancing done and fixed-rate loans being refixed at lower rates.
- Average cost of debt declined to 4.17% p.a. for 9M26 (vs 4.21%/4.24% p.a. in 1H26/1Q26 respectively). As of end-3Q26, fixed and floating ratio was 75:25.
- A dividend of 1.35 sen was declared for 3Q26 (+21.6% yoy), bringing 9M26 DPU to 4.0 sen.
Highlights
- 3Q26 results exceeded expectations on interest savings from loan refinancing.
- Shopper traffic (+8.2% yoy) and tenant sales psf (+4.5% yoy) accelerated in 3Q26 due to thematic campaigns and AEI initiatives.
- Maintain BUY with a lower target price of RM0.74 as we roll over our valuation base and increased our cost of equity assumption. CLMT remains our top pick in the REIT sector due to its attractive yield of 9.6% for 2027.
Analysis
- Results above expectations. CapitaLand Malaysia Trust (CLMT) reported 3Q26 revenue of RM126.5m (+2.8% qoq, +9.1% yoy) and core net profit of RM48.0m (+6.2% qoq, +29.0% yoy). This brings 9M26 core net profit to RM141.3m, accounting for 78.6% and 80.4% of our and consensus full-year estimates respectively. The results exceeded our expectation due to interest savings arising from MTN refinancing done and fixed-rate loans being refixed at lower rates.
- Average cost of debt declined to 4.17% p.a. for 9M26 (vs 4.21%/4.24% p.a. in 1H26/1Q26 respectively). As of end-3Q26, fixed and floating ratio was 75:25.
- A dividend of 1.35 sen was declared for 3Q26 (+21.6% yoy), bringing 9M26 DPU to 4.0 sen.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.56
RM0.74
+32.1%
RM0.80
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
CapitaLand Malaysia Trust (CLMT MK): Robust Enquiries For i-TechValley Assets

1 Sept 2026
Axiata Group (AXIATA MK): 2Q26: In Line; Partial Monetisation Of Edotco Remains A Key Catalyst

25 Sept 2026
Eco World Development (ECW MK): 3QFY26: In Line; Poised To Achieve Record Sales
Our latest research

22 Oct 2026
Westports Holdings (WPRTS MK): 3Q26: Conventional Business Outperforms Container

21 Oct 2026
CIMB Group (CIMB MK): Resilient Outlook Despite Bond Headwinds

19 Oct 2026