Company Coverage
Hartalega (HART MK): Tides Turning But Headwinds Persist
HOLD (Maintained)
Current price:
Target price:
Upside:
RM1.10
RM1.06
-3.6%
Analyst
Highlights
- 2QFY27 earnings to come in weaker qoq, mainly due to cost pressures and temporary decline in volume sales resulting from the ongoing Iran war.
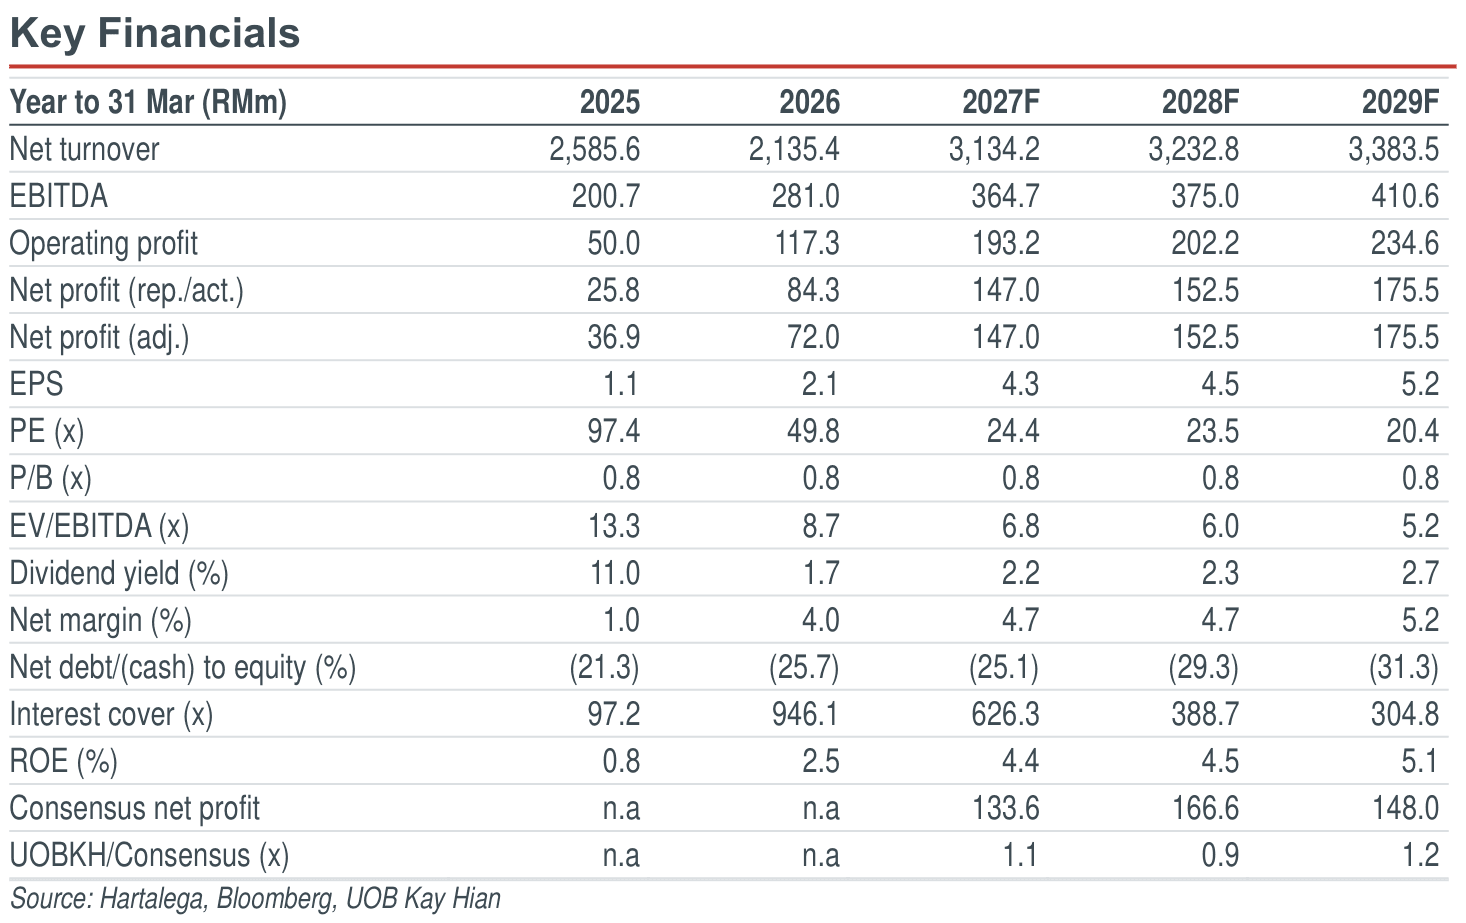
- We forecast 4-15% FY27-29 earnings growth, but various challenges such as higher input costs and lingering China competition remain.
- Risk-reward appears balanced. Maintain HOLD and target price of RM1.06.
Analysis
- Sequentially weaker 2Q-3QFY27 expected. Following the de-escalation of the Iran war, ASP moderated swiftly from peak of US$26-27/’000 pcs in 1QFY27 to US$19-20/’000 pcs for Aug-Sept shipments. Meanwhile, Hartalega (Harta) is guiding for potential margin compression in 2QFY27, as the group needs to lock in and deplete its raw material inventories which are purchased at higher costs due to the Iran war. Furthermore, the natural gas tariff’s upward revision in 3QFY27 will also lift energy cost and further pressure operating margins. Overall, we opine that softer ASP and higher input costs will result in weaker earnings through 2Q-3QFY27 for Harta.
- Volume sales to see temporary decline in upcoming 2Q, but likely to recover in 3Q on better restocking cycle. To recall, Harta reported sales volume of around 5.9b pieces in last quarter (1QFY27). For 2QFY27, we estimate that volume sales will decline to around 5.4b-5.6b pieces (down 3-7% qoq), as some customers are facing vessel availability issues which delayed shipments, and much higher logistic costs due to the ongoing Iran war. Nevertheless, management alluded that 3QFY27 volume sales will recover to around 6b pieces as customers’ restocking activities pick up.
- Operational efficiency and capacity expansion. Harta set aside RM285m for 2026-27 to further automate its production lines to optimise overall efficiency. Hence, margins could marginally recover in FY27 off FY25’s low base, coupled with an improvement in utilisation rate on better demand beginning 1QFY27 (Apr-Jun 26). The full commission of production lines in its Plant 9 which leverages automation and vision systems will also drive higher yields and lower labour costs. In FY27, management intends to restart and upgrade its Plant 3, lifting running capacity from current 27b pieces annually (after hibernating Plant 3 and 4) to 30b pieces by end-26.
Highlights
- 2QFY27 earnings to come in weaker qoq, mainly due to cost pressures and temporary decline in volume sales resulting from the ongoing Iran war.
- We forecast 4-15% FY27-29 earnings growth, but various challenges such as higher input costs and lingering China competition remain.
- Risk-reward appears balanced. Maintain HOLD and target price of RM1.06.
Analysis
- Sequentially weaker 2Q-3QFY27 expected. Following the de-escalation of the Iran war, ASP moderated swiftly from peak of US$26-27/’000 pcs in 1QFY27 to US$19-20/’000 pcs for Aug-Sept shipments. Meanwhile, Hartalega (Harta) is guiding for potential margin compression in 2QFY27, as the group needs to lock in and deplete its raw material inventories which are purchased at higher costs due to the Iran war. Furthermore, the natural gas tariff’s upward revision in 3QFY27 will also lift energy cost and further pressure operating margins. Overall, we opine that softer ASP and higher input costs will result in weaker earnings through 2Q-3QFY27 for Harta.
- Volume sales to see temporary decline in upcoming 2Q, but likely to recover in 3Q on better restocking cycle. To recall, Harta reported sales volume of around 5.9b pieces in last quarter (1QFY27). For 2QFY27, we estimate that volume sales will decline to around 5.4b-5.6b pieces (down 3-7% qoq), as some customers are facing vessel availability issues which delayed shipments, and much higher logistic costs due to the ongoing Iran war. Nevertheless, management alluded that 3QFY27 volume sales will recover to around 6b pieces as customers’ restocking activities pick up.
- Operational efficiency and capacity expansion. Harta set aside RM285m for 2026-27 to further automate its production lines to optimise overall efficiency. Hence, margins could marginally recover in FY27 off FY25’s low base, coupled with an improvement in utilisation rate on better demand beginning 1QFY27 (Apr-Jun 26). The full commission of production lines in its Plant 9 which leverages automation and vision systems will also drive higher yields and lower labour costs. In FY27, management intends to restart and upgrade its Plant 3, lifting running capacity from current 27b pieces annually (after hibernating Plant 3 and 4) to 30b pieces by end-26.
HOLD (Maintained)
Current price:
Target price:
Upside:
RM1.10
RM1.06
-3.6%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

7 Oct 2026
Top Glove (TOPG MK) - 4QFY26: Accelerating Earnings Growth, But Challenges Persist

25 Sept 2026
Eco World Development (ECW MK): 3QFY26: In Line; Poised To Achieve Record Sales

28 Aug 2026
Sime Darby (SIME MK): FY26: Above Expectations
Our latest research

22 Oct 2026
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%

22 Oct 2026
Westports Holdings (WPRTS MK): 3Q26: Conventional Business Outperforms Container

21 Oct 2026