Company Coverage
Pecca Group (PECCA MK): 1QFY27: Below Expectations
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.42
RM1.35
-4.9%
RM1.42
Analyst
Highlights
- Pecca’s 1QFY27 core net profit of RM11.0m (-9% yoy) was below expectations, accounting for 18% of our forecast, due to softer demand from key automotive customers.
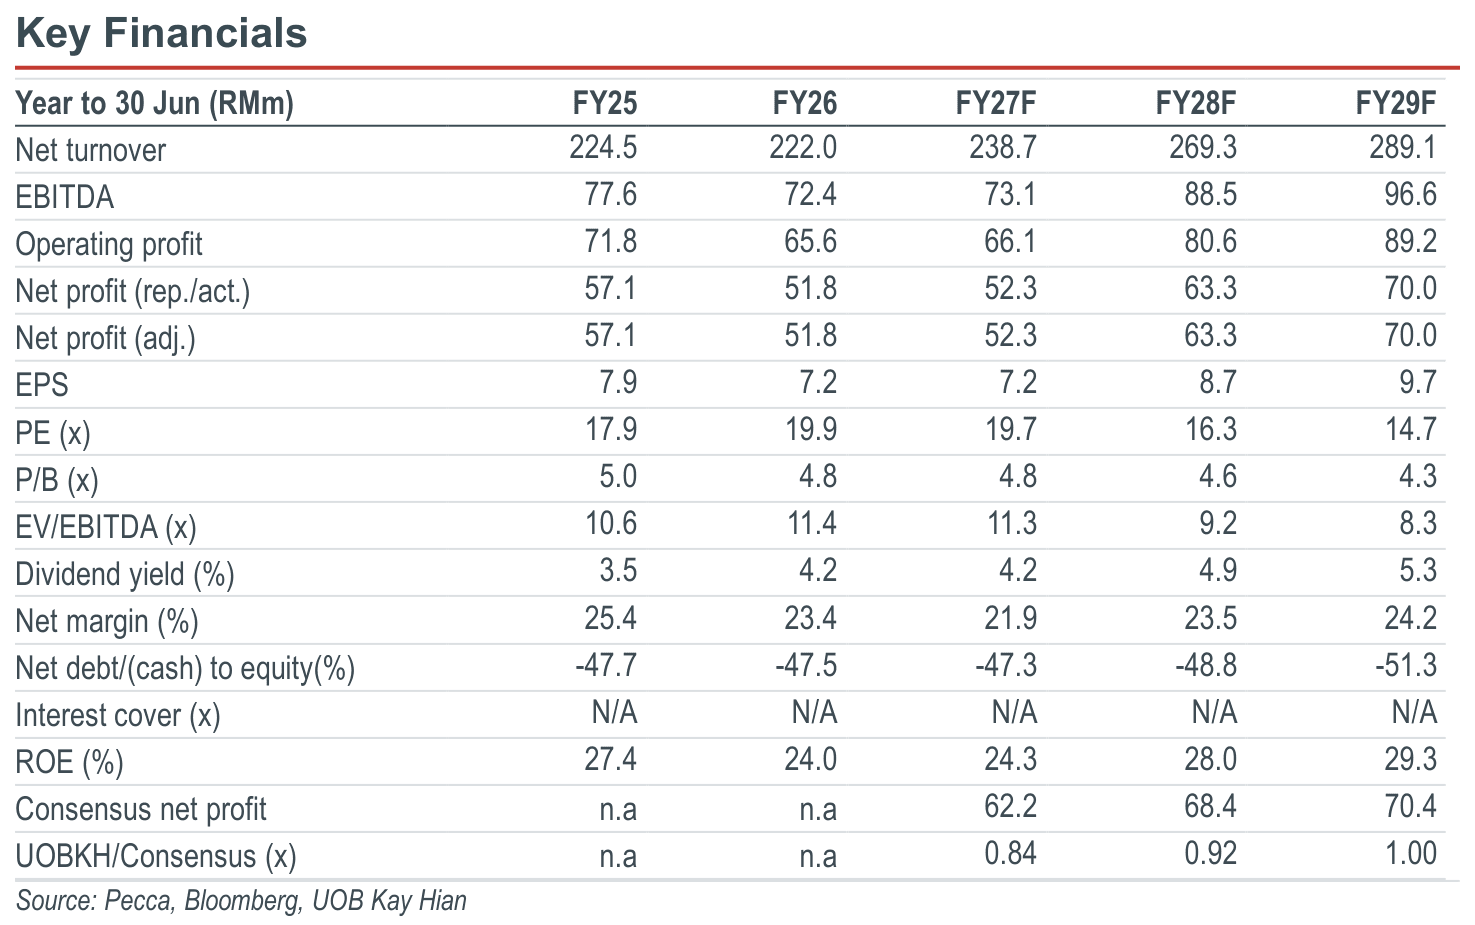
- We expect a modest earnings recovery over the coming quarters, with more meaningful growth likely to materialise after the launch of Perodua’s new model.
- Additionally, a potential MRO contract award from a local airline would be a key catalyst to the stock.
- Maintain HOLD with a lower target price of RM1.35 (from RM1.42) as current valuation appears fair, in our view.
Analysis
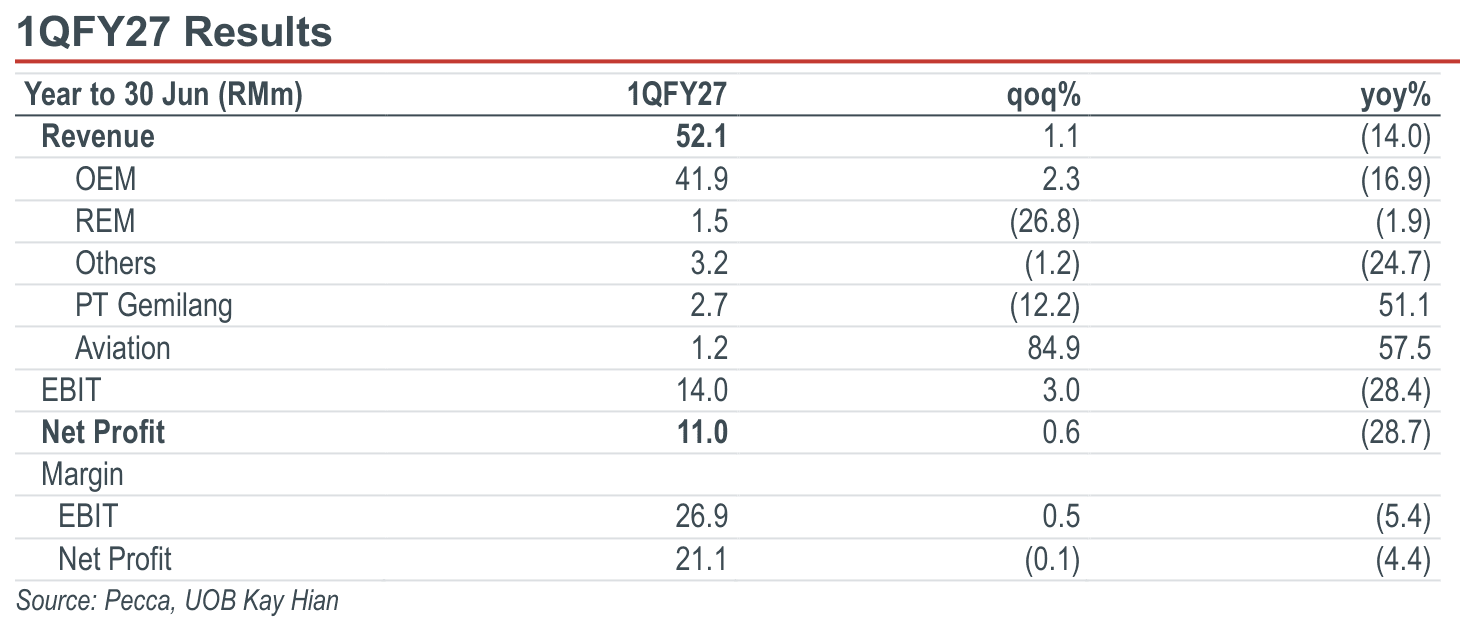
- Below expectations. Pecca Group (Pecca) reported 1QFY27 net profit of RM11.0m (+0.6% qoq, -28.7% yoy), which came in below expectations, accounting for 18% of our and consensus full-year estimates. The negative deviation was primarily attributable to weaker-than-expected order volume from key customers in the OEM segment.
Highlights
- Pecca’s 1QFY27 core net profit of RM11.0m (-9% yoy) was below expectations, accounting for 18% of our forecast, due to softer demand from key automotive customers.
- We expect a modest earnings recovery over the coming quarters, with more meaningful growth likely to materialise after the launch of Perodua’s new model.
- Additionally, a potential MRO contract award from a local airline would be a key catalyst to the stock.
- Maintain HOLD with a lower target price of RM1.35 (from RM1.42) as current valuation appears fair, in our view.
Analysis
- Below expectations. Pecca Group (Pecca) reported 1QFY27 net profit of RM11.0m (+0.6% qoq, -28.7% yoy), which came in below expectations, accounting for 18% of our and consensus full-year estimates. The negative deviation was primarily attributable to weaker-than-expected order volume from key customers in the OEM segment.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.42
RM1.35
-4.9%
RM1.42
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Oct 2026
Hartalega (HART MK): Tides Turning But Headwinds Persist

12 Nov 2026
SP Setia (SPSB MK): 3Q26: Results Miss; Slower Execution Timelines Drag Earnings

28 Oct 2026
Eco-Shop Marketing (ECOSHOP MK): 1QFY27: SSSG Turns For The Better But Earnings Disappoint
Our latest research

19 Nov 2026
Inari Amertron (INRI MK): 1QFY27: Within Expectations; A Better FY27 In The Offing

19 Nov 2026
VSTECS (VST MK): 3Q26: Within expectations; Growth Momentum To Resume In 4Q26

18 Nov 2026