Company Coverage
Eco-Shop Marketing (ECOSHOP MK): 1QFY27: SSSG Turns For The Better But Earnings Disappoint
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
RM1.42
RM1.50
5.6%
RM1.60
Analyst
Highlights
- Earnings are below expectations off largely softened gross margins, which arose from unfavourable forex and a disrupted supply chain.
- SSSG turned positive after multiple quarters of contraction but has since softened marginally again.
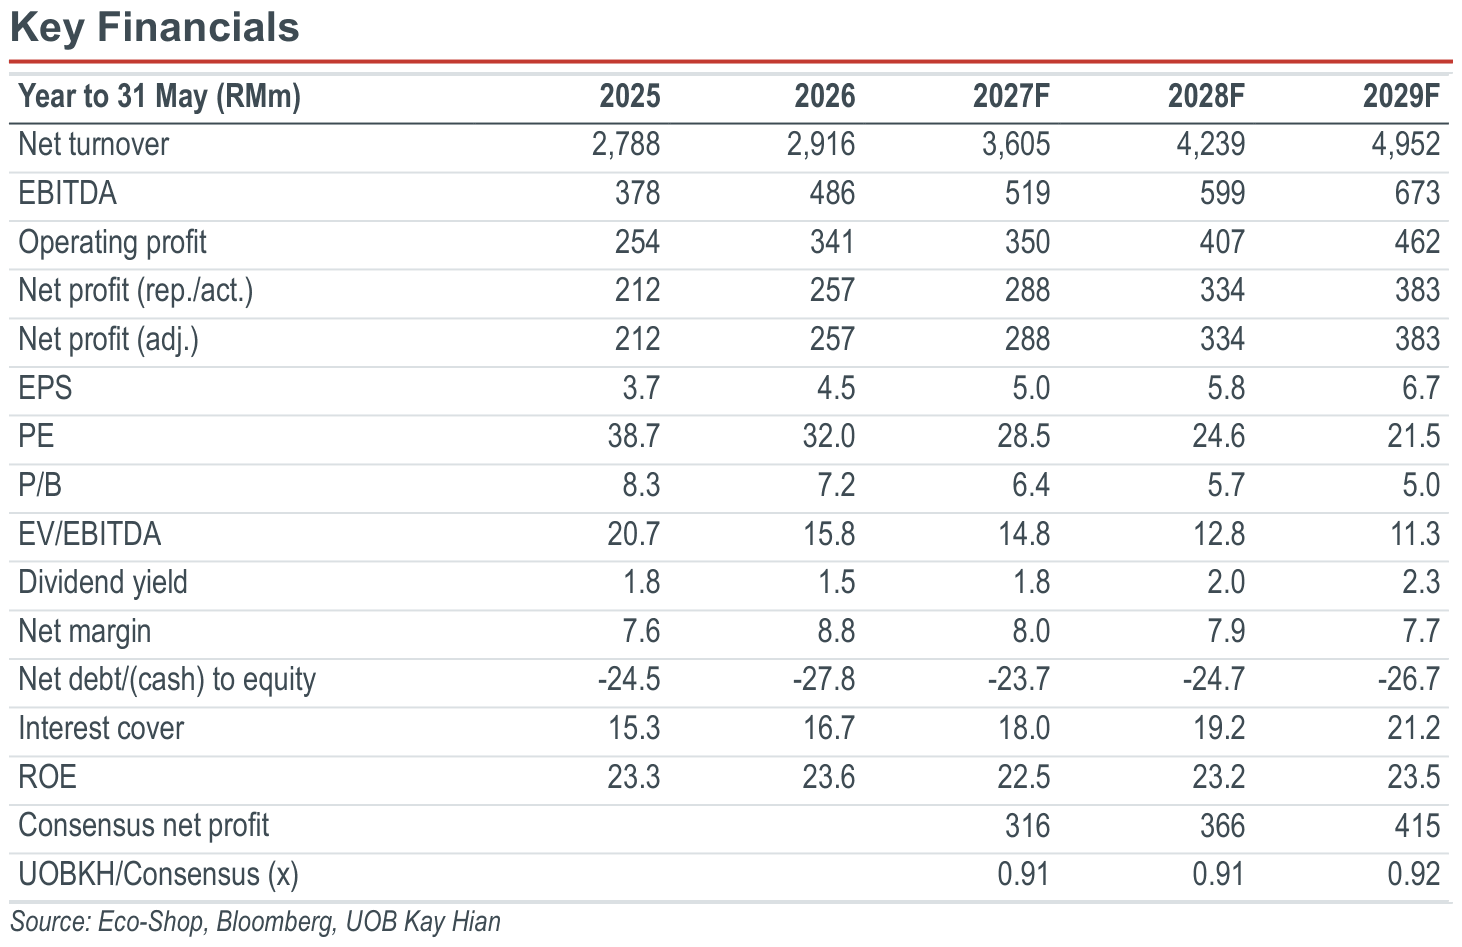
- Downgrade to HOLD as valuations no longer appear compelling following our trimmed earnings. Target price lowered to RM1.50 (from RM1.60).
Analysis
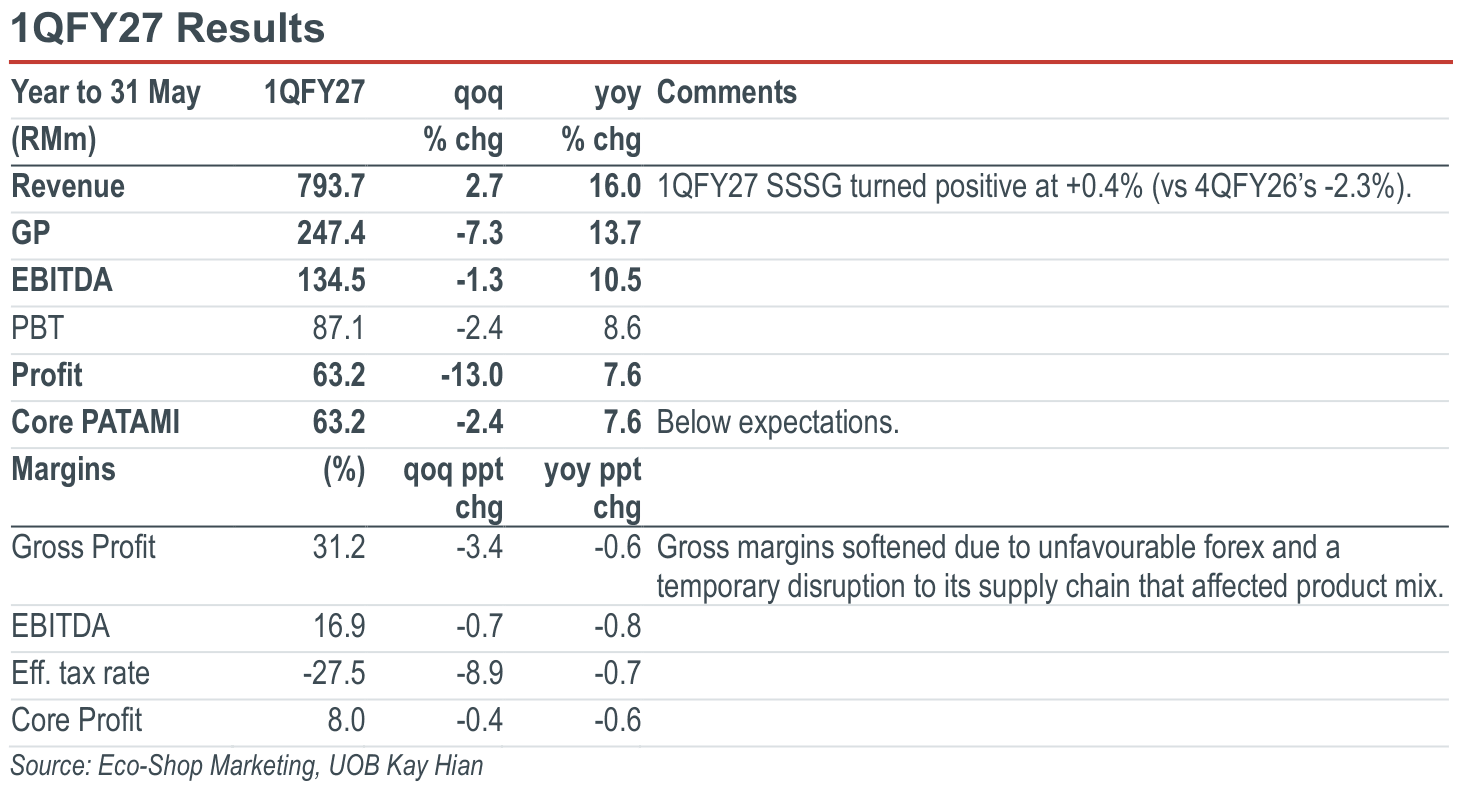
- Eco-Shop Marketing (Eco-Shop) registered a 1QFY27 core profit of RM63.2m (7.6% yoy, -2.4% qoq). This represents 20% of both our and consensus full-year forecasts, disappointing expectations. The negative variation largely arose from softer gross margins owing to unfavourable forex and a temporary disruption to its supply chain that affected its product mix, alongside a weaker SSSG outlook.
Highlights
- Earnings are below expectations off largely softened gross margins, which arose from unfavourable forex and a disrupted supply chain.
- SSSG turned positive after multiple quarters of contraction but has since softened marginally again.
- Downgrade to HOLD as valuations no longer appear compelling following our trimmed earnings. Target price lowered to RM1.50 (from RM1.60).
Analysis
- Eco-Shop Marketing (Eco-Shop) registered a 1QFY27 core profit of RM63.2m (7.6% yoy, -2.4% qoq). This represents 20% of both our and consensus full-year forecasts, disappointing expectations. The negative variation largely arose from softer gross margins owing to unfavourable forex and a temporary disruption to its supply chain that affected its product mix, alongside a weaker SSSG outlook.
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
RM1.42
RM1.50
5.6%
RM1.60
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Sept 2026
Eco-Shop Marketing (ECOSHOP MK): Prospects Intact; Macro Perspective Mixed

30 Sept 2026
VS Industry (VSI MK): 4QFY26: Turning The Corner; Deep Value Beckons

1 Sept 2026
RHB Bank (RHBBANK MK): 1H26: Resilient 1H26, Better 2H26 Ahead
Our latest research

27 Oct 2026
Gas Malaysia (GMB MK): Beneficiary Of Malaysia’s NG Supply Reform

26 Oct 2026
PPB Group (PEP MK): Resilient Wilmar Contributions Support Overall Performance

23 Oct 2026