Company Coverage
VS Industry (VSI MK): 4QFY26: Turning The Corner; Deep Value Beckons
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.235
RM0.35
+48.9%
RM0.34
Analyst
Analyst
Highlights
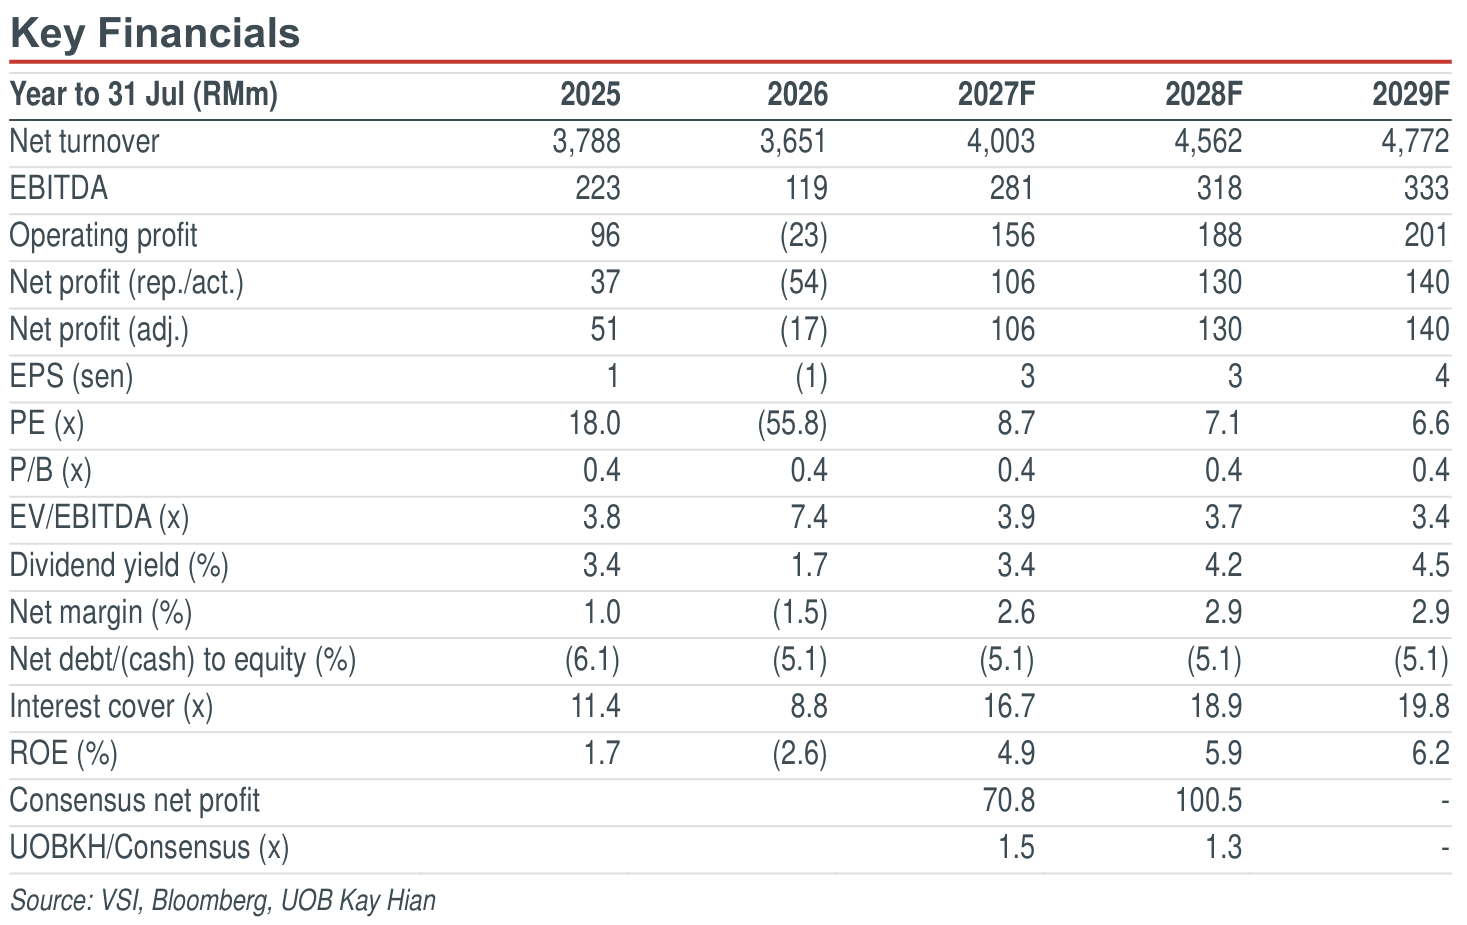
- 4QFY26 marked a return to profitability, supported by stronger volume ramp-up across its customer base and narrowing losses from loss-making divisions. We expect the recovery to gain further traction in FY27, underpinned by improving utilisation, new model launches and a steady recovery in customer orders.
- VS trades at just 8.7x FY27F PE (-1SD below historical mean) and 0.4x FY27F P/B (-2SD), well below the trough valuations seen during the MCO period (0.83-0.88x P/B), suggesting limited downside with asymmetrical upside potential.
- Maintain BUY with a higher target price of RM0.35. Key re-rating catalysts include further order normalisation, improving capacity utilisation, sustained earnings recovery, and potential new customer wins.
Analysis
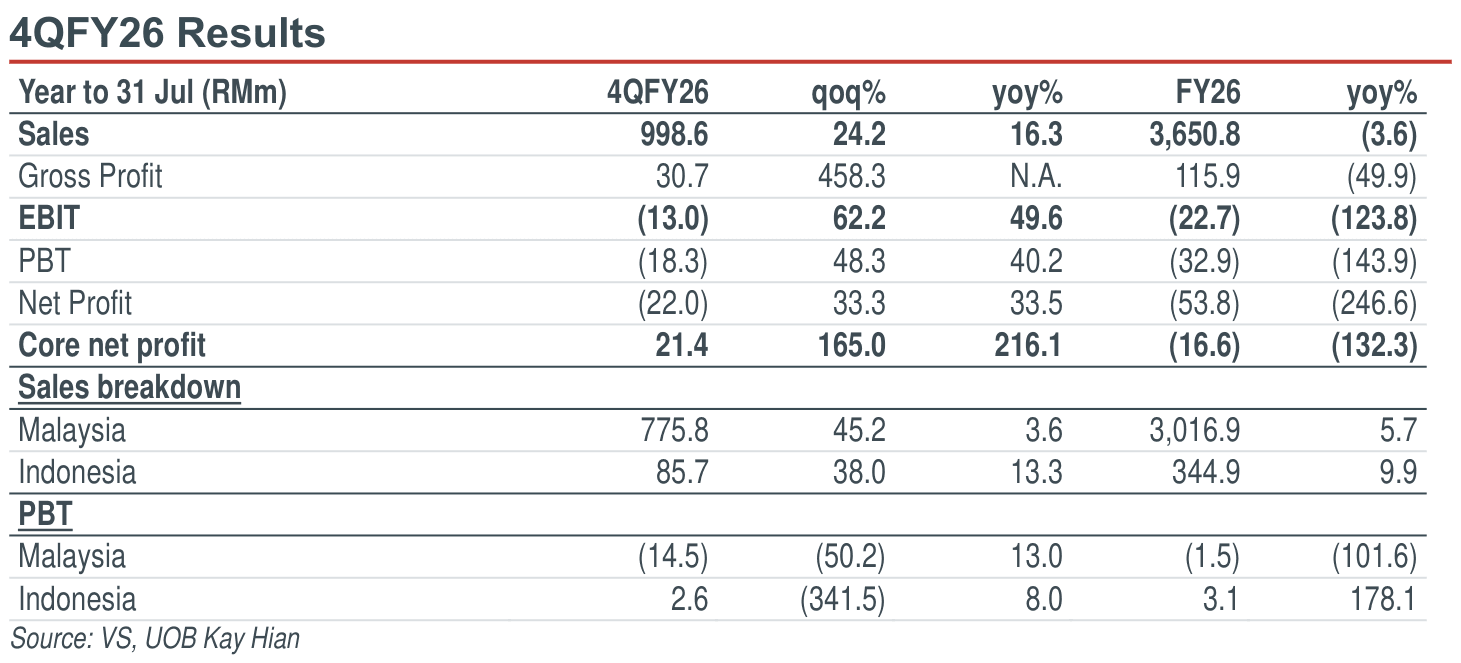
- Within expectations. VS Industry (VS) reported a 4QFY26 core net profit of RM21.4m (3QFY26: -RM32.9m; 4QFY25: -RM18.4m), which narrowed its FY26 core net loss to RM16.6m (9MFY26: -RM38.0). The results are broadly in line with our expectations but above consensus core net loss estimates of RM32.0m.
Highlights
- 4QFY26 marked a return to profitability, supported by stronger volume ramp-up across its customer base and narrowing losses from loss-making divisions. We expect the recovery to gain further traction in FY27, underpinned by improving utilisation, new model launches and a steady recovery in customer orders.
- VS trades at just 8.7x FY27F PE (-1SD below historical mean) and 0.4x FY27F P/B (-2SD), well below the trough valuations seen during the MCO period (0.83-0.88x P/B), suggesting limited downside with asymmetrical upside potential.
- Maintain BUY with a higher target price of RM0.35. Key re-rating catalysts include further order normalisation, improving capacity utilisation, sustained earnings recovery, and potential new customer wins.
Analysis
- Within expectations. VS Industry (VS) reported a 4QFY26 core net profit of RM21.4m (3QFY26: -RM32.9m; 4QFY25: -RM18.4m), which narrowed its FY26 core net loss to RM16.6m (9MFY26: -RM38.0). The results are broadly in line with our expectations but above consensus core net loss estimates of RM32.0m.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.235
RM0.35
+48.9%
RM0.34
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Oct 2026
VS Industry (VSI MK): Gradual Recovery; Diversifying For Growth

21 Aug 2026
Genting Malaysia (GENM MK): 2Q26: RWNYC Gaining Momentum, Better 2H26 Ahead

27 Aug 2026
IJM Corporation (IJM MK): 1QFY27: Above Expectations; Construction Shines Through
Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership

8 Oct 2026