Company Coverage
Fraser & Neave Holdings (FNH MK) - FY26: Below Expectations; Setup Costs Remain A Drag
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM21.22
RM30.00
+41.4%
RM36.00
Analyst
Highlights
- F&N’s FY26 earnings fell below both our and consensus estimates. Contributions from both domestic markets and Thailand came in sequentially weak as costs for new plants dragged earnings.
- As a result, F&N saw margin compression across the board as the increased costs offset largely resilient sales volumes in Malaysia and Thailand.
- Maintain BUY with a lower target price of RM30.00 as we cut our FY27/FY28 forecasts by 16%/20% respectively.
Analysis
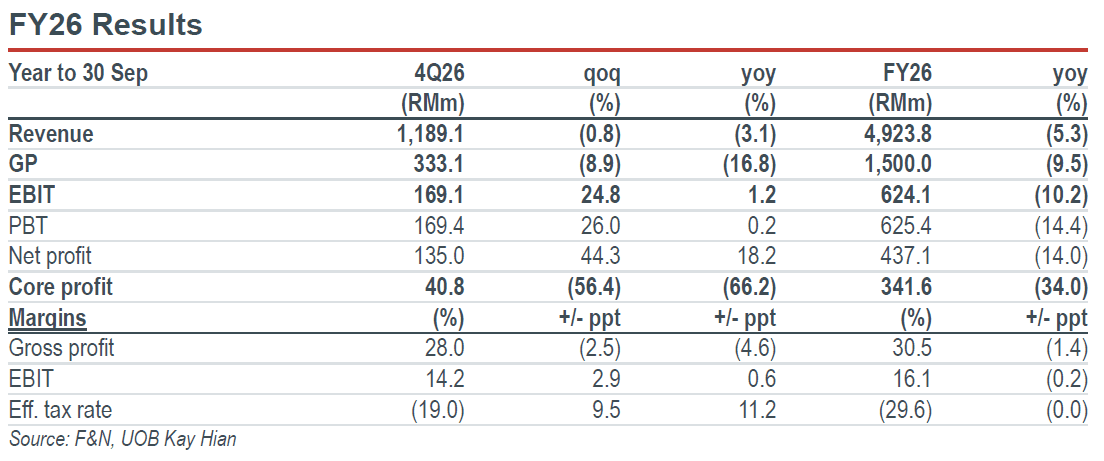
- Below expectations. Fraser & Neave (F&N) reported a core net profit of RM341.6m (-34.0% yoy) in FY26. We arrive at this after excluding: a) a RM90.5m gain from the disposal of a JV, and b) RM5.0m in foreign exchange gains. This fell below expectations, accounting for only 80% of our and 81% of consensus full-year forecasts. The negative deviation stemmed largely from higher-than-expected costs associated with the new plants in both Malaysia and Cambodia. A final dividend of 30 sen was also announced, bringing the total to 60 sen for FY26 (FY25: 65 sen).
Highlights
- F&N’s FY26 earnings fell below both our and consensus estimates. Contributions from both domestic markets and Thailand came in sequentially weak as costs for new plants dragged earnings.
- As a result, F&N saw margin compression across the board as the increased costs offset largely resilient sales volumes in Malaysia and Thailand.
- Maintain BUY with a lower target price of RM30.00 as we cut our FY27/FY28 forecasts by 16%/20% respectively.
Analysis
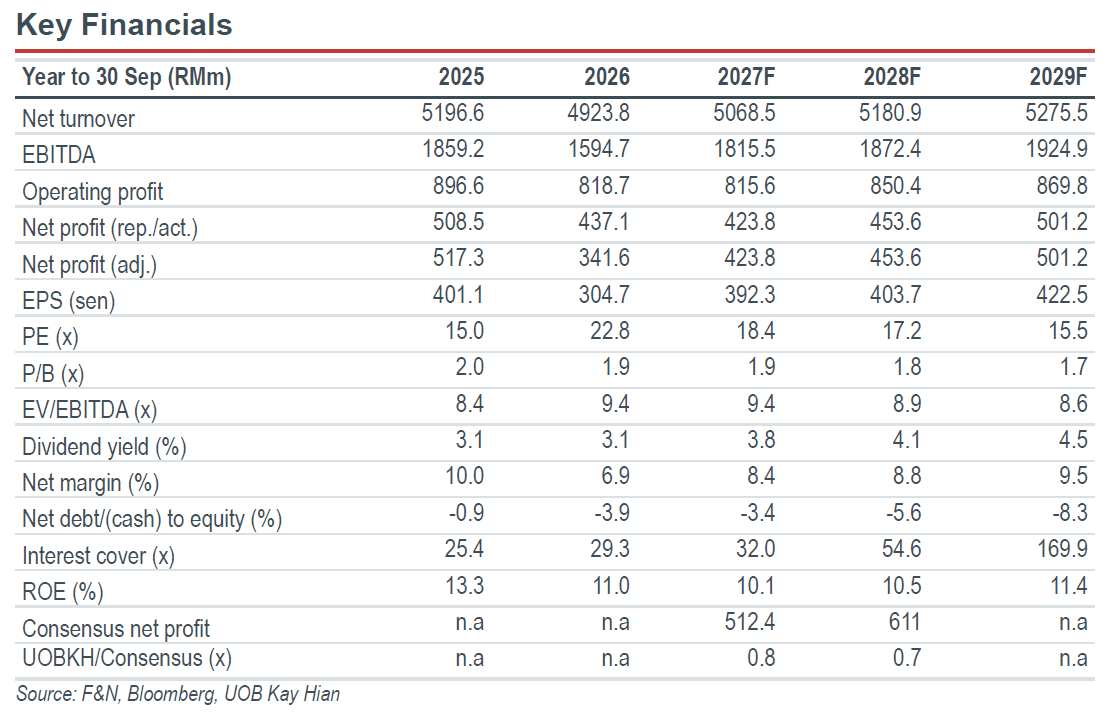
- Below expectations. Fraser & Neave (F&N) reported a core net profit of RM341.6m (-34.0% yoy) in FY26. We arrive at this after excluding: a) a RM90.5m gain from the disposal of a JV, and b) RM5.0m in foreign exchange gains. This fell below expectations, accounting for only 80% of our and 81% of consensus full-year forecasts. The negative deviation stemmed largely from higher-than-expected costs associated with the new plants in both Malaysia and Cambodia. A final dividend of 30 sen was also announced, bringing the total to 60 sen for FY26 (FY25: 65 sen).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM21.22
RM30.00
+41.4%
RM36.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Solarvest Holdings (SOLAR MK): Transforming Into A Formidable Green Power Producer By 2030

2 Nov 2026
Pekat Group (PEKAT MK): Riding The CRESS Wave Into The Next Growth Chapter

3 Nov 2026
Renewable Energy: Tailwind From Positive Regulatory Framework; Record Orderbook Wins
Our latest research

6 Nov 2026
SD Guthrie (SDG MK) - 3Q26: Within Expectations; Upstream Lifts Core Profit By 39%

4 Nov 2026
Velesto Energy (VEB MK): Rig Market Getting Tighter

2 Nov 2026