Company Coverage
SD Guthrie (SDG MK) - 3Q26: Within Expectations; Upstream Lifts Core Profit By 39%
BUY (Maintained)
Current price:
Target price:
Upside:
RM6.00
RM8.30
+38.3%
Analyst
Analyst
Highlights
SDG’s 1H26 results were broadly in line with core earnings supported by stronger CPO prices and improved downstream performance.
The group has announced two proposed outright land disposals worth a combined RM500m, supporting industrial development’s earnings pipeline.
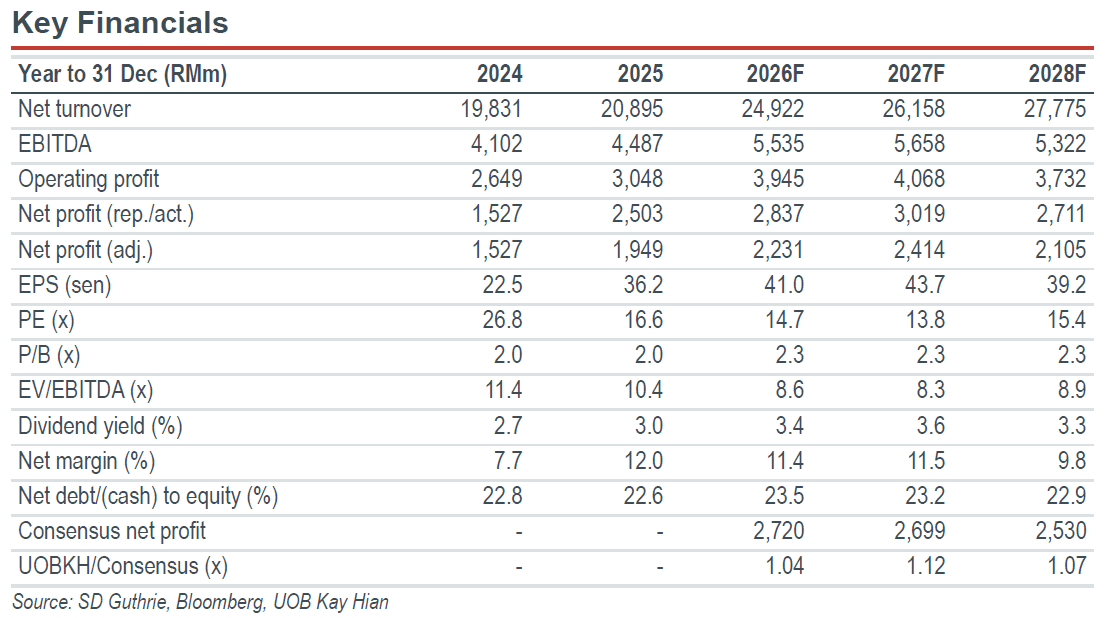
We raise our 2026-28 earnings forecasts by 10%/8%/8% as we think SDG is highly likely to meet its RM700m earnings target for the industrial division.
Maintain BUY with a higher target price of RM7.65 (previously RM7.25), pegged to 20x 2027F PE.
Analysis
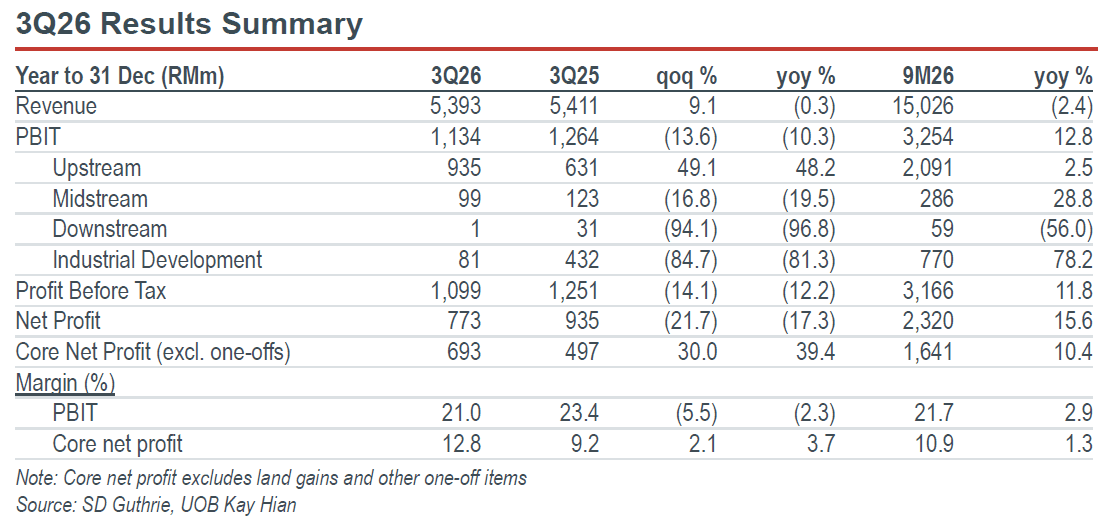
- Upstream drove the quarter. Upstream PBIT rose 48% yoy to RM935m. Indonesian PBIT nearly quadrupled to RM264m as FFB output rose 23% yoy, with newer areas reaching prime age after accelerated replanting. Malaysian PBIT rose 26% to RM517m on 4% higher FFB output and a 6% higher realised CPO price of RM4,548/tonne. Papua New Guinea (PNG) and the Solomon Islands PBIT were flat at RM154m as dry weather cut output by 2%.
- Midstream and downstream softens. Midstream PBIT fell 20% yoy to RM99m on inventory provisions in bulk refining after CPO prices eased, although trading rose 35% to RM88m. Downstream PBIT was only RM1m (3Q25: RM31m) on weaker margins in Asia Pacific and Europe and losses at the Emery JV.
Highlights
SDG’s 1H26 results were broadly in line with core earnings supported by stronger CPO prices and improved downstream performance.
The group has announced two proposed outright land disposals worth a combined RM500m, supporting industrial development’s earnings pipeline.
We raise our 2026-28 earnings forecasts by 10%/8%/8% as we think SDG is highly likely to meet its RM700m earnings target for the industrial division.
Maintain BUY with a higher target price of RM7.65 (previously RM7.25), pegged to 20x 2027F PE.
Analysis
- Upstream drove the quarter. Upstream PBIT rose 48% yoy to RM935m. Indonesian PBIT nearly quadrupled to RM264m as FFB output rose 23% yoy, with newer areas reaching prime age after accelerated replanting. Malaysian PBIT rose 26% to RM517m on 4% higher FFB output and a 6% higher realised CPO price of RM4,548/tonne. Papua New Guinea (PNG) and the Solomon Islands PBIT were flat at RM154m as dry weather cut output by 2%.
- Midstream and downstream softens. Midstream PBIT fell 20% yoy to RM99m on inventory provisions in bulk refining after CPO prices eased, although trading rose 35% to RM88m. Downstream PBIT was only RM1m (3Q25: RM31m) on weaker margins in Asia Pacific and Europe and losses at the Emery JV.
BUY (Maintained)
Current price:
Target price:
Upside:
RM6.00
RM8.30
+38.3%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

25 Sept 2026
Eco World Development (ECW MK): 3QFY26: In Line; Poised To Achieve Record Sales

29 Oct 2026
CTOS Digital (CTOS MK): 3Q26: Within Expectations; Trudging Across Choppy Seas

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine
Our latest research

6 Nov 2026
Fraser & Neave Holdings (FNH MK) - FY26: Below Expectations; Setup Costs Remain A Drag

4 Nov 2026
Velesto Energy (VEB MK): Rig Market Getting Tighter
2 Nov 2026