Company Coverage
Solarvest Holdings (SOLAR MK): Transforming Into A Formidable Green Power Producer By 2030
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM4.31
RM5.30
+23.0%
RM4.20
Analyst
Analyst
Highlights
- We raised FY29 net profit forecasts by 29%, capturing RM5b orderbook against a backdrop of 300-500MW CRESS wins and 20-25% LSS6 EPCC market share.
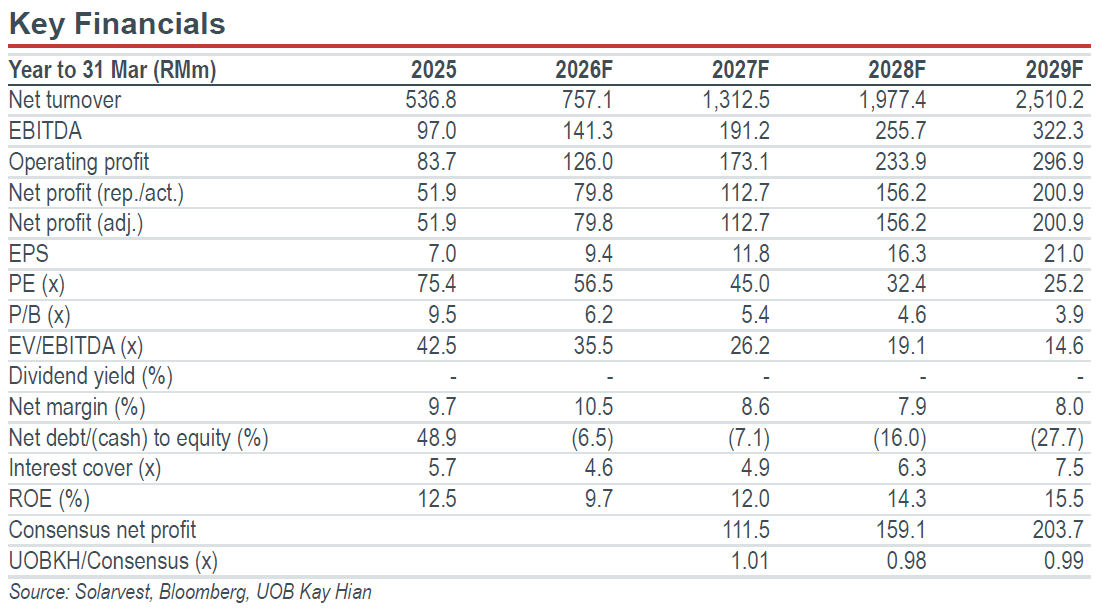
- Net profit will gradually peak at RM200m in FY29, driving ROE to an impressive 15.5% (FY26: 10%). This underscores Solarvest’s management prowess in driving earnings growth over time.
- We lift our target price to RM5.30/ share, ahead of the market. This captures: a) a RM4.60/share valuation for EPCC business; and b) a RM0.70/share valuation for 500MW CRESS asset ownership. Our blue-sky fair value is RM7.50/share assuming 2GW CRESS ownership. Maintain BUY; target price: RM5.30.
Analysis
- 500MW CRESS; raised FY28 net profit by 26%. Solarvest Holdings (Solarvest) looks to double orderbook from RM2.5b to RM5b in the near term. This comes on the back of the CRESS Acceleration Package announced in September, with a potential 300-500MW CRESS contract win in 4Q26/1Q27 as well as Large Scale Solar 6 (LSS6) wins. Importantly, we believe the group is also well positioned to win an additional 300-500MW of CRESS contracts from other DC players, lifting base case RM5b orderbook to RM7b (blue sky).
- Earnings to peak in FY29. Based on its RM5b orderbook and an 8% net margin assumption, we raise FY29 net profit forecasts by 26% (from RM160m to RM200m), as we spread the RM5b base case orderbook over FY28-29. We now project a three-year earnings CAGR of 36% (FY27-29). Sizeable landbank access is a key advantage to all solar players and we believe Solarvest is well ahead of the curve in terms of strategic landbanking activity.
- Fair value of RM5.30; blue-sky RM7.30. In tandem with the increase in earnings, we raised our fair value to RM5.30/share. We transition from PER to SOTP valuation to capture the intrinsic value of CRESS power assets. Essentially, sizeable power asset ownership pivots Solarvest into a green independent power producer (IPP) in the long run. This underpins long-term earnings visibility, and cashflow prowess will pave the way for lush dividend payouts. Our SOTP methodology captures: a) RM4.60/share for RE EPCC orderbook; and b) RM0.70/share for long-term CRESS power assets. We assume Solarvest can win 500MW CRESS contracts in the near term. Our blue-sky fair value for Solarvest is RM7.30/share, assuming 2GW of power generation assets. See our fair value analysis overleaf.
Highlights
- We raised FY29 net profit forecasts by 29%, capturing RM5b orderbook against a backdrop of 300-500MW CRESS wins and 20-25% LSS6 EPCC market share.
- Net profit will gradually peak at RM200m in FY29, driving ROE to an impressive 15.5% (FY26: 10%). This underscores Solarvest’s management prowess in driving earnings growth over time.
- We lift our target price to RM5.30/ share, ahead of the market. This captures: a) a RM4.60/share valuation for EPCC business; and b) a RM0.70/share valuation for 500MW CRESS asset ownership. Our blue-sky fair value is RM7.50/share assuming 2GW CRESS ownership. Maintain BUY; target price: RM5.30.
Analysis
- 500MW CRESS; raised FY28 net profit by 26%. Solarvest Holdings (Solarvest) looks to double orderbook from RM2.5b to RM5b in the near term. This comes on the back of the CRESS Acceleration Package announced in September, with a potential 300-500MW CRESS contract win in 4Q26/1Q27 as well as Large Scale Solar 6 (LSS6) wins. Importantly, we believe the group is also well positioned to win an additional 300-500MW of CRESS contracts from other DC players, lifting base case RM5b orderbook to RM7b (blue sky).
- Earnings to peak in FY29. Based on its RM5b orderbook and an 8% net margin assumption, we raise FY29 net profit forecasts by 26% (from RM160m to RM200m), as we spread the RM5b base case orderbook over FY28-29. We now project a three-year earnings CAGR of 36% (FY27-29). Sizeable landbank access is a key advantage to all solar players and we believe Solarvest is well ahead of the curve in terms of strategic landbanking activity.
- Fair value of RM5.30; blue-sky RM7.30. In tandem with the increase in earnings, we raised our fair value to RM5.30/share. We transition from PER to SOTP valuation to capture the intrinsic value of CRESS power assets. Essentially, sizeable power asset ownership pivots Solarvest into a green independent power producer (IPP) in the long run. This underpins long-term earnings visibility, and cashflow prowess will pave the way for lush dividend payouts. Our SOTP methodology captures: a) RM4.60/share for RE EPCC orderbook; and b) RM0.70/share for long-term CRESS power assets. We assume Solarvest can win 500MW CRESS contracts in the near term. Our blue-sky fair value for Solarvest is RM7.30/share, assuming 2GW of power generation assets. See our fair value analysis overleaf.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM4.31
RM5.30
+23.0%
RM4.20
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Pekat Group (PEKAT MK): Riding The CRESS Wave Into The Next Growth Chapter

10 Sept 2026
VSTECS (VST MK): AI Infrastructure Demand Broadens; Momentum Building Into 2H26

8 Oct 2026
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility
Our latest research

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine
2 Nov 2026
Pekat Group (PEKAT MK): Riding The CRESS Wave Into The Next Growth Chapter

30 Oct 2026