Company Coverage
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.16
RM1.40
+20.7%
RM1.00
Analyst
Analyst
Highlights
- Northern Solar has secured an additional RM34m utility-scale EPCC contract under the LSS5 programme, underpinning earnings visibility over FY27-28. NS also recently completed its transfer to Bursa’s Main Board on 6 Oct 26.
- Blue-sky scenario: Winning a sizeable CRESS project will lift valuation by RM320m (20x PER; RM18m net profit based on 80% equity stake). This suggests a blue-sky fair value of RM2.20/share within a three-year time frame.
- We maintain our BUY call on the stock with a higher PE-based target price of RM1.40/share, based on 15x PE versus sector average 19x PE. The sector will continue to benefit from strong orderbook with the CRESS accelerated programme and LSS6.
Analysis
- Another LSS5 contract win... Northern Solar (NS) has secured another utility-scale engineering, procurement, construction and commissioning (EPCC) contract under the LSS5 programme valued at RM34m. This marks the group’s second utility-scale project win in the span of a year. The 9.5MWac project is slated for commissioning by 1 May 27, with the bulk of contributions expected to be recognised in FY27 (~80% of contract value). We expect a healthy net margin of 7-9% for the above project.
- …lifting orderbook to a record RM223m. NS commands a record orderbook of RM223m, primarily anchored by its two LSS5 ECC and EPCC contracts (64%), with more contributions from rooftop solar photovoltaic (PV) projects across the commercial and industrial (C&I) (27%) and residential (15%) segments. Moving ahead, the company aims to achieve a steady top-line run rate of: a) RM100m p.a. for C&I solar installation; b) RM60-80m p.a. for the residential segment; and c) 5-10% annual revenue mix from its standalone and bundled battery energy storage system (BESS) projects.
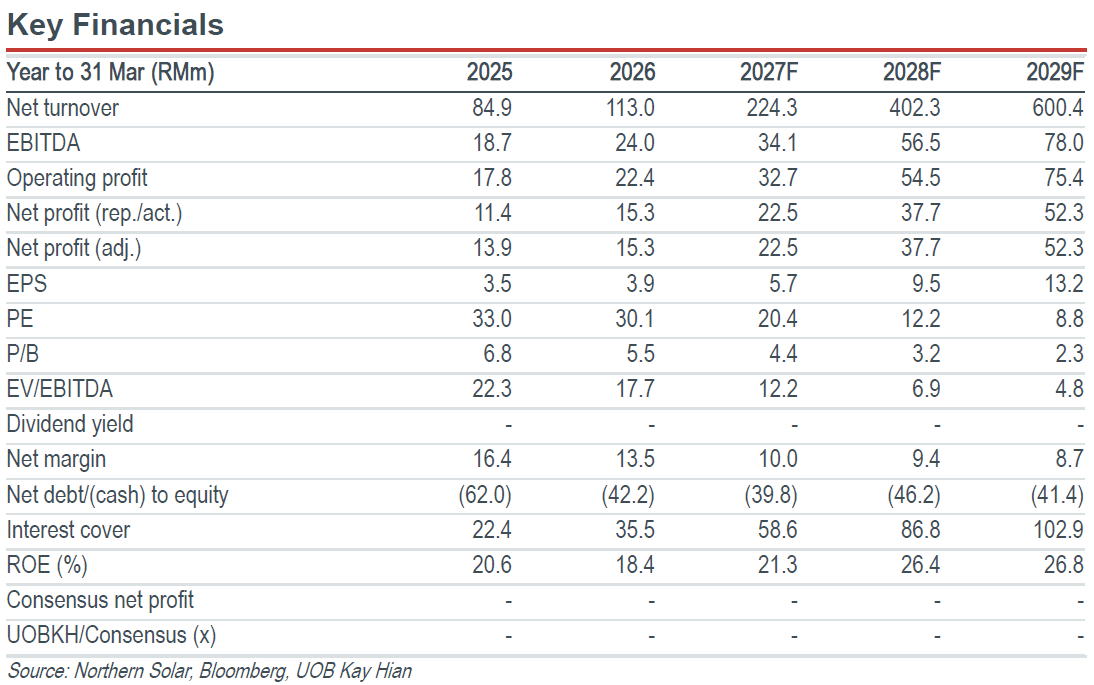
- Strong earnings visibility. With the inclusion of this second LSS5 contract win, we expect NS to deliver a robust full-year FY27 net profit growth of 50% yoy. FY27 revenue is expected to double on the back of: a) RM120m + RM34m LSS5 project execution, b) improving commercial and industrial (C&I) demand as businesses seek to mitigate rising electricity costs, and c) a recovery in residential rooftop solar installations supported by a RM3,000 SuRIA Home rebate. NS derived 85% of its revenue from the C&I segment.
Highlights
- Northern Solar has secured an additional RM34m utility-scale EPCC contract under the LSS5 programme, underpinning earnings visibility over FY27-28. NS also recently completed its transfer to Bursa’s Main Board on 6 Oct 26.
- Blue-sky scenario: Winning a sizeable CRESS project will lift valuation by RM320m (20x PER; RM18m net profit based on 80% equity stake). This suggests a blue-sky fair value of RM2.20/share within a three-year time frame.
- We maintain our BUY call on the stock with a higher PE-based target price of RM1.40/share, based on 15x PE versus sector average 19x PE. The sector will continue to benefit from strong orderbook with the CRESS accelerated programme and LSS6.
Analysis
- Another LSS5 contract win... Northern Solar (NS) has secured another utility-scale engineering, procurement, construction and commissioning (EPCC) contract under the LSS5 programme valued at RM34m. This marks the group’s second utility-scale project win in the span of a year. The 9.5MWac project is slated for commissioning by 1 May 27, with the bulk of contributions expected to be recognised in FY27 (~80% of contract value). We expect a healthy net margin of 7-9% for the above project.
- …lifting orderbook to a record RM223m. NS commands a record orderbook of RM223m, primarily anchored by its two LSS5 ECC and EPCC contracts (64%), with more contributions from rooftop solar photovoltaic (PV) projects across the commercial and industrial (C&I) (27%) and residential (15%) segments. Moving ahead, the company aims to achieve a steady top-line run rate of: a) RM100m p.a. for C&I solar installation; b) RM60-80m p.a. for the residential segment; and c) 5-10% annual revenue mix from its standalone and bundled battery energy storage system (BESS) projects.
- Strong earnings visibility. With the inclusion of this second LSS5 contract win, we expect NS to deliver a robust full-year FY27 net profit growth of 50% yoy. FY27 revenue is expected to double on the back of: a) RM120m + RM34m LSS5 project execution, b) improving commercial and industrial (C&I) demand as businesses seek to mitigate rising electricity costs, and c) a recovery in residential rooftop solar installations supported by a RM3,000 SuRIA Home rebate. NS derived 85% of its revenue from the C&I segment.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.16
RM1.40
+20.7%
RM1.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership

7 Oct 2026