Company Coverage
PPB Group (PEP MK): Resilient Wilmar Contributions Support Overall Performance
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM8.78
RM12.55
42.7%
RM13.60
Analyst
Highlights
- We remain positive on PPB’s overall prospects, underpinned by resilient contributions from Wilmar and stronger performance expected from the film segment.
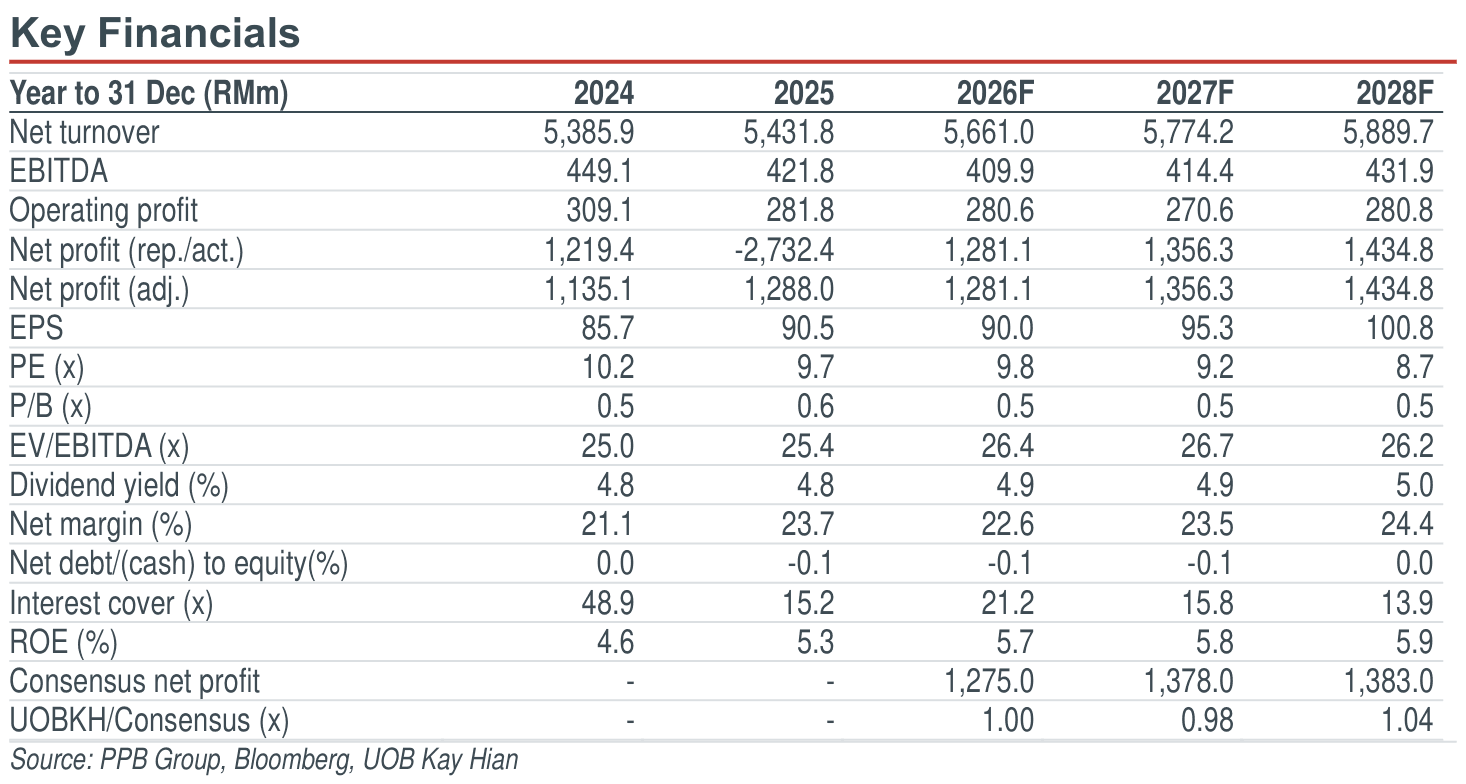
- However, the grains & agribusiness segment could remain a drag amid volatile commodity prices and elevated logistic costs with margin pressure to become more pronounced in 2H26. As such, we trim our 2026/27F forecasts by 2%/4%, reflecting conservative margin assumptions for this segment.
- Maintain BUY with a target price of RM12.55, as we believe much of the downside has already been priced in, with the stock currently trading close to -1SD of its five-year mean.
Analysis
- We remain positive on PPB Group’s (PPB) overall prospects, underpinned by resilient earnings contributions from Wilmar, its defensive staple businesses and a strong balance sheet. While the grains & agribusiness and consumer segments are expected to remain a drag on overall performance, improving performance from film exhibition and Wilmar’s resilient contributions should support the group’s overall earnings in 2026.
- Grains & agribusiness: Supply risk remains manageable. Global wheat prices have recently retreated from their Aug 26 peaks following stronger-than-expected Australia production and higher supply availability from Russia. Nevertheless, renewed tensions in the Black Sea, which account for around 20% of global wheat supplies, could continue to drive price volatility in the near term. We believe PPB’s exposure to supply disruptions remain relatively limited, as the group sources most of its wheat (flour feedstock) from Australia, where production is expected to remain above the country’s long-term average, supported by favourable rainfall conditions during mid-26.
- Margins pressure is likely to become more pronounced in 2H26. Commodity price volatility and higher logistic costs remain key concerns for the grains & agribusiness segment, with the impact on the segment’s margin expected to become more pronounced in 2H26 as existing hedging arrangements gradually expire. PPB’s hedging policy, which covers up to six months of requirements, provides some near-term cost visibility but may delay the pass-through of changes in input costs. We note that the group is unlikely to raise prices for consumer-pack flour, given that margins remain positive at current price levels. However, PPB has relatively greater pricing flexibility for industrial customers, which remains the key earnings contributor within the flour milling segment.
Highlights
- We remain positive on PPB’s overall prospects, underpinned by resilient contributions from Wilmar and stronger performance expected from the film segment.
- However, the grains & agribusiness segment could remain a drag amid volatile commodity prices and elevated logistic costs with margin pressure to become more pronounced in 2H26. As such, we trim our 2026/27F forecasts by 2%/4%, reflecting conservative margin assumptions for this segment.
- Maintain BUY with a target price of RM12.55, as we believe much of the downside has already been priced in, with the stock currently trading close to -1SD of its five-year mean.
Analysis
- We remain positive on PPB Group’s (PPB) overall prospects, underpinned by resilient earnings contributions from Wilmar, its defensive staple businesses and a strong balance sheet. While the grains & agribusiness and consumer segments are expected to remain a drag on overall performance, improving performance from film exhibition and Wilmar’s resilient contributions should support the group’s overall earnings in 2026.
- Grains & agribusiness: Supply risk remains manageable. Global wheat prices have recently retreated from their Aug 26 peaks following stronger-than-expected Australia production and higher supply availability from Russia. Nevertheless, renewed tensions in the Black Sea, which account for around 20% of global wheat supplies, could continue to drive price volatility in the near term. We believe PPB’s exposure to supply disruptions remain relatively limited, as the group sources most of its wheat (flour feedstock) from Australia, where production is expected to remain above the country’s long-term average, supported by favourable rainfall conditions during mid-26.
- Margins pressure is likely to become more pronounced in 2H26. Commodity price volatility and higher logistic costs remain key concerns for the grains & agribusiness segment, with the impact on the segment’s margin expected to become more pronounced in 2H26 as existing hedging arrangements gradually expire. PPB’s hedging policy, which covers up to six months of requirements, provides some near-term cost visibility but may delay the pass-through of changes in input costs. We note that the group is unlikely to raise prices for consumer-pack flour, given that margins remain positive at current price levels. However, PPB has relatively greater pricing flexibility for industrial customers, which remains the key earnings contributor within the flour milling segment.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM8.78
RM12.55
42.7%
RM13.60
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Oct 2026
CIMB Group (CIMB MK): Resilient Outlook Despite Bond Headwinds

11 Sept 2026
Bermaz Auto (BAUTO MK): 1QFY27: Above Expectations; New CX-5 To Support Sales Momentum

18 Sept 2026
Binastra Corporation Group (BNASTRA MK): 2QFY27: Yielding Impressively
Our latest research

23 Oct 2026
Hartalega (HART MK): Tides Turning But Headwinds Persist

22 Oct 2026
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%

22 Oct 2026