Company Coverage
Westports Holdings (WPRTS MK): 3Q26: Conventional Business Outperforms Container
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM6.77
RM7.00
+3.4%
RM6.50
Analyst
Highlights
- 9M26 core profit beat expectations. Unlike 1H26 where container yields drove the results outperformance, the conventional business outperformed container revenues on both yield and volume growth that had become material despite its small contribution to group earnings.
- Other 3Q26 takeaways. The company recorded the real normalisation of VAS income, and full delivery of E-trucks, though we assume the deployment will be gradual hence unlikely to result in immediate fuel savings. WPRTS’s timely rollout of the additional TGS helped cope with unexpected yard congestion.
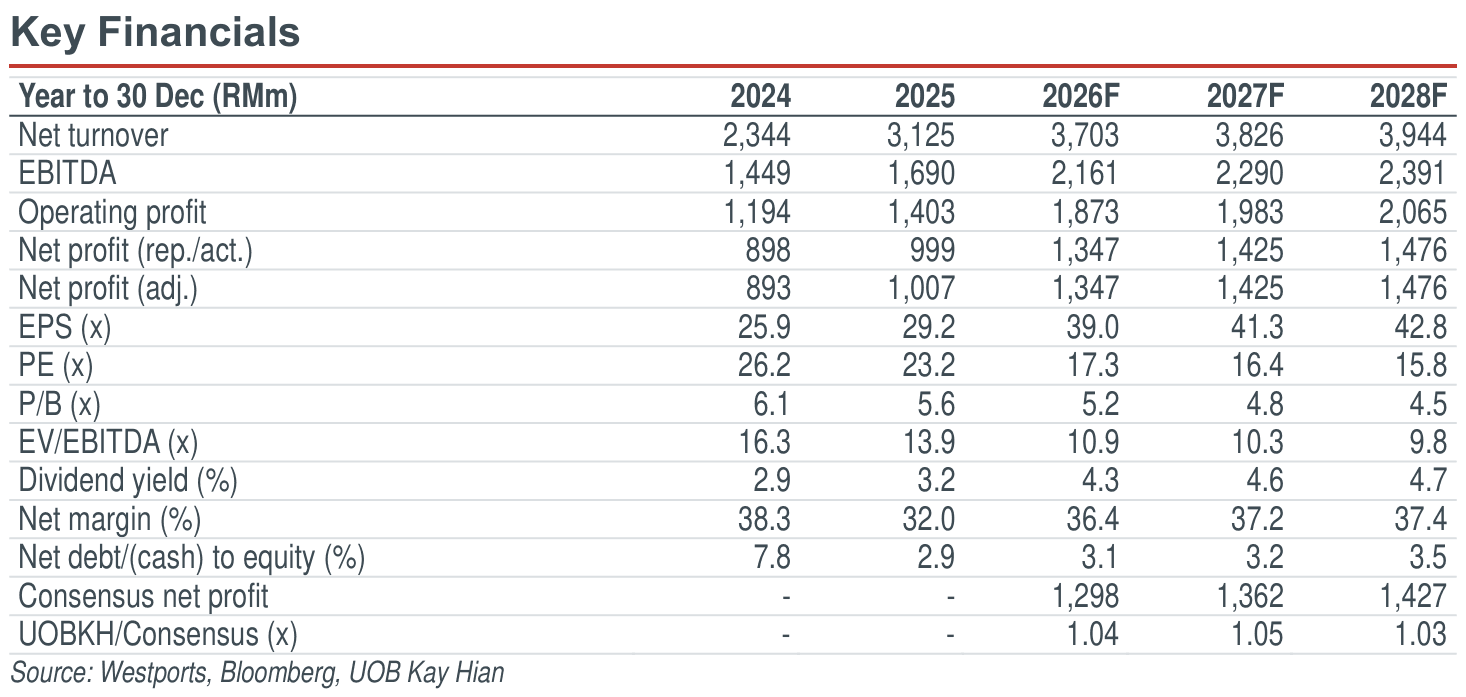
- Volume growth should remain resilient, even if interest rates start to pivot upward due to inflation. Retain HOLD. Target price adjusted to RM7.00.
Analysis
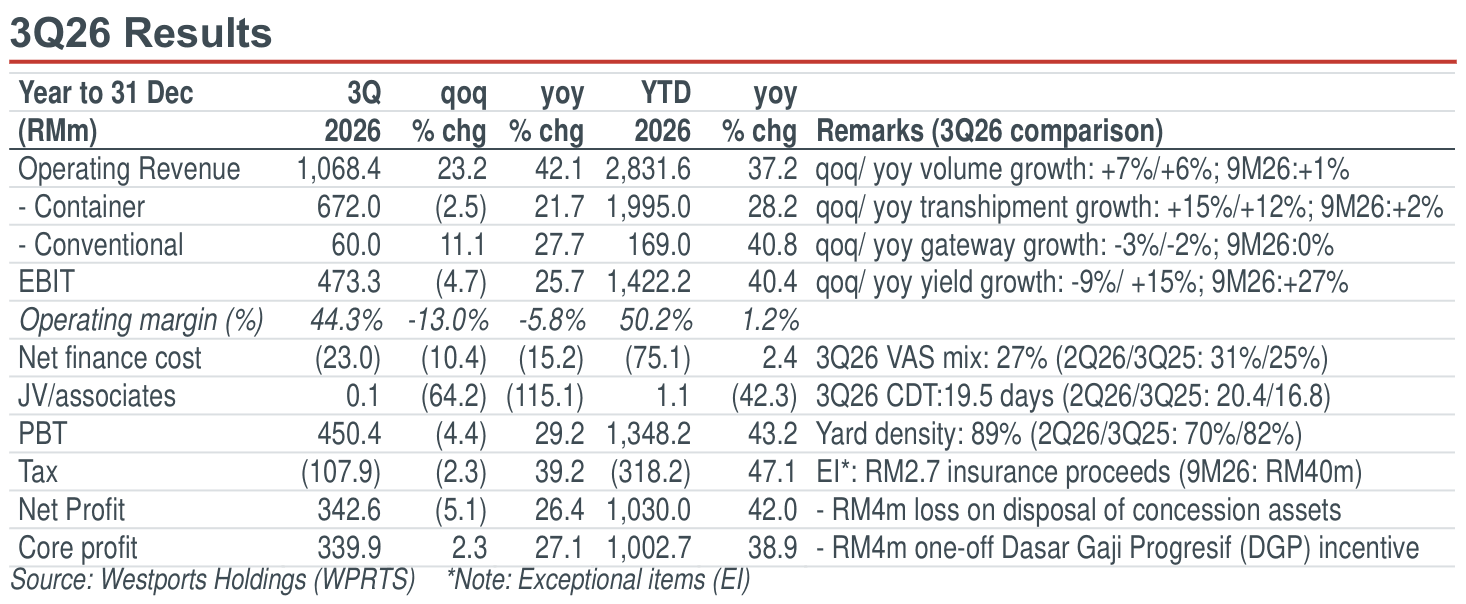
- 9M26 profit exceeded expectations, accounting for 79%/78% of our/consensus forecasts respectively. While exceptional VAS was the primary driver for the 1H26 results outperformance, 3Q26’s positive deviation is due to a stronger conventional business, whose contribution had always been small relative to container (historically, conventional revenue mix ranged between 5-8%). However, 9M26 revenue growth of 40% outperformed container’s 28%, as it benefitted from the tariff hike and also saw a strong 11% volume growth in contrast to a flattish gateway container growth. Westports’ (WPRTS) conventional business may have become a better reflection of Malaysia’s domestic economic resilience, vs gateway (where imports’ contraction outweighed export growth).
- 3Q26 VAS mix fell qoq from 31% to 27%, alongside a lower gateway mix which trended closer to 40%; this is likely the first qoq contraction (of 15%) since 2025 and the tariff hike. Container yields ex-VAS expanded by 3% qoq and 19% yoy, consistent with the two phases of tariff hikes since Jul 25.
Highlights
- 9M26 core profit beat expectations. Unlike 1H26 where container yields drove the results outperformance, the conventional business outperformed container revenues on both yield and volume growth that had become material despite its small contribution to group earnings.
- Other 3Q26 takeaways. The company recorded the real normalisation of VAS income, and full delivery of E-trucks, though we assume the deployment will be gradual hence unlikely to result in immediate fuel savings. WPRTS’s timely rollout of the additional TGS helped cope with unexpected yard congestion.
- Volume growth should remain resilient, even if interest rates start to pivot upward due to inflation. Retain HOLD. Target price adjusted to RM7.00.
Analysis
- 9M26 profit exceeded expectations, accounting for 79%/78% of our/consensus forecasts respectively. While exceptional VAS was the primary driver for the 1H26 results outperformance, 3Q26’s positive deviation is due to a stronger conventional business, whose contribution had always been small relative to container (historically, conventional revenue mix ranged between 5-8%). However, 9M26 revenue growth of 40% outperformed container’s 28%, as it benefitted from the tariff hike and also saw a strong 11% volume growth in contrast to a flattish gateway container growth. Westports’ (WPRTS) conventional business may have become a better reflection of Malaysia’s domestic economic resilience, vs gateway (where imports’ contraction outweighed export growth).
- 3Q26 VAS mix fell qoq from 31% to 27%, alongside a lower gateway mix which trended closer to 40%; this is likely the first qoq contraction (of 15%) since 2025 and the tariff hike. Container yields ex-VAS expanded by 3% qoq and 19% yoy, consistent with the two phases of tariff hikes since Jul 25.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM6.77
RM7.00
+3.4%
RM6.50
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

7 Sept 2026
Westports Holdings (WPRTS MK): Adaptation Is Ports Industry’s Proven Business Model For Resilience

5 Oct 2026
Telekom Malaysia (T MK): On Stronger Footing

22 Oct 2026
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%
Our latest research
22 Oct 2026
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%

21 Oct 2026
CIMB Group (CIMB MK): Resilient Outlook Despite Bond Headwinds

19 Oct 2026