Company Coverage
99 Speed Mart Retail Holdings (99SMART MK): 9M26: Within Expectations; SSSG Remains Robust
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.96
RM4.00
35.1%
Analyst
Highlights
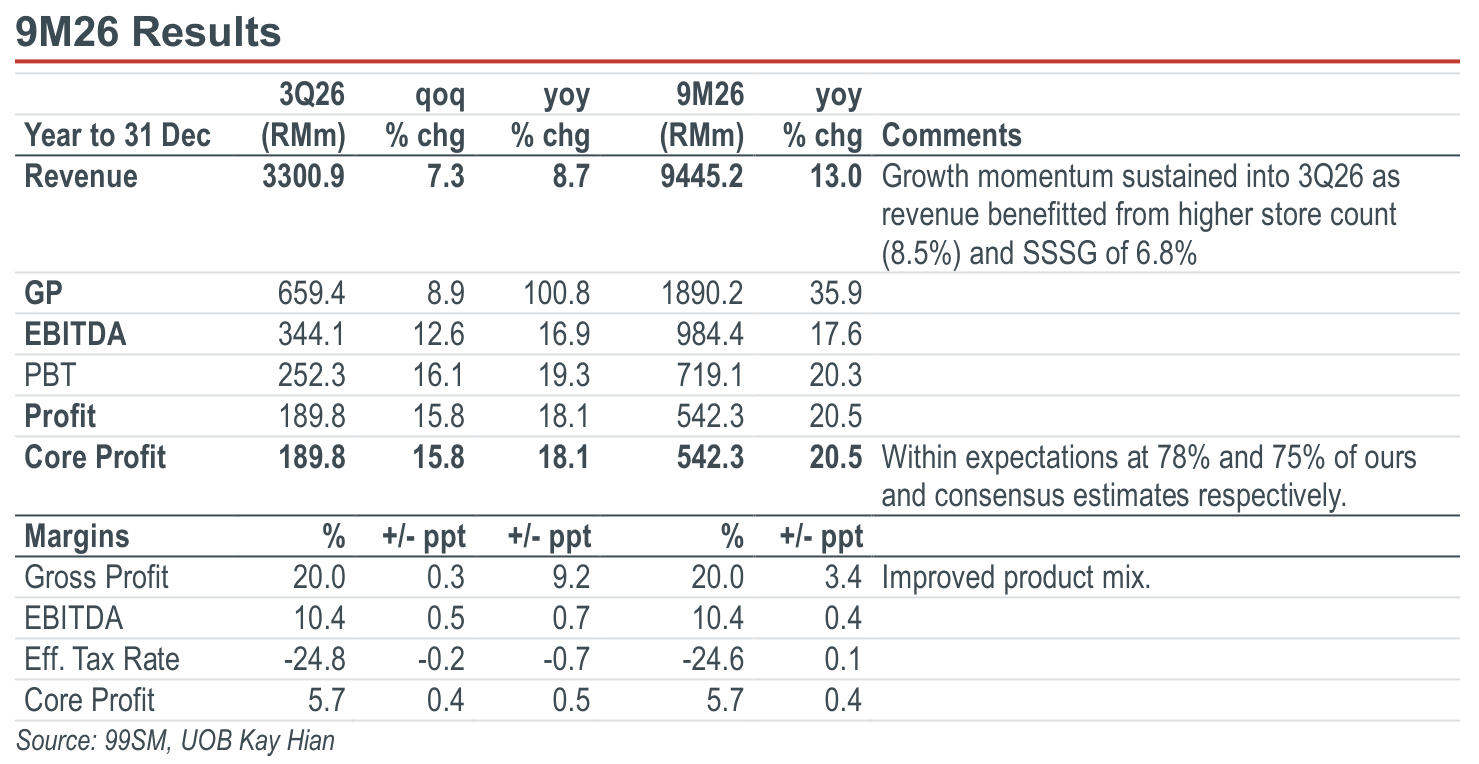
- Results fell within expectations. SSSG decelerated in 3Q26 as the stronger base from 2H25’s MySARA implementation kicked in.
- Margins were up slightly qoq, led by improved product mix and better cost optimisations.
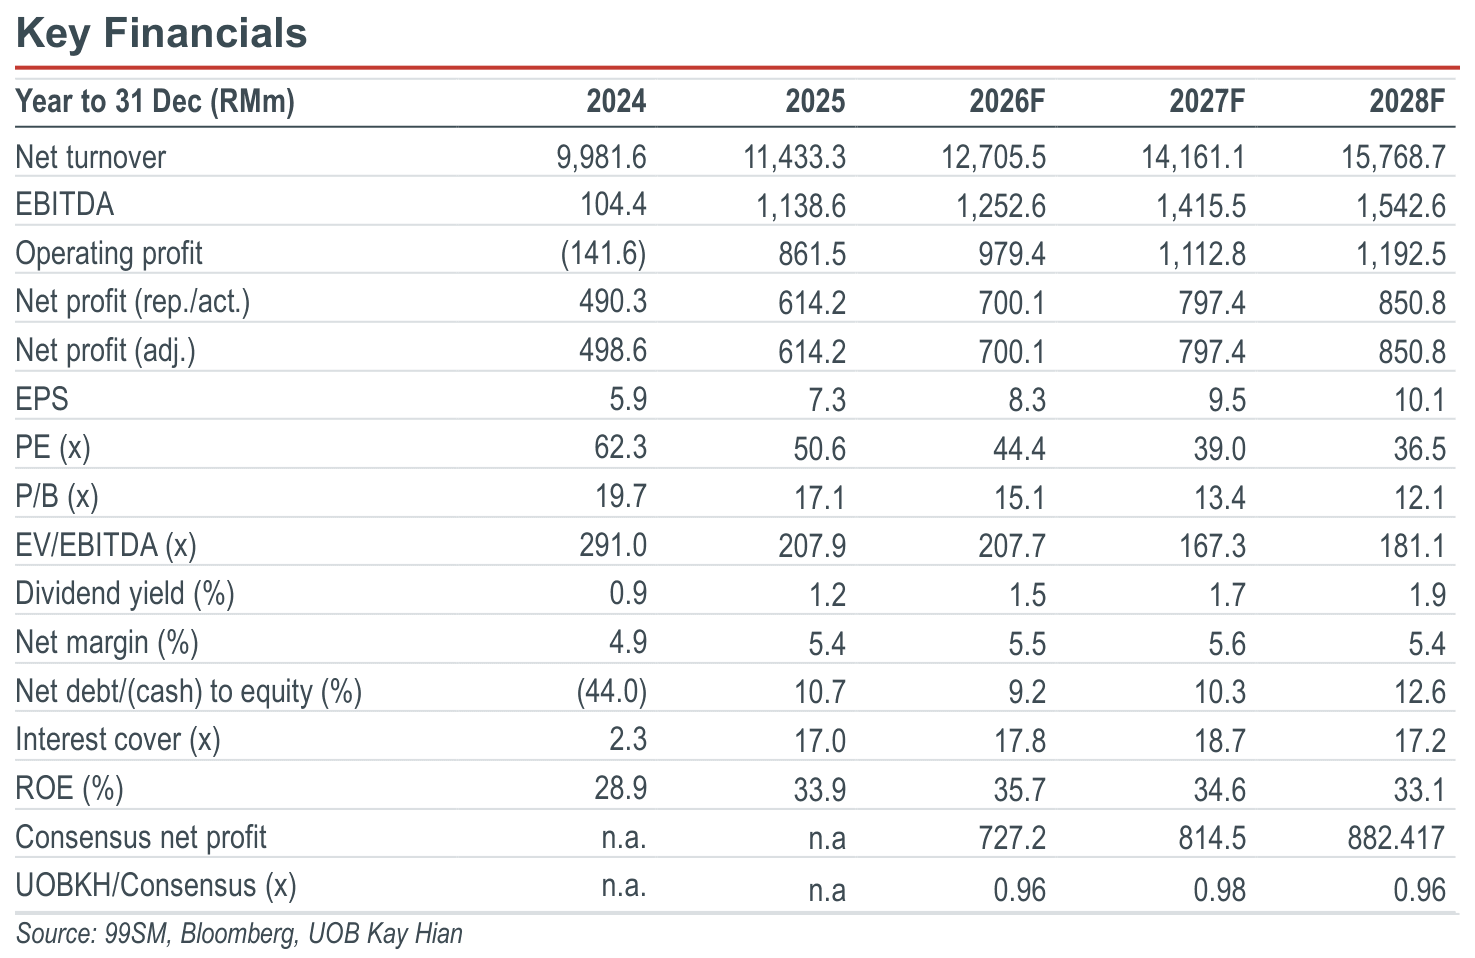
- Maintain BUY with an unchanged target price of RM4.00. 99SM is also set to benefit from measures announced in Budget 2027.
Analysis
- Within expectations. 99 Speed Mart Retail Holdings (99SM) posted a 9M26 core profit of RM542.3m (+20.5% yoy). This met expectations, representing 78% and 75% of our and consensus full-year forecasts respectively. A dividend of 2.25 sen was announced, bringing the total for 9M26 to 4.5 sen (9M25: 4.5 sen). Overall, SSSG remained robust, underpinned by Sumbangan Asas Rahmah (SARA) subsidy spending, and extended operating hours amid stable margins.
Highlights
- Results fell within expectations. SSSG decelerated in 3Q26 as the stronger base from 2H25’s MySARA implementation kicked in.
- Margins were up slightly qoq, led by improved product mix and better cost optimisations.
- Maintain BUY with an unchanged target price of RM4.00. 99SM is also set to benefit from measures announced in Budget 2027.
Analysis
- Within expectations. 99 Speed Mart Retail Holdings (99SM) posted a 9M26 core profit of RM542.3m (+20.5% yoy). This met expectations, representing 78% and 75% of our and consensus full-year forecasts respectively. A dividend of 2.25 sen was announced, bringing the total for 9M26 to 4.5 sen (9M25: 4.5 sen). Overall, SSSG remained robust, underpinned by Sumbangan Asas Rahmah (SARA) subsidy spending, and extended operating hours amid stable margins.
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.96
RM4.00
35.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Sept 2026
Eco-Shop Marketing (ECOSHOP MK): Prospects Intact; Macro Perspective Mixed

18 Nov 2026
Mr D.I.Y. Group (M) (MRDIY MK): 9M26: Below Expectations As SSSG Slumps

12 Nov 2026
Heineken Malaysia (HEIM MK): 3Q26: Soft As Expected, Potentially Turning The Corner
Our latest research

18 Nov 2026
Dialog Group (DLG MK): 1QFY27: Upstream Volumes Still Down; Looking Forward To 2Q
18 Nov 2026
Mr D.I.Y. Group (M) (MRDIY MK): 9M26: Below Expectations As SSSG Slumps

18 Nov 2026