Company Coverage
Mr D.I.Y. Group (M) (MRDIY MK): 9M26: Below Expectations As SSSG Slumps
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.04
RM1.50
58.7%
RM1.65
Analyst
Highlights
- 9M26 earnings missed expectations. While revenue came in higher yoy, rising costs and unfavourable forex movements saw net margins contract 1ppt yoy.
- SSSG remained negative for another quarter while basket size also declined.
- Mr DIY has also trimmed its new store target to 130 stores for 2026 and 200 stores by 2028, shifting focus to refurbishing its older locations.
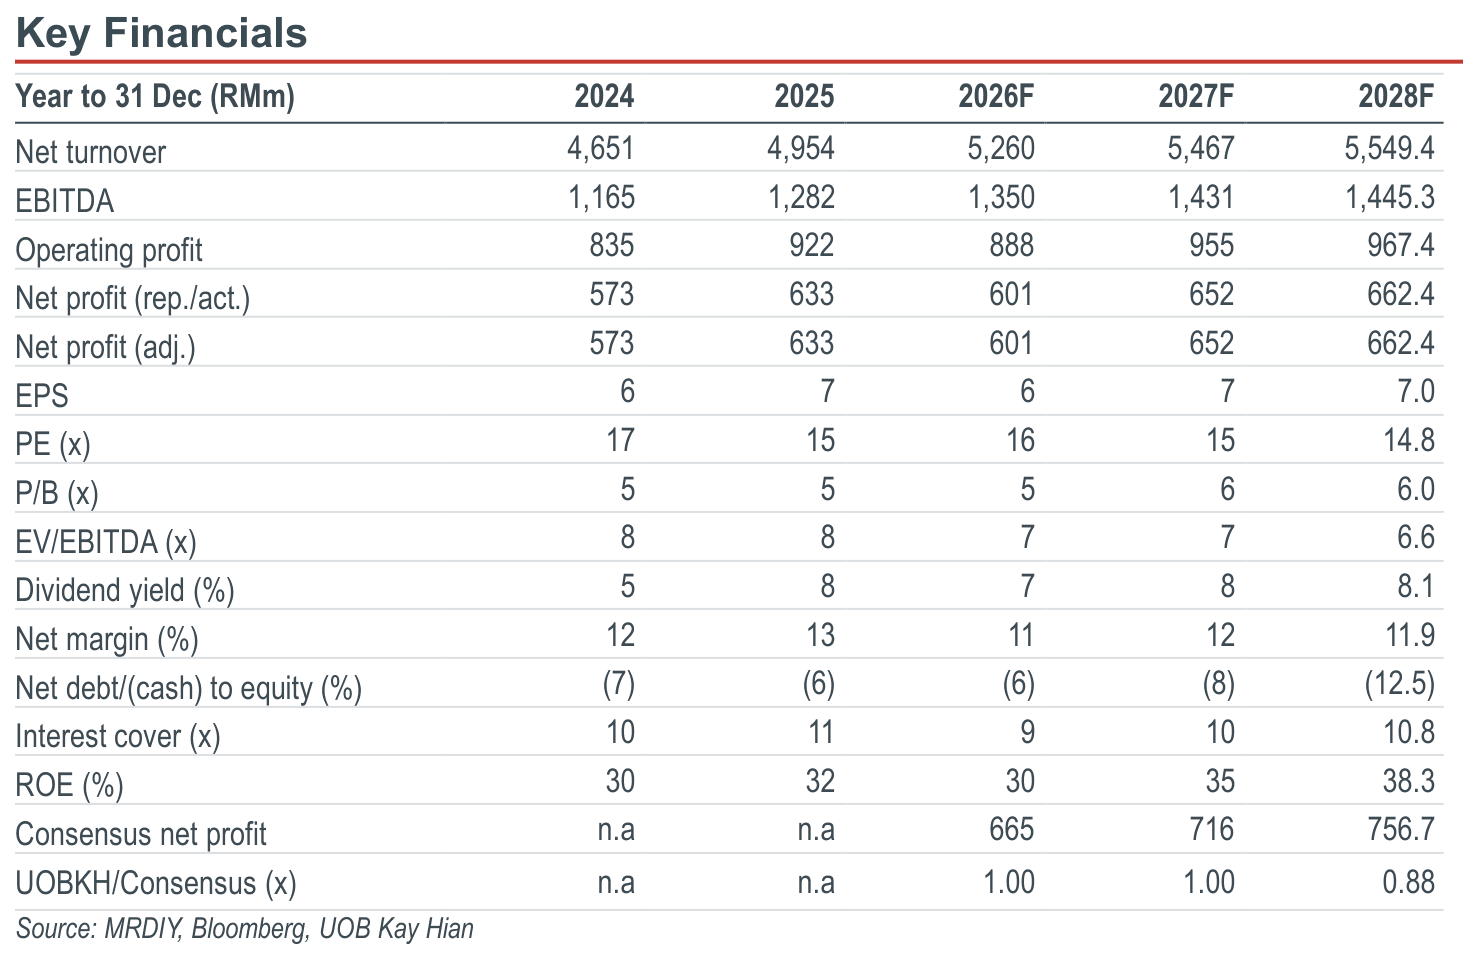
- Maintain BUY with a lower target price of RM1.50 (from RM1.65) as we trim our 2026-28 forecasts by 9-11%.
Analysis
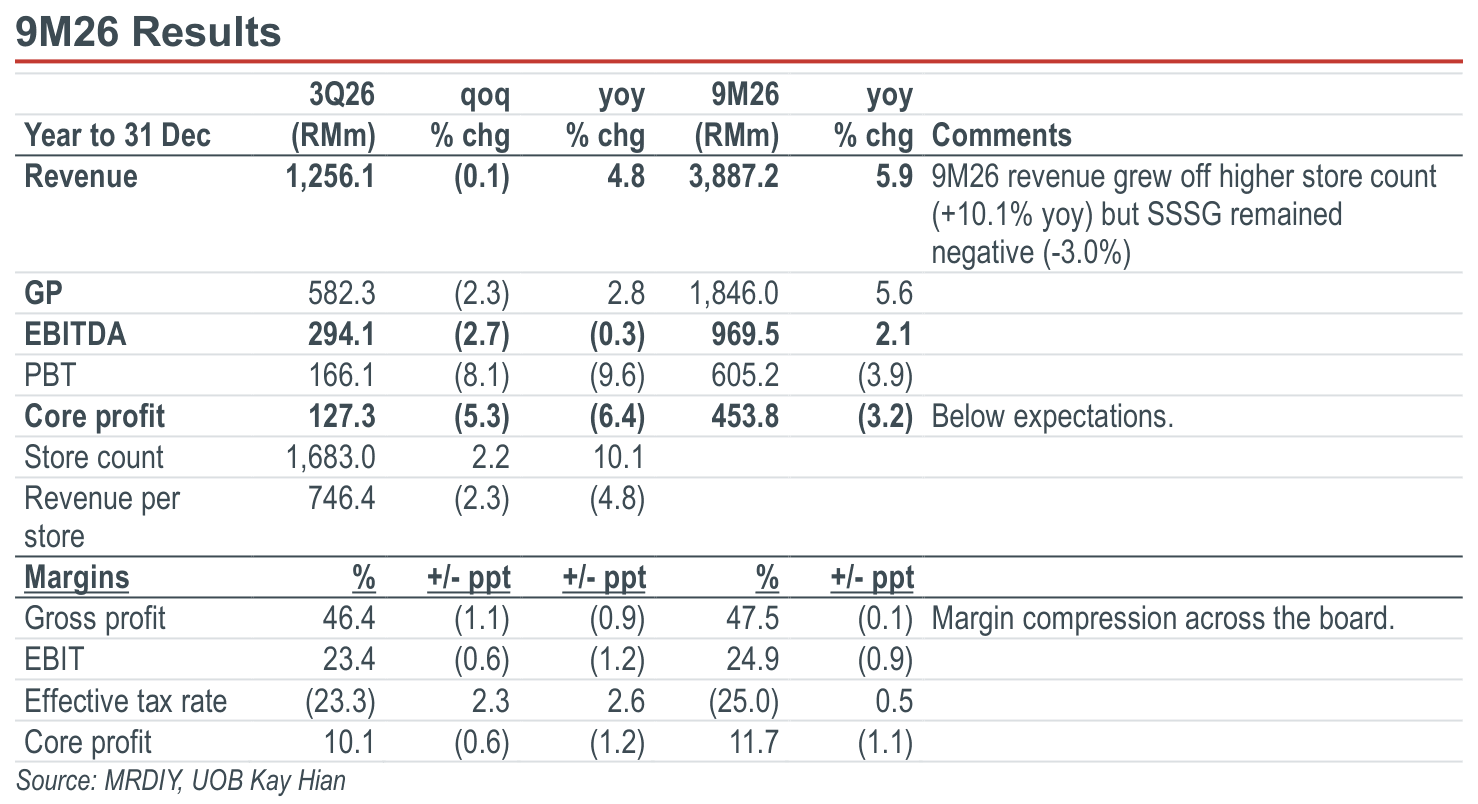
- Below expectations. Mr D.I.Y. Group (M) (Mr DIY) posted a 9M26 core net profit of RM453.8m (-3.2% yoy). This missed expectations, accounting for only 68% of both our and consensus full-year forecasts. The negative deviation was largely attributable to higher-than-expected operating costs. An interim DPS of 1.3 sen was declared, bringing 9M26 DPS to 6.2 sen (9M25: 4.2 sen).
Highlights
- 9M26 earnings missed expectations. While revenue came in higher yoy, rising costs and unfavourable forex movements saw net margins contract 1ppt yoy.
- SSSG remained negative for another quarter while basket size also declined.
- Mr DIY has also trimmed its new store target to 130 stores for 2026 and 200 stores by 2028, shifting focus to refurbishing its older locations.
- Maintain BUY with a lower target price of RM1.50 (from RM1.65) as we trim our 2026-28 forecasts by 9-11%.
Analysis
- Below expectations. Mr D.I.Y. Group (M) (Mr DIY) posted a 9M26 core net profit of RM453.8m (-3.2% yoy). This missed expectations, accounting for only 68% of both our and consensus full-year forecasts. The negative deviation was largely attributable to higher-than-expected operating costs. An interim DPS of 1.3 sen was declared, bringing 9M26 DPS to 6.2 sen (9M25: 4.2 sen).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.04
RM1.50
58.7%
RM1.65
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

18 Nov 2026
99 Speed Mart Retail Holdings (99SMART MK): 9M26: Within Expectations; SSSG Remains Robust

30 Oct 2026
KIP REIT (KIP MK): Reaping More From Existing Assets

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine
Our latest research
18 Nov 2026
99 Speed Mart Retail Holdings (99SMART MK): 9M26: Within Expectations; SSSG Remains Robust

18 Nov 2026
Dialog Group (DLG MK): 1QFY27: Upstream Volumes Still Down; Looking Forward To 2Q

18 Nov 2026