Company Coverage
CIMB Group (CIMB MK): Resilient Outlook Despite Bond Headwinds
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM7.15
RM8.80
23.1%
RM9.30
Analyst
Highlights
- ROE targets for 2026 remain intact despite recent headwinds.
- Fair Value on Comprehensive Income (FVOCI) and Fair Value to Profit & Loss (FVTPL) impact on higher bond yields on CET1 and trading income remains manageable due to hedging offsets and strong client franchise fees.
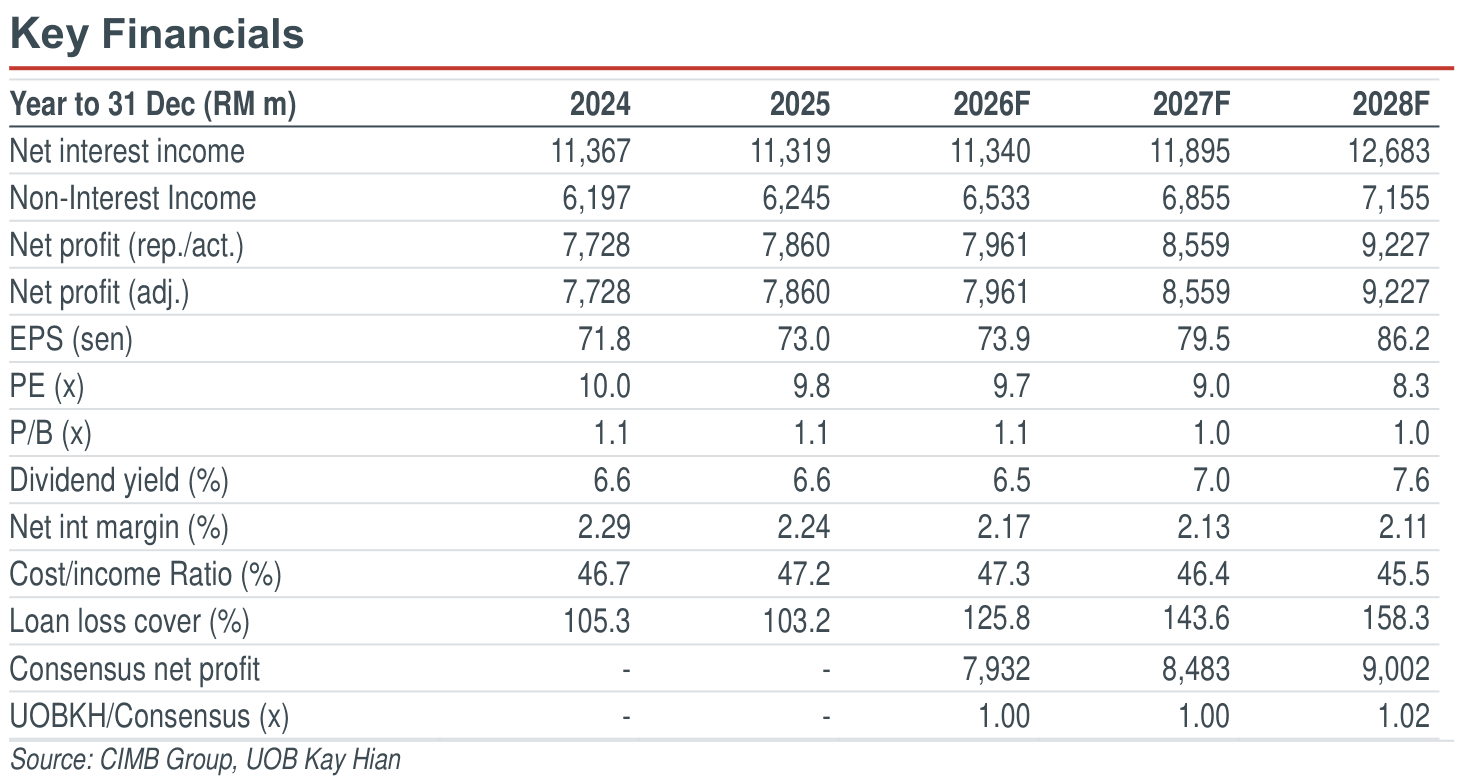
- Maintain BUY with a lower target price of RM8.80 (1.25x 2027F P/B, 11.5% ROE) from RM9.30 after earnings adjustment on lower NIM. The stock offers a lush dividend yield of 6.7%/7.0% for 2026/27.
Analysis
- Minimal impact on capital from rising bond yields. Management indicated that the impact of rising bond yields in 3Q26 on the group’s CET1 capital ratio through its FVOCI portfolio remains manageable, supported by effective hedging strategies.
- Trading income remains resilient despite bond headwinds. Similarly, trading income in 3Q26 has also remained relatively resilient compared with 2Q26, although we expect some sequential normalisation given the higher base in 2Q26, which included RM100m in a one-off non-interest income item. Excluding this contribution, underlying non-interest income appears stable to modestly stronger in 3Q26. To recap, 2Q26 non-interest income posted a 4% qoq growth, coming off an already robust 1Q26 non-interest income base. Management indicated that the group had been able to capitalise on widening credit and interest rate spreads to hedge effectively against rising bond yields. In addition, client-franchise-driven non-interest income, particularly from treasury sales and wealth management, continues to exhibit strong growth momentum helping to cushion negative impact from rising bond yields.
Highlights
- ROE targets for 2026 remain intact despite recent headwinds.
- Fair Value on Comprehensive Income (FVOCI) and Fair Value to Profit & Loss (FVTPL) impact on higher bond yields on CET1 and trading income remains manageable due to hedging offsets and strong client franchise fees.
- Maintain BUY with a lower target price of RM8.80 (1.25x 2027F P/B, 11.5% ROE) from RM9.30 after earnings adjustment on lower NIM. The stock offers a lush dividend yield of 6.7%/7.0% for 2026/27.
Analysis
- Minimal impact on capital from rising bond yields. Management indicated that the impact of rising bond yields in 3Q26 on the group’s CET1 capital ratio through its FVOCI portfolio remains manageable, supported by effective hedging strategies.
- Trading income remains resilient despite bond headwinds. Similarly, trading income in 3Q26 has also remained relatively resilient compared with 2Q26, although we expect some sequential normalisation given the higher base in 2Q26, which included RM100m in a one-off non-interest income item. Excluding this contribution, underlying non-interest income appears stable to modestly stronger in 3Q26. To recap, 2Q26 non-interest income posted a 4% qoq growth, coming off an already robust 1Q26 non-interest income base. Management indicated that the group had been able to capitalise on widening credit and interest rate spreads to hedge effectively against rising bond yields. In addition, client-franchise-driven non-interest income, particularly from treasury sales and wealth management, continues to exhibit strong growth momentum helping to cushion negative impact from rising bond yields.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM7.15
RM8.80
23.1%
RM9.30
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

1 Sept 2026
CIMB Group (CIMB MK): 2Q26: Resilient Showing Despite Forex And NIM Headwinds

17 Sept 2026
Fraser & Neave Holdings (FNH MK): Weathering The Perfect Storm

9 Sept 2026
KPJ Healthcare (KPJ MK): Strategic Roadmap Intact Despite Leadership Transition
Our latest research

19 Oct 2026
Yinson Holdings (YNS MK): 1HFY27 ER Results Addendum: Adjustments On Depreciation

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026