Company Coverage
Bursa Malaysia (BURSA MK): 3Q26: Muted Near-term Outlook
HOLD (Maintained)
Current price:
Target price:
Upside:
RM8.00
RM8.20
2.4%
Analyst
Highlights
- Bursa Malaysia reported 3Q26 net profit of RM70m (10% yoy, -2% qoq). Earnings were in line.
- Domestic politics and Middle East uncertainty continues to weigh on sentiment.
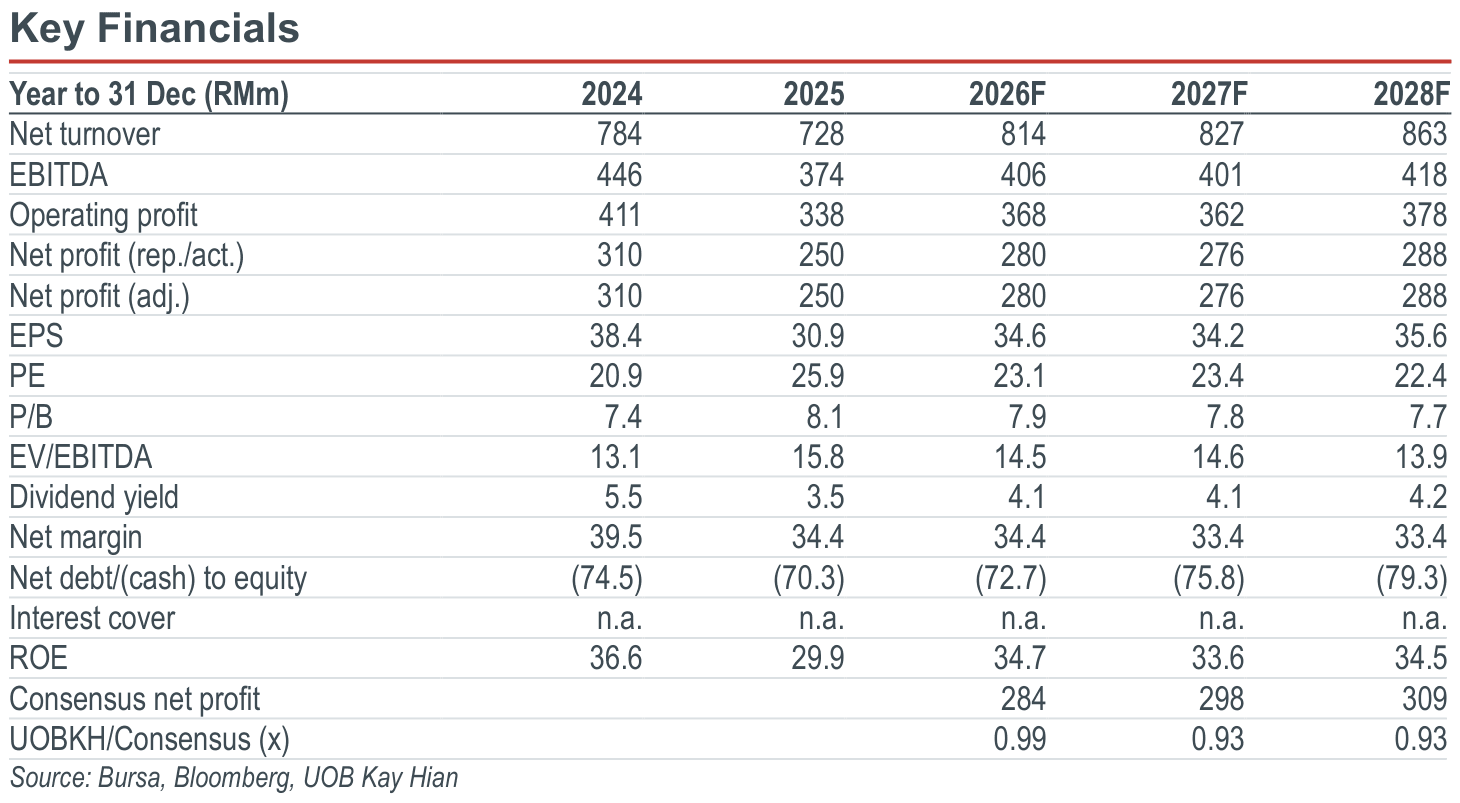
- Maintain HOLD and target price of RM8.20 (based on 24.0x FY27F P/E). The stock is currently trading close to its historical mean valuation, which we deem fair given the expected flattish earnings trajectory in 2027. Additionally, rising operating expenses amid a flattish ADV outlook are likely to constrain near-term earnings upside and cap share price outperformance.
Analysis
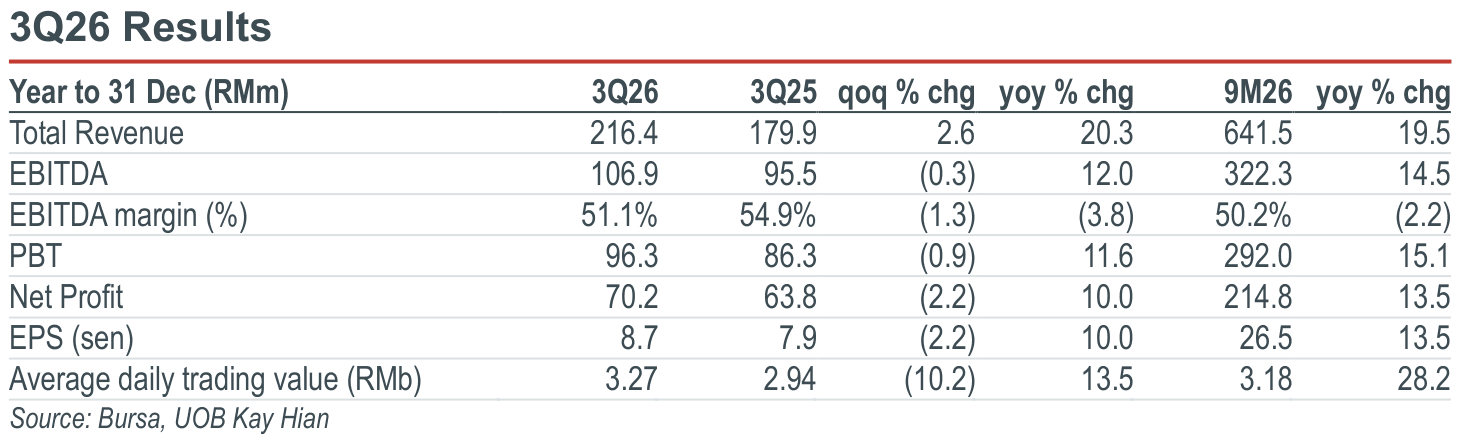
- In line. Bursa Malaysia reported 3Q26 net profit of RM70.2m (+10.0% yoy, -2.2% qoq), bringing 9M26 earnings to RM214.8m (+13.5% yoy), which came in broadly in line with expectations at 76% of our full-year forecast. 9M26 revenue grew 19.5% yoy, driven by a 28.2% yoy increase in securities trading revenue, in line with stronger average daily value traded (ADV), alongside a 64% yoy surge in listing revenue supported by larger IPOs. However, earnings growth was relatively more muted at 13.5% yoy due to higher operating expenses, arising from the new regulatory fees payable to the Securities Commission Malaysia, effective 1 Jan 26 (capped at RM35m p.a. for 2026) and a 19% yoy spike in staff cost.
- 3Q26 trend: Moderated qoq on lower ADV. 3Q26 earnings rose 10.0% yoy, driven primarily by a 21% increase in securities trading revenue, underpinned by a 14% yoy increase in average daily value traded (ADV). On a qoq basis, earnings dipped slightly (-2%) dragged down by a 10% qoq decline in ADV but partly offset by stronger derivative trading revenue (+24% qoq).
Highlights
- Bursa Malaysia reported 3Q26 net profit of RM70m (10% yoy, -2% qoq). Earnings were in line.
- Domestic politics and Middle East uncertainty continues to weigh on sentiment.
- Maintain HOLD and target price of RM8.20 (based on 24.0x FY27F P/E). The stock is currently trading close to its historical mean valuation, which we deem fair given the expected flattish earnings trajectory in 2027. Additionally, rising operating expenses amid a flattish ADV outlook are likely to constrain near-term earnings upside and cap share price outperformance.
Analysis
- In line. Bursa Malaysia reported 3Q26 net profit of RM70.2m (+10.0% yoy, -2.2% qoq), bringing 9M26 earnings to RM214.8m (+13.5% yoy), which came in broadly in line with expectations at 76% of our full-year forecast. 9M26 revenue grew 19.5% yoy, driven by a 28.2% yoy increase in securities trading revenue, in line with stronger average daily value traded (ADV), alongside a 64% yoy surge in listing revenue supported by larger IPOs. However, earnings growth was relatively more muted at 13.5% yoy due to higher operating expenses, arising from the new regulatory fees payable to the Securities Commission Malaysia, effective 1 Jan 26 (capped at RM35m p.a. for 2026) and a 19% yoy spike in staff cost.
- 3Q26 trend: Moderated qoq on lower ADV. 3Q26 earnings rose 10.0% yoy, driven primarily by a 21% increase in securities trading revenue, underpinned by a 14% yoy increase in average daily value traded (ADV). On a qoq basis, earnings dipped slightly (-2%) dragged down by a 10% qoq decline in ADV but partly offset by stronger derivative trading revenue (+24% qoq).
HOLD (Maintained)
Current price:
Target price:
Upside:
RM8.00
RM8.20
2.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


