Company Coverage
Hartalega (HART MK): 2QFY27: Mounting Cost Pressures Earnings Outlook
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.06
RM0.93
-12.3%
RM1.06
Analyst
Highlights
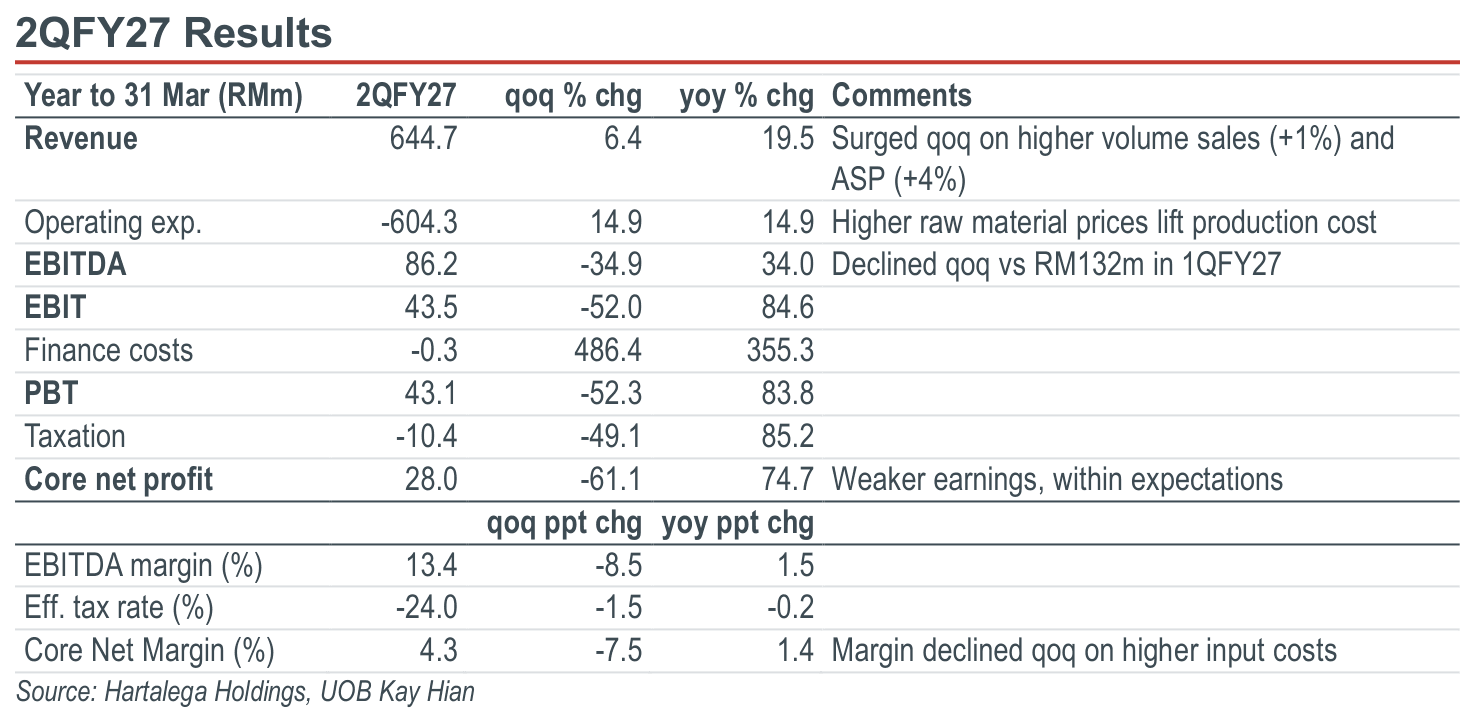
- 2QFY27 earnings declined significantly as higher volume sales (+1% qoq) and ASPs (+4% qoq) are largely offset by higher raw material costs.
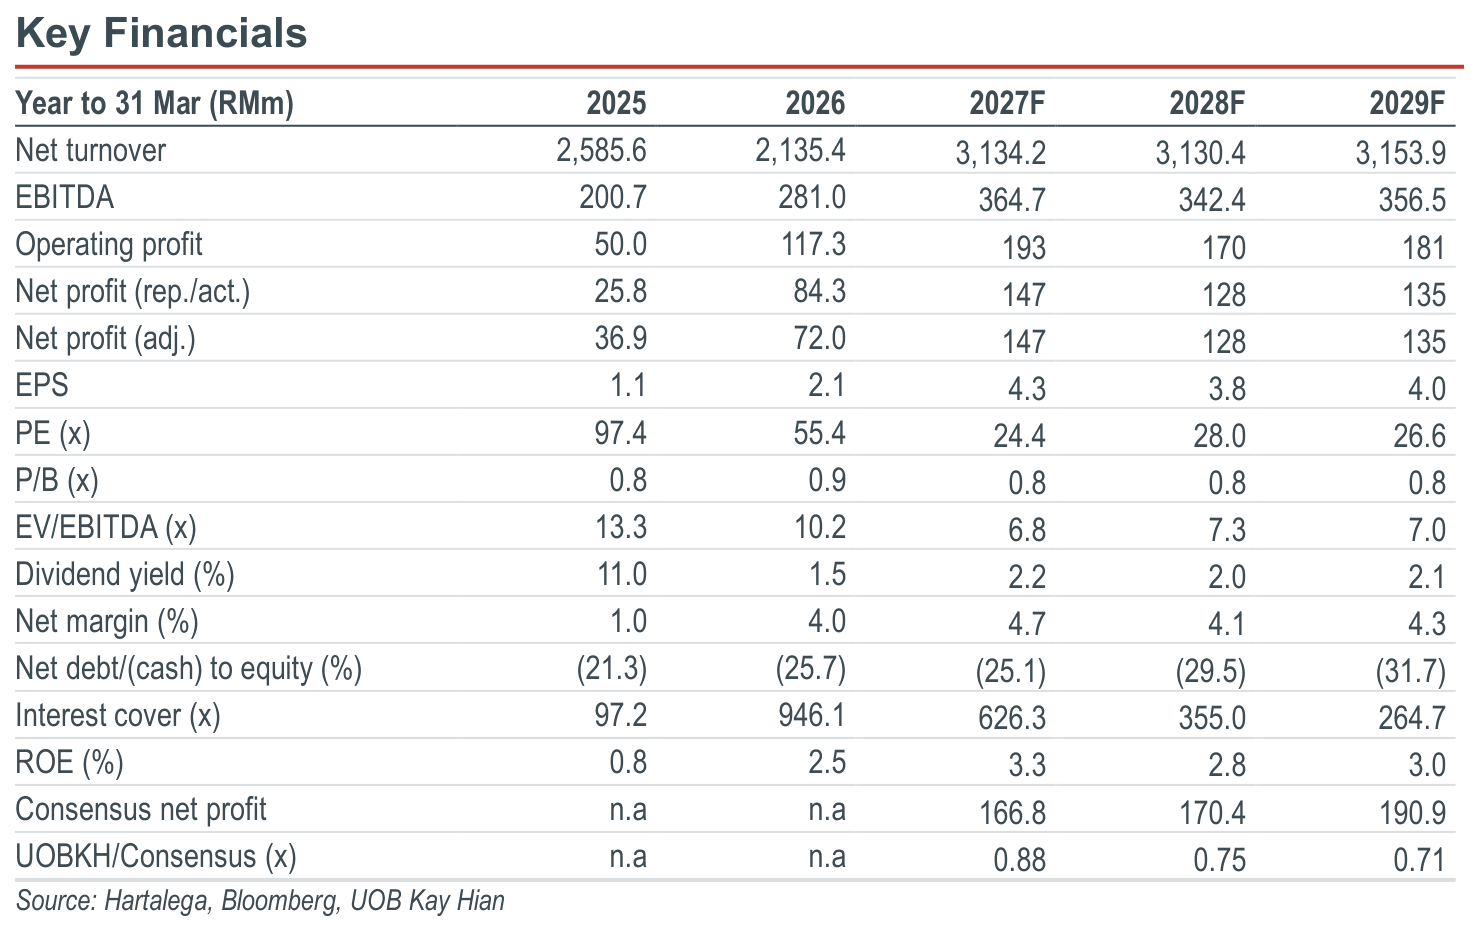
- Upcoming 2HFY27-FY28 results may see further margin compression as ASPs largely normalised, while minimum wage impacts and elevated raw material and energy costs will start to kick in.
- Structurally, competition from China and oversupply dynamics continue to impact earnings. Maintain HOLD with a lower target price of RM0.93.
Analysis
- Within expectations. Hartalega Holdings (Harta) registered a 2QFY27 core net profit of RM28m (1QFY27: RM72m), after stripping out exceptional items. 1HFY27 earnings accounted for 68% and 60% of our and consensus’ full-year estimates respectively, but are deemed within expectations as we foresee weaker earnings in 2HFY27.
Highlights
- 2QFY27 earnings declined significantly as higher volume sales (+1% qoq) and ASPs (+4% qoq) are largely offset by higher raw material costs.
- Upcoming 2HFY27-FY28 results may see further margin compression as ASPs largely normalised, while minimum wage impacts and elevated raw material and energy costs will start to kick in.
- Structurally, competition from China and oversupply dynamics continue to impact earnings. Maintain HOLD with a lower target price of RM0.93.
Analysis
- Within expectations. Hartalega Holdings (Harta) registered a 2QFY27 core net profit of RM28m (1QFY27: RM72m), after stripping out exceptional items. 1HFY27 earnings accounted for 68% and 60% of our and consensus’ full-year estimates respectively, but are deemed within expectations as we foresee weaker earnings in 2HFY27.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM1.06
RM0.93
-12.3%
RM1.06
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Oct 2026
Hartalega (HART MK): Tides Turning But Headwinds Persist

7 Oct 2026
Top Glove (TOPG MK) - 4QFY26: Accelerating Earnings Growth, But Challenges Persist

29 Oct 2026
Bursa Malaysia (BURSA MK): 3Q26: Muted Near-term Outlook
Our latest research

12 Nov 2026
Heineken Malaysia (HEIM MK): 3Q26: Soft As Expected, Potentially Turning The Corner

12 Nov 2026
SP Setia (SPSB MK): 3Q26: Results Miss; Slower Execution Timelines Drag Earnings

11 Nov 2026