Company Coverage
Top Glove (TOPG MK) - 4QFY26: Accelerating Earnings Growth, But Challenges Persist
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.875
RM0.85
-2.9%
RM0.75
Analyst
Highlights
- 4QFY26 earnings were lifted by margin expansion and much higher ASP due to the Middle East tensions. FY26 results are above expectations (149% and 156% of our and the Street’s forecasts).
- Despite stable demand and improving efficiency anticipated in FY27-28, intensifying China competition and higher production costs (from natural gas tariffs and minimum wage hike) remain a threat for mid-term earnings.
- Risk-reward appears neutral following yesterday’s share price action (+12%). Maintain HOLD with a higher target price of RM0.85 (from RM0.75).
Analysis
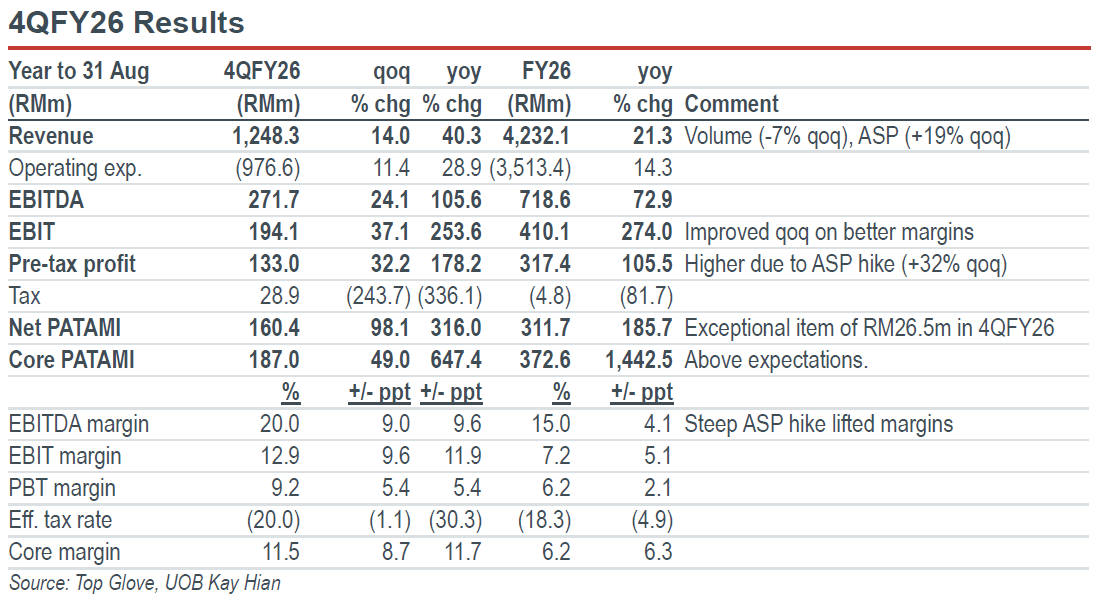
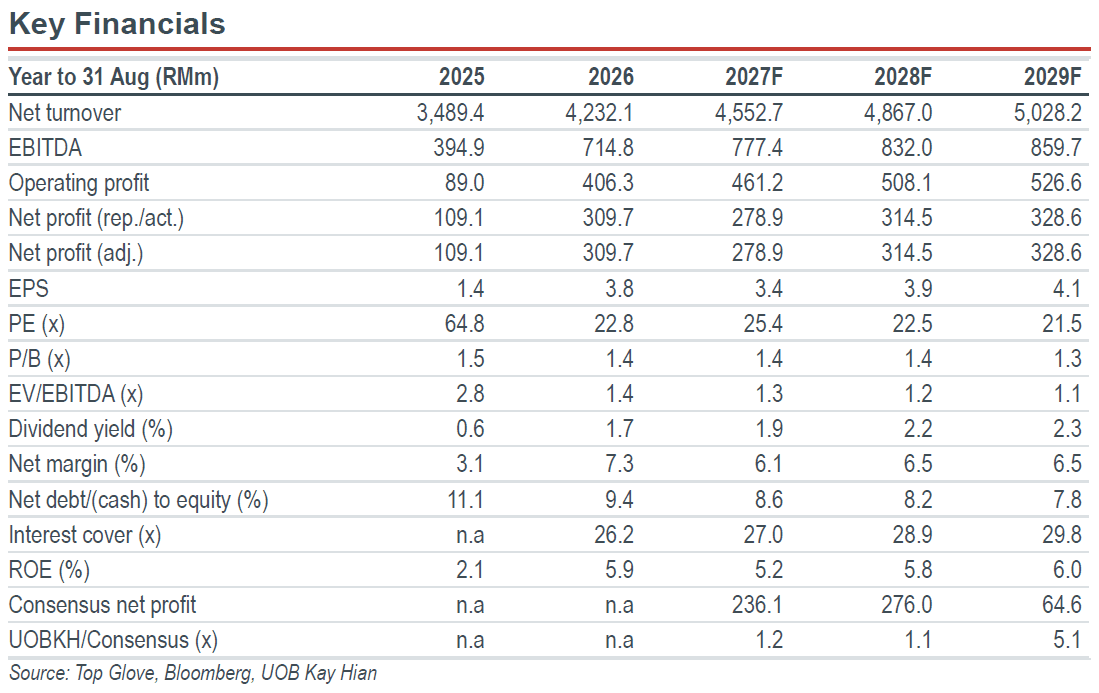
- Above expectations. Top Glove (TOPG) reported 4QFY26 core net profit of RM187m (+49% qoq) and higher revenue of RM889.6m (+7% qoq). For FY26, core net profit of RM373m was above our expectation, making up 149% and 156% of our and consensus full-year forecasts respectively. TOPG declared a 1.5 sen dividend for FY26 (FY25: 0.48 sen), which implies a modest 1.7% yield.
Highlights
- 4QFY26 earnings were lifted by margin expansion and much higher ASP due to the Middle East tensions. FY26 results are above expectations (149% and 156% of our and the Street’s forecasts).
- Despite stable demand and improving efficiency anticipated in FY27-28, intensifying China competition and higher production costs (from natural gas tariffs and minimum wage hike) remain a threat for mid-term earnings.
- Risk-reward appears neutral following yesterday’s share price action (+12%). Maintain HOLD with a higher target price of RM0.85 (from RM0.75).
Analysis
- Above expectations. Top Glove (TOPG) reported 4QFY26 core net profit of RM187m (+49% qoq) and higher revenue of RM889.6m (+7% qoq). For FY26, core net profit of RM373m was above our expectation, making up 149% and 156% of our and consensus full-year forecasts respectively. TOPG declared a 1.5 sen dividend for FY26 (FY25: 0.48 sen), which implies a modest 1.7% yield.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM0.875
RM0.85
-2.9%
RM0.75
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Aug 2026
Dialog Group (DLG MK): 4QFY26: Downstream’s Year; FY27 Sets The Stage For Upstream

21 Aug 2026
Genting Malaysia (GENM MK): 2Q26: RWNYC Gaining Momentum, Better 2H26 Ahead

9 Sept 2026
KPJ Healthcare (KPJ MK): Strategic Roadmap Intact Despite Leadership Transition
Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership

8 Oct 2026