Company Coverage
Sunway REIT (SREIT MK): 3Q26: In Line; Expect A Better 4Q26 On Seasonality
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM2.03
RM2.40
18.2%
RM2.80
Analyst
Highlights
Results are in line, with 9M26 core net profit reaching 74% of our full-year forecast.
Retail tenant sales psf growth moderated to 2% yoy in 9M26 (1H26: +4%), although footfall remained resilient. Nevertheless, management expects full-year tenant sales growth to remain in positive territory, while rental reversion in Sunway 163 Mall could improve after the completion of its AEI.
Maintain BUY with a lower target price of RM2.40 as we roll over our valuation base to 2027 and lift our cost of equity assumptions. While the timeline for sponsor asset acquisition appears slower than our expectation, any eventual acquisitions are likely to be DPU-accretive.
Analysis
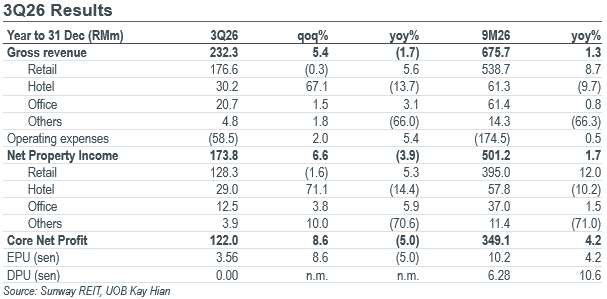
In line. Sunway REIT (SREIT) reported 3Q26 revenue of RM232m (+5% qoq, -2% yoy) and core net profit of RM122m (+9% qoq, -5% yoy). This brings 9M26 core net profit to RM349m (+4% yoy), accounting for 74% and 77% of our and consensus full-year forecasts respectively, in line with our expectations.
Gross gearing rose to 43.0% as of end-3Q26 (2Q26: 40.6%) following the early drawdown of financing to refinance debt due in Dec 26, as the company locked in competitive rates ahead of a potential OPR hike. Average cost of debt was at 3.62%.
Highlights
Results are in line, with 9M26 core net profit reaching 74% of our full-year forecast.
Retail tenant sales psf growth moderated to 2% yoy in 9M26 (1H26: +4%), although footfall remained resilient. Nevertheless, management expects full-year tenant sales growth to remain in positive territory, while rental reversion in Sunway 163 Mall could improve after the completion of its AEI.
Maintain BUY with a lower target price of RM2.40 as we roll over our valuation base to 2027 and lift our cost of equity assumptions. While the timeline for sponsor asset acquisition appears slower than our expectation, any eventual acquisitions are likely to be DPU-accretive.
Analysis
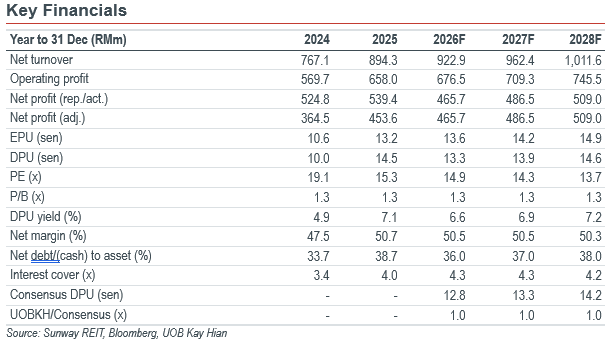
In line. Sunway REIT (SREIT) reported 3Q26 revenue of RM232m (+5% qoq, -2% yoy) and core net profit of RM122m (+9% qoq, -5% yoy). This brings 9M26 core net profit to RM349m (+4% yoy), accounting for 74% and 77% of our and consensus full-year forecasts respectively, in line with our expectations.
Gross gearing rose to 43.0% as of end-3Q26 (2Q26: 40.6%) following the early drawdown of financing to refinance debt due in Dec 26, as the company locked in competitive rates ahead of a potential OPR hike. Average cost of debt was at 3.62%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM2.03
RM2.40
18.2%
RM2.80
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

22 Oct 2026
CapitaLand Malaysia Trust (CLMT MK): 3Q26: Exceeds Expectations Due To Interest Cost Savings; Lush Dividend Yield Of 9-10%

30 Oct 2026
KIP REIT (KIP MK): Reaping More From Existing Assets

2 Nov 2026
IGB REIT (IGBREIT MK) - 3Q26: In Line; Southkey Remains The Growth Engine
Our latest research

10 Nov 2026
Maxis (MAXIS MK): 3Q26: Above Expectations; ARPU Uplift To Cushion Prepaid Subscriber Rationalisation

10 Nov 2026
Public Bank (PBK MK): 3Q26: Below Forecasts Due To NIM Pressure And Higher Credit Cost

10 Nov 2026