Company Coverage
Maxis (MAXIS MK): 3Q26: Above Expectations; ARPU Uplift To Cushion Prepaid Subscriber Rationalisation
BUY (Maintained)
Current price:
Target price:
Upside:
RM3.50
RM4.20
20.0%
Analyst
Highlights
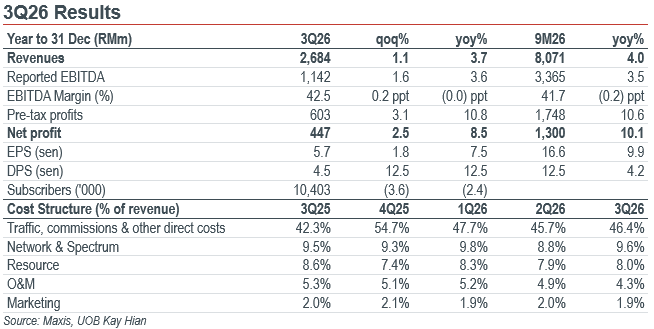
Maxis recorded strong 3Q26 results, with net profit reported at RM447m (+9% yoy; +3% qoq) on the back of cost discipline and higher service and enterprise revenue base. This brings 9M26 net profit to RM1,300m, which came in above expectations.
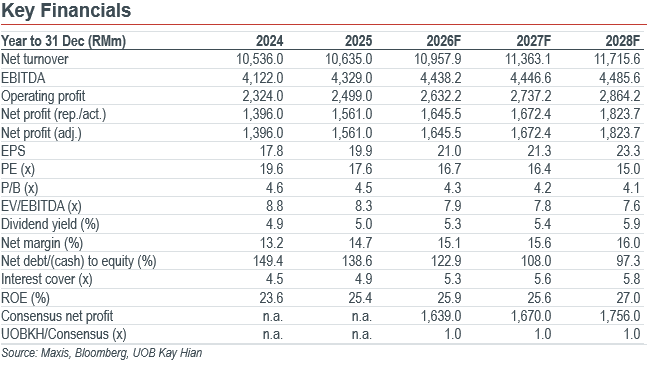
Maxis declared a higher third interim DPS of 4.5 sen/share. We raise 2026 earnings forecasts by 2% to reflect lower-than-expected earnings drag from DNB.
Maintain BUY with a DCF-based target price of RM4.20. The stock offers a 5.3% dividend yield.
Analysis
Strong 3Q26 results. Maxis’ 3Q26 net profit grew to RM447m (+9% yoy; +3% qoq), underpinned by robust cost discipline through operational digitalisation and network optimisation stronger service, coupled with healthy revenue growth driven by robust enterprise connectivity demand and resilient ARPUs. During the quarter, operations and maintenance saw a one-off true-up adjustment leading to a 17% yoy and 12% qoq reduction, respectively. 9M26 net profit came in at RM1,300m (+10% yoy) accounting for 79% and 81% of our and consensus full-year estimates respectively, which we deem to be above expectations.
Highlights
Maxis recorded strong 3Q26 results, with net profit reported at RM447m (+9% yoy; +3% qoq) on the back of cost discipline and higher service and enterprise revenue base. This brings 9M26 net profit to RM1,300m, which came in above expectations.
Maxis declared a higher third interim DPS of 4.5 sen/share. We raise 2026 earnings forecasts by 2% to reflect lower-than-expected earnings drag from DNB.
Maintain BUY with a DCF-based target price of RM4.20. The stock offers a 5.3% dividend yield.
Analysis
Strong 3Q26 results. Maxis’ 3Q26 net profit grew to RM447m (+9% yoy; +3% qoq), underpinned by robust cost discipline through operational digitalisation and network optimisation stronger service, coupled with healthy revenue growth driven by robust enterprise connectivity demand and resilient ARPUs. During the quarter, operations and maintenance saw a one-off true-up adjustment leading to a 17% yoy and 12% qoq reduction, respectively. 9M26 net profit came in at RM1,300m (+10% yoy) accounting for 79% and 81% of our and consensus full-year estimates respectively, which we deem to be above expectations.
BUY (Maintained)
Current price:
Target price:
Upside:
RM3.50
RM4.20
20.0%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Sept 2026
VS Industry (VSI MK): 4QFY26: Turning The Corner; Deep Value Beckons

10 Nov 2026
Public Bank (PBK MK): 3Q26: Below Forecasts Due To NIM Pressure And Higher Credit Cost

6 Nov 2026
SD Guthrie (SDG MK) - 3Q26: Within Expectations; Upstream Lifts Core Profit By 39%
Our latest research
10 Nov 2026
Public Bank (PBK MK): 3Q26: Below Forecasts Due To NIM Pressure And Higher Credit Cost

10 Nov 2026
Yinson Holdings (YNS MK): Privatisation: Third Time Is The Charm

10 Nov 2026