Company Coverage
Yinson Holdings (YNS MK): Privatisation: Third Time Is The Charm
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM2.26
RM2.50
+10.6%
RM2.40
Analyst
Highlights
Privatisation price of RM2.50 is fair and the best deal yet. We deem the valuation multiple on EV/EBITDA to be fair, as it is well within peer average and more importantly aligns with the implied multiple of the RCPS. MISC’s role is clearly not to take control of YNS as a subsidiary but as an associate, and it will be business as usual for both FPSO players. Having MISC as a platform will allow YNS to gradually reduce its blended financing costs over time. The timing of MISC’s entry and as a capital provider is impeccable, given that Yinson Production (YP) recently guided it can take on five projects at once, but in reality is in late stage negotiations for at least three new FPSOs - Tangkulo, Albacora and ZabaZaba.
Revising target price to match privatisation, as we assume third time is the charm. YNS has pursued privatisation for years, driven by the valuation gap between its public and private market valuations. The RCPS private investors valued YNS at US$3.7b, which is a sharp contrast to YNS’ market cap. The current deal may not be as lucrative as the previous attempts, but will allow YNS to have a quality, diversified funding platform ie founders’ capital, pension money and a strategic FPSO partner. Hence, we encourage investors to support this privatisation. Retain BUY with an adjusted target price RM2.50.
Analysis
Sweetened RM2.50/share cash buyout. The deal runs through a vehicle MY Offshore Holdings, in which MISC and the Lim family each hold 41.5% and Employees Provident Fund (EPF) retains 17.1%. This structure follows the details revealed during the preliminary exclusive negotiations with the consortium that started about two months ago. The price is 6.4% above the preliminary RM2.35/share offer floated on 28 Aug 26. Privatising Yinson Holdings (YNS) at RM2.50/share implies a firm value of RM7.3b (US$1.8b). The consortium plans to buy the remaining 1.6b shares for RM4.03b under a court-sanctioned scheme of arrangement. MISC’s portion amounts to RM3.03b.
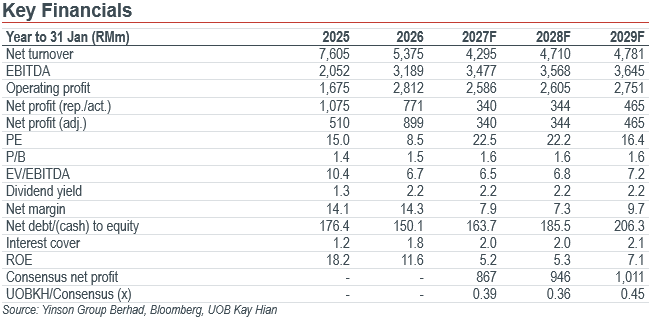
We deem the implied valuation to be fair... According to MISC’s announcement and with reference to YNS’ 1HFY27 financials, the deal implies 8.7x EV/EBITDA and 1.4x P/B. The enterprise value (EV) includes RM16b in group loans, RM3.3b in Redeemable Convertible Preference Shares (RCPS) and RM1.9b in perpetual securities. It is well within peer average EV/EBITDA multiples eg Bumi Armada (4x), BW Offshore (12x), and Modec (3x), and nearly a mirror image to SBM Offshore’s (7.8x EV/EBITDA; 1.5x P/B). We note that YNS’ historical EV/EBITDA trading range of 6-8x seems to be at a discount relative to other offshore peers that are valued closer to 10x. Using a PE comparison is not meaningful due to finance lease distortions.
Highlights
Privatisation price of RM2.50 is fair and the best deal yet. We deem the valuation multiple on EV/EBITDA to be fair, as it is well within peer average and more importantly aligns with the implied multiple of the RCPS. MISC’s role is clearly not to take control of YNS as a subsidiary but as an associate, and it will be business as usual for both FPSO players. Having MISC as a platform will allow YNS to gradually reduce its blended financing costs over time. The timing of MISC’s entry and as a capital provider is impeccable, given that Yinson Production (YP) recently guided it can take on five projects at once, but in reality is in late stage negotiations for at least three new FPSOs - Tangkulo, Albacora and ZabaZaba.
Revising target price to match privatisation, as we assume third time is the charm. YNS has pursued privatisation for years, driven by the valuation gap between its public and private market valuations. The RCPS private investors valued YNS at US$3.7b, which is a sharp contrast to YNS’ market cap. The current deal may not be as lucrative as the previous attempts, but will allow YNS to have a quality, diversified funding platform ie founders’ capital, pension money and a strategic FPSO partner. Hence, we encourage investors to support this privatisation. Retain BUY with an adjusted target price RM2.50.
Analysis
Sweetened RM2.50/share cash buyout. The deal runs through a vehicle MY Offshore Holdings, in which MISC and the Lim family each hold 41.5% and Employees Provident Fund (EPF) retains 17.1%. This structure follows the details revealed during the preliminary exclusive negotiations with the consortium that started about two months ago. The price is 6.4% above the preliminary RM2.35/share offer floated on 28 Aug 26. Privatising Yinson Holdings (YNS) at RM2.50/share implies a firm value of RM7.3b (US$1.8b). The consortium plans to buy the remaining 1.6b shares for RM4.03b under a court-sanctioned scheme of arrangement. MISC’s portion amounts to RM3.03b.
We deem the implied valuation to be fair... According to MISC’s announcement and with reference to YNS’ 1HFY27 financials, the deal implies 8.7x EV/EBITDA and 1.4x P/B. The enterprise value (EV) includes RM16b in group loans, RM3.3b in Redeemable Convertible Preference Shares (RCPS) and RM1.9b in perpetual securities. It is well within peer average EV/EBITDA multiples eg Bumi Armada (4x), BW Offshore (12x), and Modec (3x), and nearly a mirror image to SBM Offshore’s (7.8x EV/EBITDA; 1.5x P/B). We note that YNS’ historical EV/EBITDA trading range of 6-8x seems to be at a discount relative to other offshore peers that are valued closer to 10x. Using a PE comparison is not meaningful due to finance lease distortions.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
RM2.26
RM2.50
+10.6%
RM2.40
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

19 Oct 2026
Yinson Holdings (YNS MK): 1HFY27 ER Results Addendum: Adjustments On Depreciation

8 Oct 2026
Northern Solar (NORTHERN MK): Wins Another LSS5 EPCC Award; Underpins Earnings Visibility

30 Sept 2026
Yinson (YNS MK) - 1HFY27: Superior Execution To Support Deleveraging
Our latest research

10 Nov 2026
Maxis (MAXIS MK): 3Q26: Above Expectations; ARPU Uplift To Cushion Prepaid Subscriber Rationalisation

10 Nov 2026
Public Bank (PBK MK): 3Q26: Below Forecasts Due To NIM Pressure And Higher Credit Cost

10 Nov 2026