Company Coverage
Yinson (YNS MK) - 1HFY27: Superior Execution To Support Deleveraging
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.15
RM2.40
+11.6%
Analyst
Highlights
- 1HFY27 core profit is deemed in line, assuming the ER version is similar to its reported number. 1HFY27 results are cleaner, unlike FY26 whereby Yinson benefitted from large lumpy gains in FPSO Agogo’s early progress milestone. However, we observed narrowing losses from the non-FPSO divisions and accelerated loan repayments are the bigger picture for Yinson, as long as it maintains its superior execution.
- Maintain BUY with a target price of RM2.40, as we see a high likelihood of the company securing up to two new FPSOs in Indonesia and Brazil. This is corroborated by a second crude tanker purchase by Yinson in Aug 26. Management guided no additional funding is necessary.
Analysis
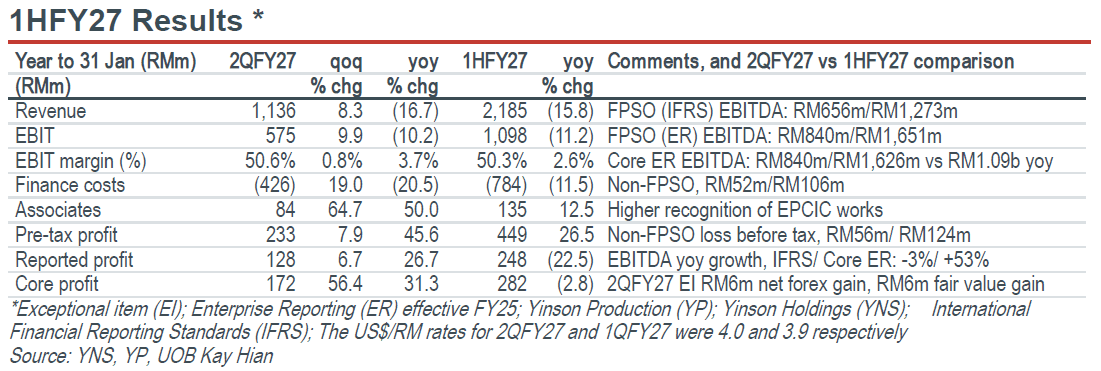
- 1HFY27 deemed in line, at potentially 43% of our/consensus forecasts. YP is expected to publish its 2QFY27 enterprise reporting (ER) results and investor presentation by 14 Oct 26, and hence we assume at this juncture that 2QFY27 core profit under the ER version almost matches the IFRS core profit of RM128m. As a recap in FY26, Yinson benefitted significantly from RM554m in early bonus/progress milestone payments for FPSO Agogo (1HFY27: RM25m). 2QFY27 finance costs contained some one-off charges of RM40m that relate to early loan repayments. We treated these as EI.
- Growth of adjusted ER EBITDA consistent with that of operating cash flow. Our addendum note to Yinson’s 1QFY27 results revealed YP’s ER quarterly profit base (before adjusting for EI) was below US$10m since end-FY26, as they now reflect higher financing/depreciation costs, and operating cost structure after adjusting for FPSO Agogo’s inventory costs and cost of tendering for projects. However, we believe assessment of Yinson’s 2QFY27 execution is more meaningful, if we account for lower non-O&G losses qoq and early loan repayments. Operating cash flow shows a remarkable turnaround of +741% yoy from a RM184m loss to RM1,179m (2QFY27: RM542m), enabling a continuous enhancement on its debt repayment profile.
Highlights
- 1HFY27 core profit is deemed in line, assuming the ER version is similar to its reported number. 1HFY27 results are cleaner, unlike FY26 whereby Yinson benefitted from large lumpy gains in FPSO Agogo’s early progress milestone. However, we observed narrowing losses from the non-FPSO divisions and accelerated loan repayments are the bigger picture for Yinson, as long as it maintains its superior execution.
- Maintain BUY with a target price of RM2.40, as we see a high likelihood of the company securing up to two new FPSOs in Indonesia and Brazil. This is corroborated by a second crude tanker purchase by Yinson in Aug 26. Management guided no additional funding is necessary.
Analysis
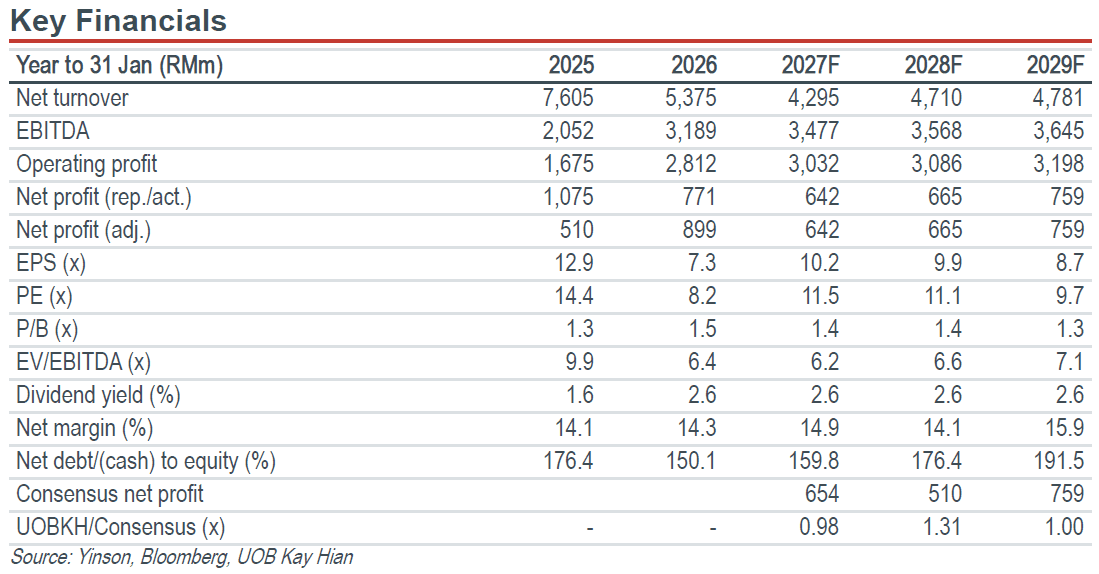
- 1HFY27 deemed in line, at potentially 43% of our/consensus forecasts. YP is expected to publish its 2QFY27 enterprise reporting (ER) results and investor presentation by 14 Oct 26, and hence we assume at this juncture that 2QFY27 core profit under the ER version almost matches the IFRS core profit of RM128m. As a recap in FY26, Yinson benefitted significantly from RM554m in early bonus/progress milestone payments for FPSO Agogo (1HFY27: RM25m). 2QFY27 finance costs contained some one-off charges of RM40m that relate to early loan repayments. We treated these as EI.
- Growth of adjusted ER EBITDA consistent with that of operating cash flow. Our addendum note to Yinson’s 1QFY27 results revealed YP’s ER quarterly profit base (before adjusting for EI) was below US$10m since end-FY26, as they now reflect higher financing/depreciation costs, and operating cost structure after adjusting for FPSO Agogo’s inventory costs and cost of tendering for projects. However, we believe assessment of Yinson’s 2QFY27 execution is more meaningful, if we account for lower non-O&G losses qoq and early loan repayments. Operating cash flow shows a remarkable turnaround of +741% yoy from a RM184m loss to RM1,179m (2QFY27: RM542m), enabling a continuous enhancement on its debt repayment profile.
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.15
RM2.40
+11.6%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


