Company Coverage
Yinson Holdings (YNS MK): 1HFY27 ER Results Addendum: Adjustments On Depreciation
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.13
RM2.40
+12.7%
Analyst
Highlights
- 1HFY27 profit on ER basis by its FPSO subsidiary. YP reveals new information, namely: a) an estimated US$10m one-off financing costs for the early repayment of Agogo junior loan of US$383m, b) US$3m one-off incentive bonus for FPSO AN, and c) FPSO MQ weakened slightly by pending charter payment by Petrobras.
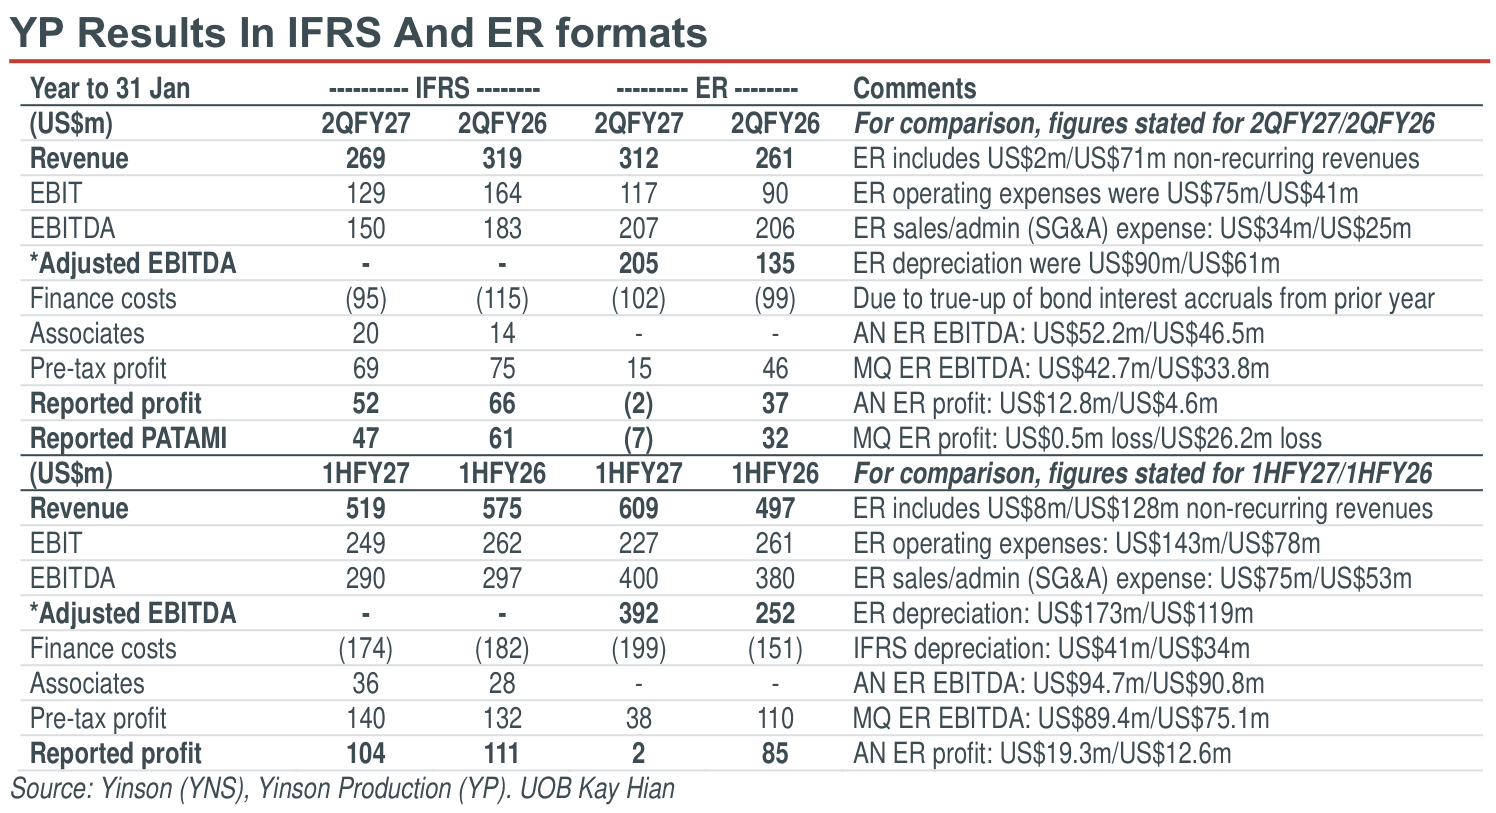
- Operations on track, with active debt repayment ongoing, as shown in the successful refinancing of FPSO Agogo into a US$1.5b project bond. The Agogo project bond carries a lower coupon of 6.5% vs the other two bonds for Brazil FPSOs (8.5-8.9%). Potentially, two more new FPSOs may be secured. While our EBITDA forecasts are aligned, the ER depreciation was nearly 3-4x of IFRS equivalent, hence we cut our profit forecasts by up to 49%. Depreciation adjustment does not impact our valuation.
- Retain BUY; target price: RM2.40.
Analysis
- 1HFY27 core profit recomputed on ER basis. The FPSO subsidiary Yinson Production (YP) released 2QFY27 accounts and investor presentation last week. Alongside new Enterprise Reporting (ER) disclosure, we found additional information namely: a) one-off financing costs for the early repayment of Agogo junior loan of US$383m, which we estimated to be US$10m; b) FPSO Anna Nery (AN) had a one-off incentive bonus for a planned performance was affected slightly by pending charter payment by Petrobras.
Highlights
- 1HFY27 profit on ER basis by its FPSO subsidiary. YP reveals new information, namely: a) an estimated US$10m one-off financing costs for the early repayment of Agogo junior loan of US$383m, b) US$3m one-off incentive bonus for FPSO AN, and c) FPSO MQ weakened slightly by pending charter payment by Petrobras.
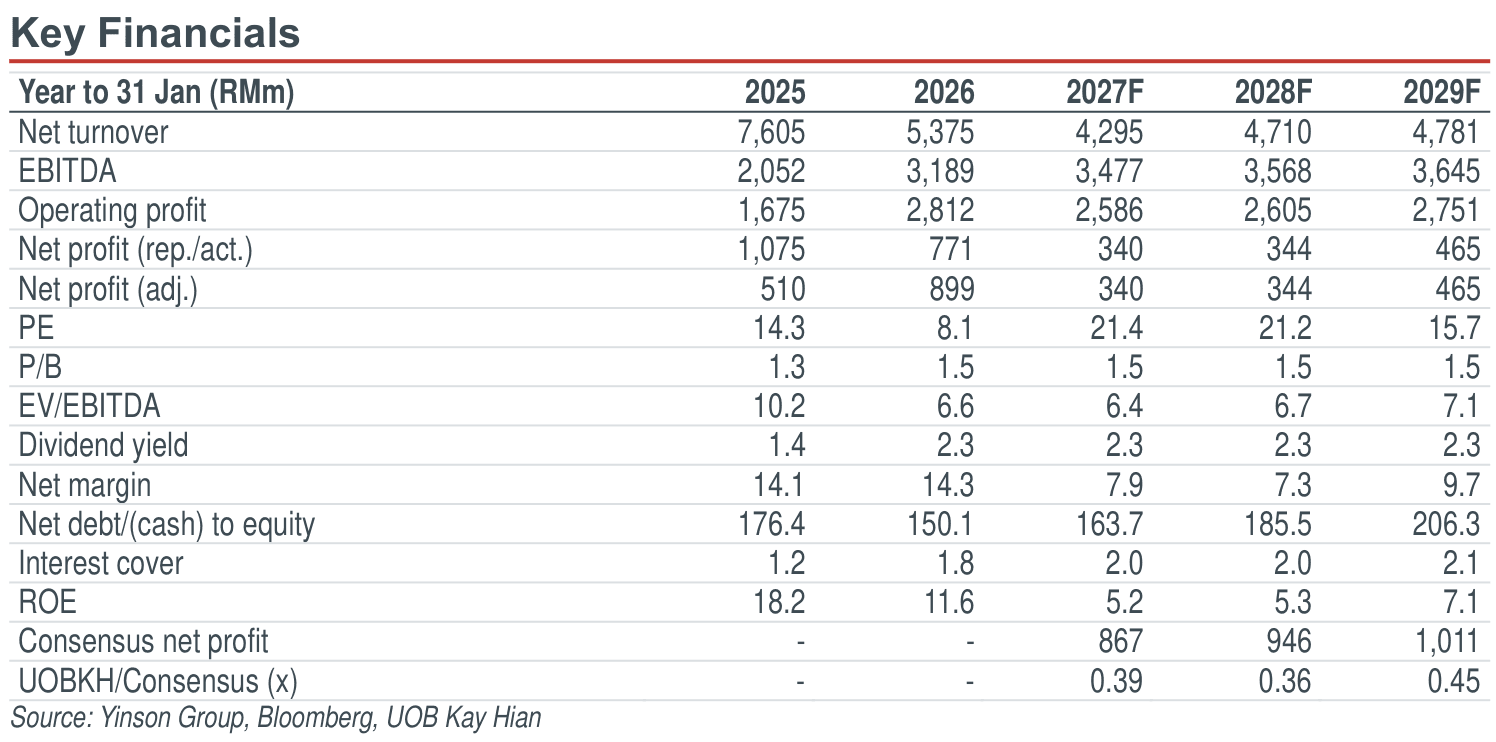
- Operations on track, with active debt repayment ongoing, as shown in the successful refinancing of FPSO Agogo into a US$1.5b project bond. The Agogo project bond carries a lower coupon of 6.5% vs the other two bonds for Brazil FPSOs (8.5-8.9%). Potentially, two more new FPSOs may be secured. While our EBITDA forecasts are aligned, the ER depreciation was nearly 3-4x of IFRS equivalent, hence we cut our profit forecasts by up to 49%. Depreciation adjustment does not impact our valuation.
- Retain BUY; target price: RM2.40.
Analysis
- 1HFY27 core profit recomputed on ER basis. The FPSO subsidiary Yinson Production (YP) released 2QFY27 accounts and investor presentation last week. Alongside new Enterprise Reporting (ER) disclosure, we found additional information namely: a) one-off financing costs for the early repayment of Agogo junior loan of US$383m, which we estimated to be US$10m; b) FPSO Anna Nery (AN) had a one-off incentive bonus for a planned performance was affected slightly by pending charter payment by Petrobras.
BUY (Maintained)
Current price:
Target price:
Upside:
RM2.13
RM2.40
+12.7%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Sept 2026
Yinson (YNS MK) - 1HFY27: Superior Execution To Support Deleveraging

1 Sept 2026
Axiata Group (AXIATA MK): 2Q26: In Line; Partial Monetisation Of Edotco Remains A Key Catalyst

28 Aug 2026
Tenaga Nasional (TNB MK): 2Q26: In Line; EBITDA Margin 29% On Higher Non-Fuel Opex
Our latest research

12 Oct 2026
HE Group (HEGROUP MK): A Diversified MEP Player; Scaling Up On DC And Semiconductor Demand

9 Oct 2026
Hume Cement Industries (HUME MK): Business Resilience Continues To Cement Its Margin Leadership

8 Oct 2026