Periodic/Sector reports
Mechanical, Electrical And Plumbing (MEP): The Electrification Gold Rush
Highlights
- The multi-year upcycle is driven by four structural themes: TNB grid investment, DC expansion, renewable energy integration and semiconductor investments. These underpin strong job visibility and growth prospects for M&E contractors and MEP players.
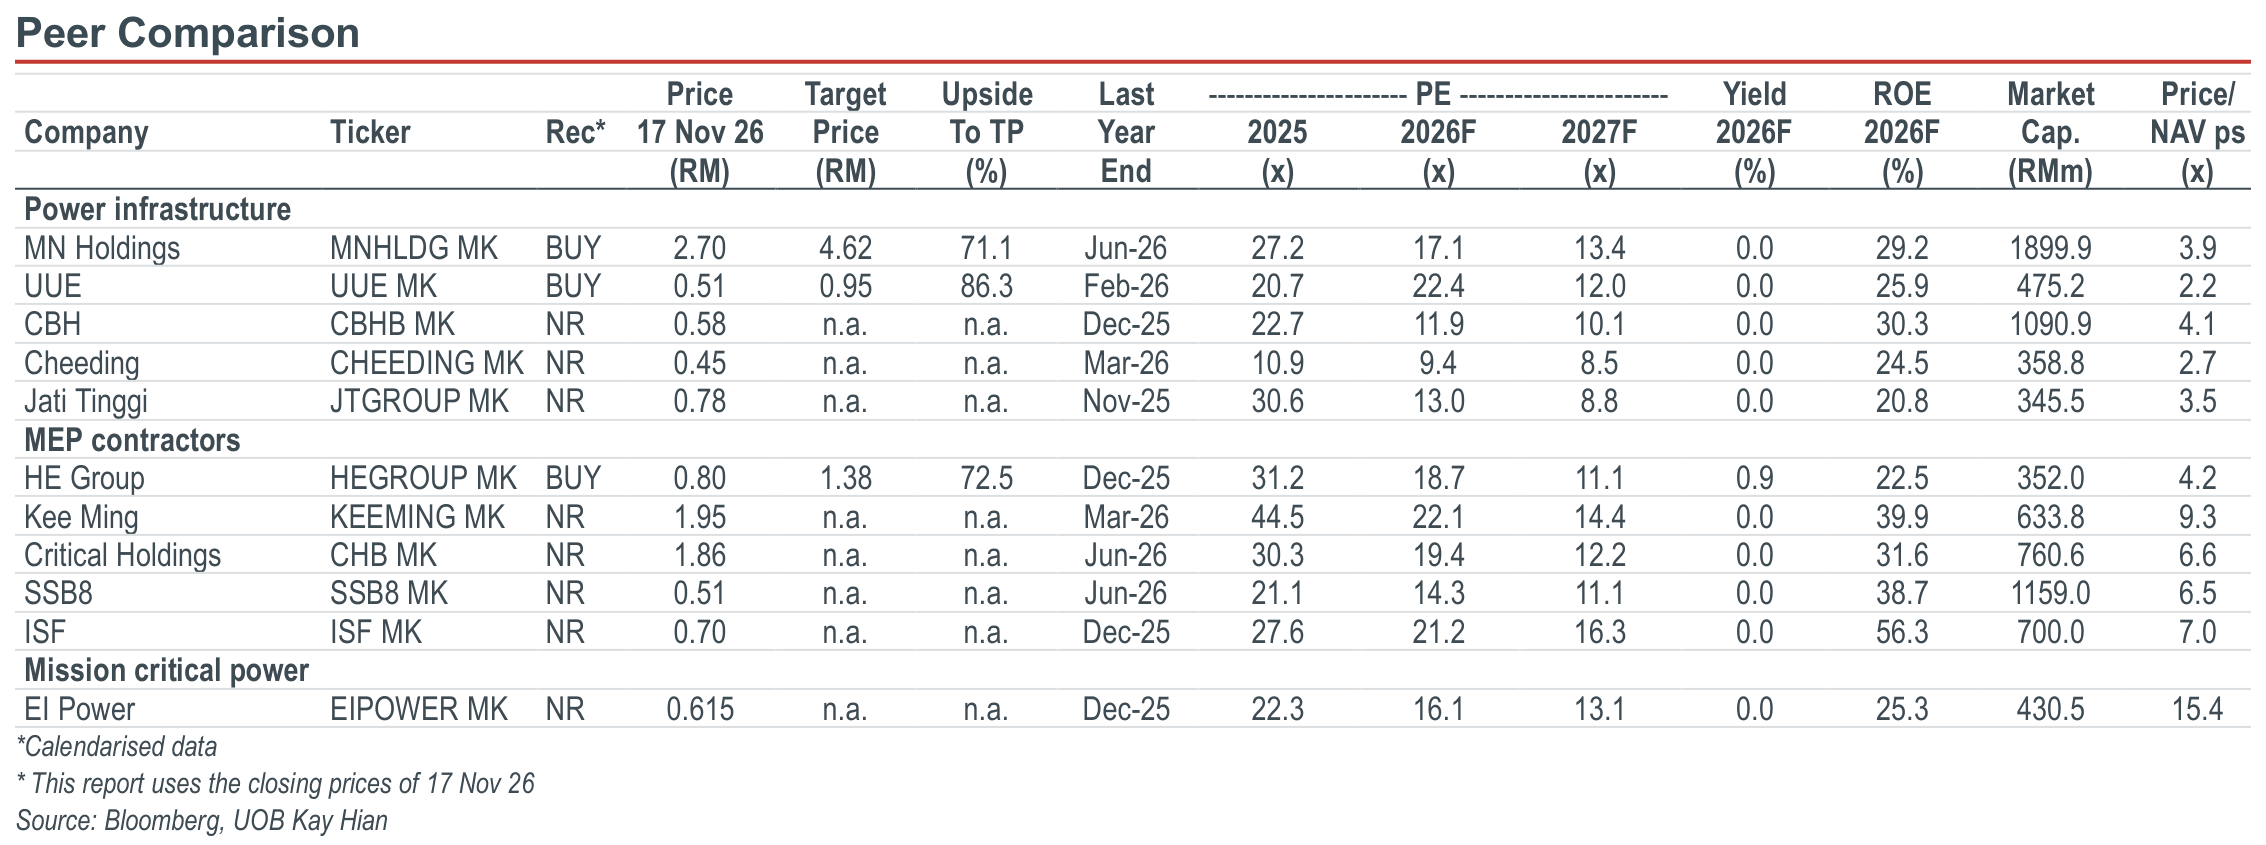
- Following the recent correction, sector valuations have eased from a peak of 23x to 15x 2027F PE. We view the pullback as an attractive accumulation opportunity, supported by our projected 30% sector core earnings CAGR over 2025-28. Stronger TNB contract flows, sustained hyperscaler investments and improving earnings delivery should reinforce investor confidence and provide catalysts for a further re-rating.
- Initiate coverage with OVERWEIGHT. We like MN Holdings (BUY/Target: RM4.62), HE Group (BUY/Target: RM1.38) and UUE Holdings (BUY/Target: RM0.95).
Analysis
- We project a robust three-year sector core earnings CAGR of 30% Growth will be driven by sustained contract replenishment and stronger billings across four demand drivers. Tenaga Nasional’s (TNB) RM42.8b Regulatory Period 4 (RP4) capex and potential RM47.2b under RP5 underpin grid-related awards. Beyond regulated spending, we estimate RM3.0b-3.8b of privately-funded data centre (DC) substation works and RM65.0b-80.0b of MEP fit-out opportunities in the next 3-5 years. Large scale solar 6 (LSS6) and the Corporate Renewable Energy Supply Scheme (CRESS) could generate another RM4b-5b of interconnection works, while semiconductor plant expansions and retrofits will broaden the addressable market.
- Three picks, three ways to play the upcycle. MN Holdings (MN) is a core, liquid grid proxy with DC and solar exposure, and backed by a RM1.9b orderbook and RM5b tenderbook. It offers 19.7% core earnings CAGR at 13x FY28F PE. HE Group (HE) is our high-growth alpha pick, with the highest earnings CAGR of 44.9%. It offers direct exposure to DC electrical fit-out and semiconductor recovery, but trades at just 11x PE. UUE Holdings (UUE) offers niche Malaysia–Singapore underground grid exposure and in-house HDPE manufacturing expansion, and has 31.5% earnings CAGR at 12x PE. Click here for Full Report dated 18 Nov 26
Highlights
- The multi-year upcycle is driven by four structural themes: TNB grid investment, DC expansion, renewable energy integration and semiconductor investments. These underpin strong job visibility and growth prospects for M&E contractors and MEP players.
- Following the recent correction, sector valuations have eased from a peak of 23x to 15x 2027F PE. We view the pullback as an attractive accumulation opportunity, supported by our projected 30% sector core earnings CAGR over 2025-28. Stronger TNB contract flows, sustained hyperscaler investments and improving earnings delivery should reinforce investor confidence and provide catalysts for a further re-rating.
- Initiate coverage with OVERWEIGHT. We like MN Holdings (BUY/Target: RM4.62), HE Group (BUY/Target: RM1.38) and UUE Holdings (BUY/Target: RM0.95).
Analysis
- We project a robust three-year sector core earnings CAGR of 30% Growth will be driven by sustained contract replenishment and stronger billings across four demand drivers. Tenaga Nasional’s (TNB) RM42.8b Regulatory Period 4 (RP4) capex and potential RM47.2b under RP5 underpin grid-related awards. Beyond regulated spending, we estimate RM3.0b-3.8b of privately-funded data centre (DC) substation works and RM65.0b-80.0b of MEP fit-out opportunities in the next 3-5 years. Large scale solar 6 (LSS6) and the Corporate Renewable Energy Supply Scheme (CRESS) could generate another RM4b-5b of interconnection works, while semiconductor plant expansions and retrofits will broaden the addressable market.
- Three picks, three ways to play the upcycle. MN Holdings (MN) is a core, liquid grid proxy with DC and solar exposure, and backed by a RM1.9b orderbook and RM5b tenderbook. It offers 19.7% core earnings CAGR at 13x FY28F PE. HE Group (HE) is our high-growth alpha pick, with the highest earnings CAGR of 44.9%. It offers direct exposure to DC electrical fit-out and semiconductor recovery, but trades at just 11x PE. UUE Holdings (UUE) offers niche Malaysia–Singapore underground grid exposure and in-house HDPE manufacturing expansion, and has 31.5% earnings CAGR at 12x PE. Click here for Full Report dated 18 Nov 26
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

20 Oct 2026
Automobile: 9M26 TIV Remains Resilient; Raising TIV Forecast To 810,000 Units

1 Oct 2026
Banking - Aug 26 BNM Statistics: Firmer Loan Growth; Improving Funding Mix

16 Nov 2026

