Periodic/Sector reports
Banking - Aug 26 BNM Statistics: Firmer Loan Growth; Improving Funding Mix
OVERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- Business lending continued to strengthen and CASA mix improved, but household demand and approvals softened, while asset quality edged weaker with coverage broadly stable.
- We expect sector earnings to grow by a decent 6% in 2027. Earnings resilience will be underpinned by modest loans growth, stable credit costs and relatively stable NIM with banks’ asset liability management helping to offset some of the headwinds from yield pressure.
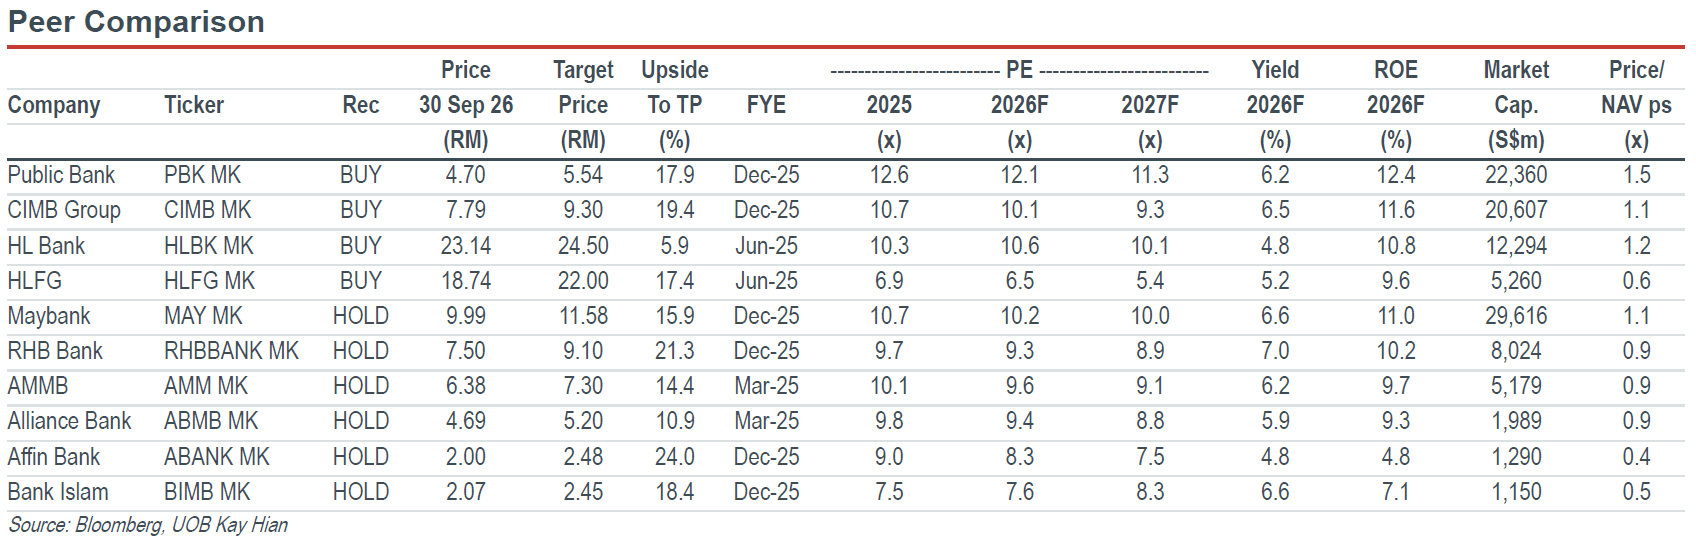
- Maintain OVERWEIGHT. Amid the ongoing Middle East geopolitical uncertainties, we adopt a barbell strategy, favouring Hong Leong Bank for its defensive profiles and capital management upside, while CIMB offers attractive value with one of the sector’s highest dividend yields at around 6.5%.
Analysis
- Business lending drives further acceleration. Loan growth strengthened to 5.7% yoy in Aug 26 (Jul 26: 5.6%), led by business loans rising to 6.8% (Jul 26: 6.4%), while household growth eased to 5.0% (Jul 26: 5.1%). Working-capital growth accelerated to 5.3% (Jul 26: 4.5%), offsetting softer SME growth of 3.8% (Jul 26: 4.5%), while mortgage, hire-purchase and credit-card growth all moderated.
- Business approvals remain the key pipeline support. Approved loan growth moderated to 10.9% yoy in Aug 26 (Jul 26: 25.1%) as household approvals contracted -10.7% (Jul 26: -2.8%). Business approvals remained strong at 31.2% (Jul 26: 53.2%), supported by working capital at 50.9%, while SME approvals improved to 7.7% (Jul 26: -3.2%). Mortgage and hire-purchase approvals weakened further, keeping the household pipeline subdued.
- CASA strengthens despite softer deposit growth. Total deposit growth moderated to 5.2% yoy in Aug 26 (Jul 26: 5.6%), trailing loan growth and lifting the loan-to-deposit ratio to 89.8% (Jul 26: 88.8%). Encouragingly, CASA growth accelerated to 7.9% (Jul 26: 7.1%) and CASA mix improved to 31.1% (Jul 26: 30.7%), partly offsetting continued contraction in fixed deposits and supporting the overall funding mix.
- Asset quality softens but remains contained. Total GIL rose slightly to 1.44% in Aug 26 (Jul 26: 1.43%), with household GIL increasing to 1.11% (Jul 26: 1.10%) and business GIL to 1.92% (Jul 26: 1.91%). SME GIL increased to 3.63% (Jul 26: 3.58%), while LLC was broadly stable at 81.4%, suggesting no material deterioration in coverage during the month.
Highlights
- Business lending continued to strengthen and CASA mix improved, but household demand and approvals softened, while asset quality edged weaker with coverage broadly stable.
- We expect sector earnings to grow by a decent 6% in 2027. Earnings resilience will be underpinned by modest loans growth, stable credit costs and relatively stable NIM with banks’ asset liability management helping to offset some of the headwinds from yield pressure.
- Maintain OVERWEIGHT. Amid the ongoing Middle East geopolitical uncertainties, we adopt a barbell strategy, favouring Hong Leong Bank for its defensive profiles and capital management upside, while CIMB offers attractive value with one of the sector’s highest dividend yields at around 6.5%.
Analysis
- Business lending drives further acceleration. Loan growth strengthened to 5.7% yoy in Aug 26 (Jul 26: 5.6%), led by business loans rising to 6.8% (Jul 26: 6.4%), while household growth eased to 5.0% (Jul 26: 5.1%). Working-capital growth accelerated to 5.3% (Jul 26: 4.5%), offsetting softer SME growth of 3.8% (Jul 26: 4.5%), while mortgage, hire-purchase and credit-card growth all moderated.
- Business approvals remain the key pipeline support. Approved loan growth moderated to 10.9% yoy in Aug 26 (Jul 26: 25.1%) as household approvals contracted -10.7% (Jul 26: -2.8%). Business approvals remained strong at 31.2% (Jul 26: 53.2%), supported by working capital at 50.9%, while SME approvals improved to 7.7% (Jul 26: -3.2%). Mortgage and hire-purchase approvals weakened further, keeping the household pipeline subdued.
- CASA strengthens despite softer deposit growth. Total deposit growth moderated to 5.2% yoy in Aug 26 (Jul 26: 5.6%), trailing loan growth and lifting the loan-to-deposit ratio to 89.8% (Jul 26: 88.8%). Encouragingly, CASA growth accelerated to 7.9% (Jul 26: 7.1%) and CASA mix improved to 31.1% (Jul 26: 30.7%), partly offsetting continued contraction in fixed deposits and supporting the overall funding mix.
- Asset quality softens but remains contained. Total GIL rose slightly to 1.44% in Aug 26 (Jul 26: 1.43%), with household GIL increasing to 1.11% (Jul 26: 1.10%) and business GIL to 1.92% (Jul 26: 1.91%). SME GIL increased to 3.63% (Jul 26: 3.58%), while LLC was broadly stable at 81.4%, suggesting no material deterioration in coverage during the month.
OVERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles


Our latest research

14 Oct 2026
Construction: Budget 2027 Neutral; Marginal Lift From Expansionary Stance

14 Oct 2026
Renewable Energy: 18 sen/kwh SAC For CRESS Acceleration Programme, 3GW Of CRESS In The Pipeline

13 Oct 2026