Periodic/Sector reports
Banking - Sep 26 BNM Statistics: Firmer Lending; Steady Asset Quality
OVERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- Loan growth accelerated on stronger business lending and approvals, while deposit growth held steady. Asset quality improved, although LLC eased further.
- We expect sector earnings to grow by a decent 6% in 2027. Earnings resilience will be underpinned by modest loans growth, stable credit costs and relatively stable NIM with banks’ asset liability management helping to offset some of the headwinds from yield pressure.
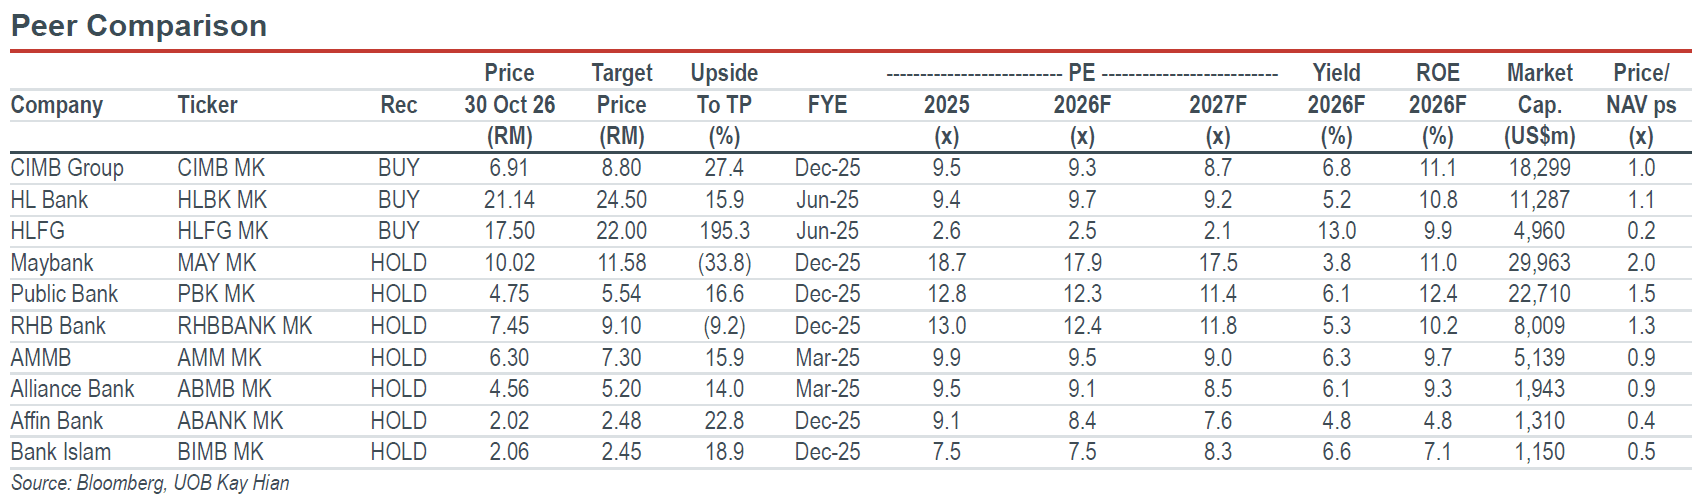
- Maintain OVERWEIGHT. Amid the ongoing Middle East geopolitical uncertainties, we adopt a barbell strategy, favouring Hong Leong Bank for its defensive profiles and capital management upside, while CIMB offers attractive value with one of the sector’s highest dividend yields at around 6.5%.
Analysis
- Loan growth accelerates on business momentum. Total loan growth strengthened to 6.1% yoy in Sep 26 (Aug 26: 5.7%), driven by business loans accelerating to 7.7% (Aug 26: 6.8%), while household growth was stable at 5.0%. Working-capital growth jumped to 7.4% (Aug 26: 5.3%), while mortgage and hire-purchase growth held near 5.3% and 5.2%; credit-card growth eased to 3.0%. SME growth also improved to 3.9% (Aug 26: 3.6%).
- Approvals signal a firmer pipeline. Approved loan growth surged to 31.1% yoy in Sep 26 (Aug 26: 13.6%), led by business approvals rising to 50.8% (Aug 26: 36.4%). Working-capital approvals remained robust at 55.3%, while SME approvals rebounded to 22.4% (Aug 26: -5.6%). Household approvals also recovered to 4.7% (Aug 26: -10.8%), supported by stronger hire-purchase and credit-card approvals, broadening pipeline support.
- Deposit growth holds steady as CASA momentum softens. Total deposit growth was stable at 5.2% yoy in Sep 26, trailing loan growth of 6.1%. CASA growth moderated to 5.1% (Aug 26: 7.9%) and CASA mix eased to 30.9% (Aug 26: 31.1%), although fixed-deposit growth turned positive at 0.3% (Aug 26: -1.4%). LDR remained broadly stable at 89.8%, signalling mildly tighter system funding conditions.
- Asset quality improves despite lower coverage. Total GIL declined to 1.42% in Sep 26 (Aug 26: 1.44%), while household GIL was broadly stable at 1.11% and business GIL improved to 1.87% (Aug 26: 1.92%). SME GIL also fell to 3.55% (Aug 26: 3.63%). However, LLC eased to 80.8% (Aug 26: 81.4%), indicating a modestly thinner coverage buffer despite contained impairment ratios overall.
Highlights
- Loan growth accelerated on stronger business lending and approvals, while deposit growth held steady. Asset quality improved, although LLC eased further.
- We expect sector earnings to grow by a decent 6% in 2027. Earnings resilience will be underpinned by modest loans growth, stable credit costs and relatively stable NIM with banks’ asset liability management helping to offset some of the headwinds from yield pressure.
- Maintain OVERWEIGHT. Amid the ongoing Middle East geopolitical uncertainties, we adopt a barbell strategy, favouring Hong Leong Bank for its defensive profiles and capital management upside, while CIMB offers attractive value with one of the sector’s highest dividend yields at around 6.5%.
Analysis
- Loan growth accelerates on business momentum. Total loan growth strengthened to 6.1% yoy in Sep 26 (Aug 26: 5.7%), driven by business loans accelerating to 7.7% (Aug 26: 6.8%), while household growth was stable at 5.0%. Working-capital growth jumped to 7.4% (Aug 26: 5.3%), while mortgage and hire-purchase growth held near 5.3% and 5.2%; credit-card growth eased to 3.0%. SME growth also improved to 3.9% (Aug 26: 3.6%).
- Approvals signal a firmer pipeline. Approved loan growth surged to 31.1% yoy in Sep 26 (Aug 26: 13.6%), led by business approvals rising to 50.8% (Aug 26: 36.4%). Working-capital approvals remained robust at 55.3%, while SME approvals rebounded to 22.4% (Aug 26: -5.6%). Household approvals also recovered to 4.7% (Aug 26: -10.8%), supported by stronger hire-purchase and credit-card approvals, broadening pipeline support.
- Deposit growth holds steady as CASA momentum softens. Total deposit growth was stable at 5.2% yoy in Sep 26, trailing loan growth of 6.1%. CASA growth moderated to 5.1% (Aug 26: 7.9%) and CASA mix eased to 30.9% (Aug 26: 31.1%), although fixed-deposit growth turned positive at 0.3% (Aug 26: -1.4%). LDR remained broadly stable at 89.8%, signalling mildly tighter system funding conditions.
- Asset quality improves despite lower coverage. Total GIL declined to 1.42% in Sep 26 (Aug 26: 1.44%), while household GIL was broadly stable at 1.11% and business GIL improved to 1.87% (Aug 26: 1.92%). SME GIL also fell to 3.55% (Aug 26: 3.63%). However, LLC eased to 80.8% (Aug 26: 81.4%), indicating a modestly thinner coverage buffer despite contained impairment ratios overall.
OVERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

1 Oct 2026
Banking - Aug 26 BNM Statistics: Firmer Loan Growth; Improving Funding Mix

14 Oct 2026
Construction: Budget 2027 Neutral; Marginal Lift From Expansionary Stance

23 Sept 2026
Banking: ESG: Assessing TNFD Readiness
Our latest research

30 Oct 2026
Oil & Gas: Offshore Support Vessel Market At A New Crossroads

20 Oct 2026
Automobile: 9M26 TIV Remains Resilient; Raising TIV Forecast To 810,000 Units

16 Oct 2026