Wealth Daily
Anthropic’s Debut Rally Leaves the Wider AI Sell-Off Intact
Today’s Must-Know News
Overnight Markets
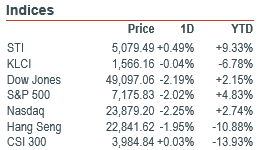
Market Movers: At the 19 November close, The S&P 500 lost 2.0% and the Nasdaq Composite 2.3%, with more than nine in ten S&P constituents declining. Anthropic (ANT US) closed at US$97.17, 17.1% above its US$83 offer price but below its US$111.50 opening trade. Of the 980m shares offered, 956.4m were new shares, providing the Claude developer with fresh capital for computing capacity. Advanced Micro Devices (AMD US) fell 7.7% after a short seller questioned its exposure to restricted Chinese customers. AMD disputed the report. Tencent (0700.HK) fell 6.5% to HK$348.40 in the first Hong Kong session after it reported RMB81.4bn of capital expenditure and negative free cash flow of RMB69.1bn. Its cloud revenue grew 35.0%, but that growth has yet to absorb the cash cost of expansion. (Anthropic / AP / Reuters / Tencent / HKEX) Tencent (0700.HK) is our Core Recommendation.
Macro: US initial jobless claims rose by 1,000 to 203,000. Continuing claims rose by 70,000 to 1.76m, suggesting workers already on benefits faced a harder time finding a new job than the modest increase in new claims implied. In the Philadelphia Fed survey, the manufacturing activity index fell to 6.3 from 20.9 and new orders slipped below zero. The prices-paid index rose to 58.2. For manufacturers, the combination puts the focus on whether pricing can protect margins as orders soften. (US Department of Labor / Philadelphia Fed)
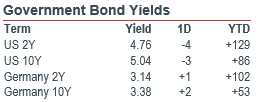
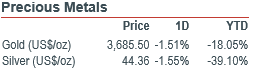
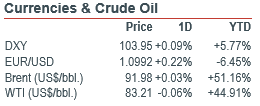
FICC: December gold settled 1.5% lower at US$3,685.50/oz and December silver lost 1.6% to US$44.36/oz. The US 10-year Treasury yield fell 3bps to 5.04%. January Brent settled at US$91.98/bbl and December WTI at US$83.21/bbl, both within US$0.05 of the previous settlement. At 05:26:52 SGT the US Dollar Index was live at 103.95, up 0.1% from its prior daily close and 5.8% since year-end. (AP / US Treasury / Reuters / Yahoo Finance)
AI
Anthropic record flotation gives investors a listed benchmark for frontier AI. Anthropic (ANT US) closed its first Nasdaq session at US$97.17, up 17.1% from the US$83 offer price. The 980m-share sale was worth US$81.34bn. Anthropic issued 956.4m shares to fund its business and selling holders supplied the balance. Investors who bought at the opening trade of US$111.50 finished the session with a loss despite the premium to the offer. (Company / Stock Titan)
China export concerns put AMD’s server business under scrutiny. Advanced Micro Devices (AMD US) fell 7.7% after Hunterbrook Capital disclosed a short position. Its research affiliate alleged that server makers tied to a restricted Chinese company used AMD firmware. Reuters could not independently verify the allegations. AMD said the report misrepresented its practices and that it complies with US export controls. Tighter distributor checks could lengthen delivery times even for permitted customers. (Reuters / The Fly)
Meta AI build-out puts its 2030 climate target under review. Meta Platforms (META US) is reviewing its 2030 value-chain net-zero target as it expands its AI infrastructure. Net greenhouse gas emissions rose 45% in 2025 to 11.8m metric tons of carbon dioxide equivalent. Meta contracted more than 10GW of clean energy capacity that year, yet equipment and construction emissions remain a drag on progress towards the target. (Company / Bloomberg) Meta Platforms (META US) is our Core Recommendation.
Palo Alto forecast draws buyers to cybersecurity as other AI stocks retreat. Palo Alto Networks (PANW US) rose 6.4% in its first regular session after announcing earnings and a US$4.5bn all-stock deal for Applied Compute. Fiscal 1Q revenue grew 39% YoY to US$3.44bn. Palo Alto expects FY27 revenue of US$14.52bn–14.57bn. The acquisition would let customers run open-weight models within their own security controls, extending Palo Alto’s reach into deployment. (Company / Reuters)
Americas
Walmart raises its outlook as online sales outpace its stores. Walmart (WMT US) raised FY27 adjusted EPS guidance to US$2.84–2.89 from US$2.80–2.87. Fiscal 3Q revenue rose 5.2% YoY to US$188.8bn and adjusted EPS of US$0.65 beat the US$0.64 consensus. Shares fell 1.0%. US e-commerce grew 23% and global advertising sales rose 25%, giving Walmart room to improve margins without raising shelf prices. (Company / AP) Walmart (WMT US) is our Core Recommendation.
Intuit agrees to sell Mailchimp as growth shifts to its small-business platform. At the US close, Intuit (INTU US) announced a US$3.68bn agreement with Bending Spoons. Intuit expects US$3.31bn in cash and US$368m in the buyer’s shares. Fiscal 1Q revenue rose 12% YoY to US$4.4bn, while Mailchimp revenue fell 1% to US$313m and online accounting revenue grew 19% to US$1.4bn. The sale would remove a slow-growing business. Intuit’s guidance still includes Mailchimp pending the expected closing in early 2027. (Company / Bending Spoons)
Williams-Sonoma unchanged outlook overshadows profit growth. Williams-Sonoma (WSM US) dropped 15.2% after revenue fell short of market expectations and the company reiterated its FY26 sales outlook. Fiscal 3Q comparable brand revenue rose 5.1%, and adjusted EPS grew 11.7% YoY to US$2.19. Higher oil prices added 50bps to supply-chain costs. Management retained its 4.7%–7.2% annual revenue-growth range. The sell-off leaves holiday demand and the ability to offset freight costs as the main tests of its operating margin. (Company / AP)
Ross Stores sustains customer traffic ahead of the holiday season. Ross Stores (ROST US) reported fiscal 3Q sales of US$6.3bn after the US close, up 12% YoY. Higher traffic helped lift comparable sales 8%, and operating margin widened 70bps to 12.3%. Management kept its 4Q comparable-sales growth outlook at 4%–5%. The prior-year gain of 9% makes further margin expansion a tougher proposition. (Company)
Greater China
Alibaba cloud margin expanded as recurring demand outpaced overall growth. Alibaba (9988.HK) grew September-quarter revenue 10% YoY to RMB271.5bn. Cloud and compute sales rose 53% to RMB61.0bn and the segment’s adjusted EBITA more than doubled to RMB8.84bn. Its AI labs and applications business, however, posted an adjusted EBITA loss of RMB10.5bn, up from RMB3.44bn. The contrast shows how much of the infrastructure profit is being reinvested in applications. (Alibaba / AP) Alibaba (9988.HK) is our Core Recommendation.
Tencent cash outflow put the cost of AI expansion in focus. Tencent (0700.HK) fell 6.5% to HK$348.40 in the first Hong Kong session after its 3Q results. Cloud revenue rose 35% YoY and marketing services revenue grew 19%, but the marketing gross margin fell to 52% from 57%. Capital expenditure reached RMB81.4bn and free cash flow was negative RMB69.1bn. Cash conversion now matters as much to the investment case as cloud demand. (Tencent / HKEX) Tencent (0700.HK) is our Core Recommendation.
Lenovo server earnings beat forecasts, but warrant revaluation pushed it to a statutory loss. Lenovo (0992.HK) fell 5.5% to HK$16.25. Fiscal 2Q revenue rose 48% YoY to US$30.2bn, above the US$27.6bn LSEG consensus. Infrastructure revenue grew 178% to US$11.3bn and segment operating profit exceeded US$1bn for the first time. A non-cash revaluation of warrants tied to the Alat partnership contributed to a US$640m statutory loss, even as adjusted net income rose 166% to US$1.36bn. (Lenovo / Reuters / HKEX)
NetEase improved gaming profitability as lower revenue-sharing costs cushioned softer sales. NetEase (9999.HK) reported 3Q revenue of RMB27.9bn, down 1.8% YoY. Revenue from games and related services fell 1.7% to RMB22.9bn, while group gross profit rose 4.8% to RMB19.0bn. Lower revenue-sharing costs and a 5.4% decline in operating expenses softened the earnings impact. Attributable net income was RMB8.4bn against RMB8.6bn a year earlier. (NetEase)
Kuaishou slipped to a loss as weaker merchant advertising squeezed margins. Kuaishou (1024.HK) posted a 3Q loss of RMB959m against a RMB4.5bn profit a year earlier. Revenue fell to RMB31.6bn from RMB35.6bn and gross margin narrowed to 48.2% from 54.7%. Online marketing sales fell 11.1% as merchants cut spending. Other services, including Kling AI, grew 1.5%, too slowly to offset weakness in advertising and livestreaming. (Kuaishou)
Asia ex. China
TSMC took a US$500m stake in Anthropic as Taiwanese chip shares fell. Taiwan’s TAIEX fell 4.4% to 38,426.89 and the semiconductor index lost 4.3%. Taiwan Semiconductor Manufacturing (TSM US) separately disclosed that its subsidiary bought 6.02m Anthropic shares at US$83 each. The US$500m investment took up the full sum authorised on 10 November. Its 0.03% stake gives the foundry direct financial exposure to the developer, with little voting influence. (TWSE / CNA / CNA filing report / TSMC) Taiwan Semiconductor Manufacturing (TSM US) is our Core Recommendation.
Seatrium expects a better project mix to lift FY26 underlying profit. Seatrium (5E2 SP) expects materially higher FY26 underlying net profit as project margins improve. Its S$12.2bn order book covers 35 projects with deliveries through 2033. Year-to-date awards reached S$1.7bn. The backlog supports activity across the yards, while customers’ final investment decisions will determine how quickly Seatrium can replenish work as projects are delivered. (Seatrium / Business Times)
Autos and banks drove India’s rally as cheaper inputs supported domestic cyclicals. The Nifty 50 rose 1.14% to 25,514.30 as 15 of 16 major sectors advanced. The auto index gained 4.4%, helped by lower commodity costs and strong festival sales. Nifty Financial Services rose 1.1% and the PSU Bank index 2.3%, while IT shares fell 1.1%. The split favoured businesses exposed to domestic demand over exporters sensitive to US technology spending. (NSE / Reuters)
EMEA and Others
Novartis narrows its sales growth outlook as patent expiries approach. Novartis (NOVN.SW) set a 5% annual constant-currency sales growth target for 2026–31. Its prior 5%–6% range covered 2025–30. The core operating margin target remains at least 40% by 2029. Management raised peak sales estimates for Kesimpta to US$8bn and for Scemblix and Leqvio to US$5bn each. Those medicines must help offset generic competition for Entresto. (Company / Reuters)
Germany and UniCredit agree principles for a Commerzbank combination. UniCredit (UCG.MI) agreed to keep its enlarged German business headquartered and listed in Frankfurt, and Berlin dropped its demand for two seats on Commerzbank’s supervisory board. Germany owns 13.3% of Commerzbank (CBK.DE). Its finance minister backed an orderly transfer of control. The agreement clears a political obstacle to a combination that would have more than €1.3tn of assets, while leaving the terms and timing of the merger to be settled. (Company / Reuters)
Evonik loses its takeover premium as BASF ends its pursuit. Evonik Industries (EVK.DE) fell 16.2% to €18.25 after BASF (BAS.DE) withdrew from discussions. Evonik had rejected two non-binding cash proposals, including €24 per share, valuing its equity at €11.2bn. BASF said it saw insufficient value in a higher bid after assessing Evonik’s standalone risks. Investors must now assess Evonik on the earnings and cash flow its specialty chemicals portfolio can generate without a buyer. (BASF / Reuters)
The IEA puts a figure on the loss of Gulf oil and gas supplies. The International Energy Agency put cumulative Gulf supply losses at 2.8bn barrels of oil and 60bn cubic metres of gas in its World Energy Outlook. Before the disruption, Asia received 80% of the oil and an even larger share of the LNG shipped through the Strait of Hormuz. The loss of supply buffers leaves Asian importers exposed to renewed disruption despite little change in crude futures. (IEA / Reuters)
Babcock nuclear and aviation work lifts margins despite flat full-year guidance. Babcock International (BAB.L) rose 9.4% as fiscal first-half underlying operating profit grew 13% YoY to £227m. Defence revenue rose 8.0%, and the group operating margin widened 50bps to 8.4%. Management retained its FY27 outlook and medium-term margin target of at least 9%. The £8.9bn backlog supports revenue, while new orders will determine how quickly the group can extend it. (Company / FactSet)
Traders' Corner
Our Technical View
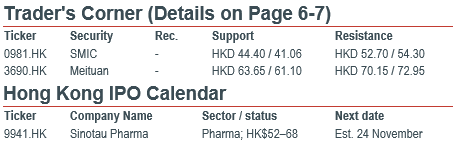
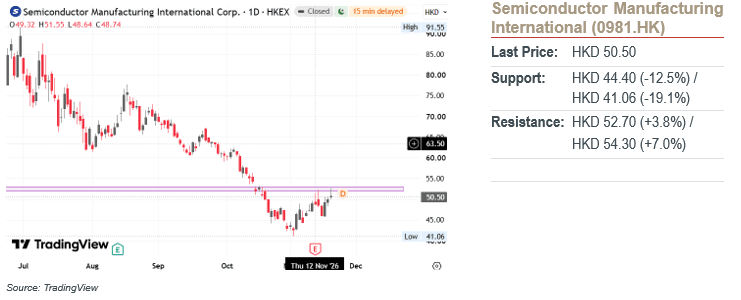
Price was rejected at its previous price high resistance zone, printing a shooting star candlestick pattern during yesterday's session.
The RSI hovers only slightly above its neutral 50 level, lacking the strong overbought expansion typically required to sustain a resistance breakout.
Provided price remains capped below the shooting star high and previous price high resistance ceiling, we see a downward rotation toward lower support levels.
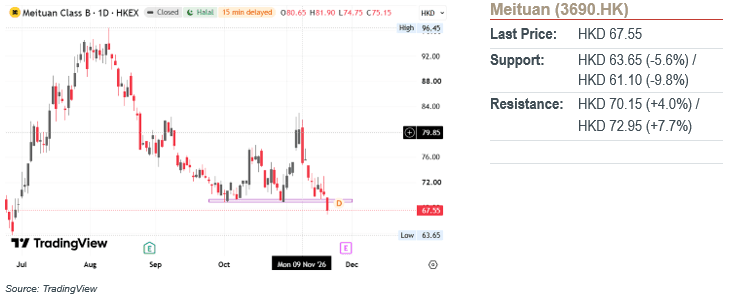
Our Technical View
Price violated its previous price low support zone with a prominent bearish candlestick during yesterday's session.
The RSI sits firmly in bearish territory and continues to fall.
Provided price remains capped below the violated support-turned-resistance ceiling, we see continued downward progression toward deeper structural lows.
Market Movers: At the 19 November close, The S&P 500 lost 2.0% and the Nasdaq Composite 2.3%, with more than nine in ten S&P constituents declining. Anthropic (ANT US) closed at US$97.17, 17.1% above its US$83 offer price but below its US$111.50 opening trade. Of the 980m shares offered, 956.4m were new shares, providing the Claude developer with fresh capital for computing capacity. Advanced Micro Devices (AMD US) fell 7.7% after a short seller questioned its exposure to restricted Chinese customers. AMD disputed the report. Tencent (0700.HK) fell 6.5% to HK$348.40 in the first Hong Kong session after it reported RMB81.4bn of capital expenditure and negative free cash flow of RMB69.1bn. Its cloud revenue grew 35.0%, but that growth has yet to absorb the cash cost of expansion. (Anthropic / AP / Reuters / Tencent / HKEX) Tencent (0700.HK) is our Core Recommendation.
Macro: US initial jobless claims rose by 1,000 to 203,000. Continuing claims rose by 70,000 to 1.76m, suggesting workers already on benefits faced a harder time finding a new job than the modest increase in new claims implied. In the Philadelphia Fed survey, the manufacturing activity index fell to 6.3 from 20.9 and new orders slipped below zero. The prices-paid index rose to 58.2. For manufacturers, the combination puts the focus on whether pricing can protect margins as orders soften. (US Department of Labor / Philadelphia Fed)
FICC: December gold settled 1.5% lower at US$3,685.50/oz and December silver lost 1.6% to US$44.36/oz. The US 10-year Treasury yield fell 3bps to 5.04%. January Brent settled at US$91.98/bbl and December WTI at US$83.21/bbl, both within US$0.05 of the previous settlement. At 05:26:52 SGT the US Dollar Index was live at 103.95, up 0.1% from its prior daily close and 5.8% since year-end. (AP / US Treasury / Reuters / Yahoo Finance)
AI
Anthropic record flotation gives investors a listed benchmark for frontier AI. Anthropic (ANT US) closed its first Nasdaq session at US$97.17, up 17.1% from the US$83 offer price. The 980m-share sale was worth US$81.34bn. Anthropic issued 956.4m shares to fund its business and selling holders supplied the balance. Investors who bought at the opening trade of US$111.50 finished the session with a loss despite the premium to the offer. (Company / Stock Titan)
China export concerns put AMD’s server business under scrutiny. Advanced Micro Devices (AMD US) fell 7.7% after Hunterbrook Capital disclosed a short position. Its research affiliate alleged that server makers tied to a restricted Chinese company used AMD firmware. Reuters could not independently verify the allegations. AMD said the report misrepresented its practices and that it complies with US export controls. Tighter distributor checks could lengthen delivery times even for permitted customers. (Reuters / The Fly)
Meta AI build-out puts its 2030 climate target under review. Meta Platforms (META US) is reviewing its 2030 value-chain net-zero target as it expands its AI infrastructure. Net greenhouse gas emissions rose 45% in 2025 to 11.8m metric tons of carbon dioxide equivalent. Meta contracted more than 10GW of clean energy capacity that year, yet equipment and construction emissions remain a drag on progress towards the target. (Company / Bloomberg) Meta Platforms (META US) is our Core Recommendation.
Palo Alto forecast draws buyers to cybersecurity as other AI stocks retreat. Palo Alto Networks (PANW US) rose 6.4% in its first regular session after announcing earnings and a US$4.5bn all-stock deal for Applied Compute. Fiscal 1Q revenue grew 39% YoY to US$3.44bn. Palo Alto expects FY27 revenue of US$14.52bn–14.57bn. The acquisition would let customers run open-weight models within their own security controls, extending Palo Alto’s reach into deployment. (Company / Reuters)
Americas
Walmart raises its outlook as online sales outpace its stores. Walmart (WMT US) raised FY27 adjusted EPS guidance to US$2.84–2.89 from US$2.80–2.87. Fiscal 3Q revenue rose 5.2% YoY to US$188.8bn and adjusted EPS of US$0.65 beat the US$0.64 consensus. Shares fell 1.0%. US e-commerce grew 23% and global advertising sales rose 25%, giving Walmart room to improve margins without raising shelf prices. (Company / AP) Walmart (WMT US) is our Core Recommendation.
Intuit agrees to sell Mailchimp as growth shifts to its small-business platform. At the US close, Intuit (INTU US) announced a US$3.68bn agreement with Bending Spoons. Intuit expects US$3.31bn in cash and US$368m in the buyer’s shares. Fiscal 1Q revenue rose 12% YoY to US$4.4bn, while Mailchimp revenue fell 1% to US$313m and online accounting revenue grew 19% to US$1.4bn. The sale would remove a slow-growing business. Intuit’s guidance still includes Mailchimp pending the expected closing in early 2027. (Company / Bending Spoons)
Williams-Sonoma unchanged outlook overshadows profit growth. Williams-Sonoma (WSM US) dropped 15.2% after revenue fell short of market expectations and the company reiterated its FY26 sales outlook. Fiscal 3Q comparable brand revenue rose 5.1%, and adjusted EPS grew 11.7% YoY to US$2.19. Higher oil prices added 50bps to supply-chain costs. Management retained its 4.7%–7.2% annual revenue-growth range. The sell-off leaves holiday demand and the ability to offset freight costs as the main tests of its operating margin. (Company / AP)
Ross Stores sustains customer traffic ahead of the holiday season. Ross Stores (ROST US) reported fiscal 3Q sales of US$6.3bn after the US close, up 12% YoY. Higher traffic helped lift comparable sales 8%, and operating margin widened 70bps to 12.3%. Management kept its 4Q comparable-sales growth outlook at 4%–5%. The prior-year gain of 9% makes further margin expansion a tougher proposition. (Company)
Greater China
Alibaba cloud margin expanded as recurring demand outpaced overall growth. Alibaba (9988.HK) grew September-quarter revenue 10% YoY to RMB271.5bn. Cloud and compute sales rose 53% to RMB61.0bn and the segment’s adjusted EBITA more than doubled to RMB8.84bn. Its AI labs and applications business, however, posted an adjusted EBITA loss of RMB10.5bn, up from RMB3.44bn. The contrast shows how much of the infrastructure profit is being reinvested in applications. (Alibaba / AP) Alibaba (9988.HK) is our Core Recommendation.
Tencent cash outflow put the cost of AI expansion in focus. Tencent (0700.HK) fell 6.5% to HK$348.40 in the first Hong Kong session after its 3Q results. Cloud revenue rose 35% YoY and marketing services revenue grew 19%, but the marketing gross margin fell to 52% from 57%. Capital expenditure reached RMB81.4bn and free cash flow was negative RMB69.1bn. Cash conversion now matters as much to the investment case as cloud demand. (Tencent / HKEX) Tencent (0700.HK) is our Core Recommendation.
Lenovo server earnings beat forecasts, but warrant revaluation pushed it to a statutory loss. Lenovo (0992.HK) fell 5.5% to HK$16.25. Fiscal 2Q revenue rose 48% YoY to US$30.2bn, above the US$27.6bn LSEG consensus. Infrastructure revenue grew 178% to US$11.3bn and segment operating profit exceeded US$1bn for the first time. A non-cash revaluation of warrants tied to the Alat partnership contributed to a US$640m statutory loss, even as adjusted net income rose 166% to US$1.36bn. (Lenovo / Reuters / HKEX)
NetEase improved gaming profitability as lower revenue-sharing costs cushioned softer sales. NetEase (9999.HK) reported 3Q revenue of RMB27.9bn, down 1.8% YoY. Revenue from games and related services fell 1.7% to RMB22.9bn, while group gross profit rose 4.8% to RMB19.0bn. Lower revenue-sharing costs and a 5.4% decline in operating expenses softened the earnings impact. Attributable net income was RMB8.4bn against RMB8.6bn a year earlier. (NetEase)
Kuaishou slipped to a loss as weaker merchant advertising squeezed margins. Kuaishou (1024.HK) posted a 3Q loss of RMB959m against a RMB4.5bn profit a year earlier. Revenue fell to RMB31.6bn from RMB35.6bn and gross margin narrowed to 48.2% from 54.7%. Online marketing sales fell 11.1% as merchants cut spending. Other services, including Kling AI, grew 1.5%, too slowly to offset weakness in advertising and livestreaming. (Kuaishou)
Asia ex. China
TSMC took a US$500m stake in Anthropic as Taiwanese chip shares fell. Taiwan’s TAIEX fell 4.4% to 38,426.89 and the semiconductor index lost 4.3%. Taiwan Semiconductor Manufacturing (TSM US) separately disclosed that its subsidiary bought 6.02m Anthropic shares at US$83 each. The US$500m investment took up the full sum authorised on 10 November. Its 0.03% stake gives the foundry direct financial exposure to the developer, with little voting influence. (TWSE / CNA / CNA filing report / TSMC) Taiwan Semiconductor Manufacturing (TSM US) is our Core Recommendation.
Seatrium expects a better project mix to lift FY26 underlying profit. Seatrium (5E2 SP) expects materially higher FY26 underlying net profit as project margins improve. Its S$12.2bn order book covers 35 projects with deliveries through 2033. Year-to-date awards reached S$1.7bn. The backlog supports activity across the yards, while customers’ final investment decisions will determine how quickly Seatrium can replenish work as projects are delivered. (Seatrium / Business Times)
Autos and banks drove India’s rally as cheaper inputs supported domestic cyclicals. The Nifty 50 rose 1.14% to 25,514.30 as 15 of 16 major sectors advanced. The auto index gained 4.4%, helped by lower commodity costs and strong festival sales. Nifty Financial Services rose 1.1% and the PSU Bank index 2.3%, while IT shares fell 1.1%. The split favoured businesses exposed to domestic demand over exporters sensitive to US technology spending. (NSE / Reuters)
EMEA and Others
Novartis narrows its sales growth outlook as patent expiries approach. Novartis (NOVN.SW) set a 5% annual constant-currency sales growth target for 2026–31. Its prior 5%–6% range covered 2025–30. The core operating margin target remains at least 40% by 2029. Management raised peak sales estimates for Kesimpta to US$8bn and for Scemblix and Leqvio to US$5bn each. Those medicines must help offset generic competition for Entresto. (Company / Reuters)
Germany and UniCredit agree principles for a Commerzbank combination. UniCredit (UCG.MI) agreed to keep its enlarged German business headquartered and listed in Frankfurt, and Berlin dropped its demand for two seats on Commerzbank’s supervisory board. Germany owns 13.3% of Commerzbank (CBK.DE). Its finance minister backed an orderly transfer of control. The agreement clears a political obstacle to a combination that would have more than €1.3tn of assets, while leaving the terms and timing of the merger to be settled. (Company / Reuters)
Evonik loses its takeover premium as BASF ends its pursuit. Evonik Industries (EVK.DE) fell 16.2% to €18.25 after BASF (BAS.DE) withdrew from discussions. Evonik had rejected two non-binding cash proposals, including €24 per share, valuing its equity at €11.2bn. BASF said it saw insufficient value in a higher bid after assessing Evonik’s standalone risks. Investors must now assess Evonik on the earnings and cash flow its specialty chemicals portfolio can generate without a buyer. (BASF / Reuters)
The IEA puts a figure on the loss of Gulf oil and gas supplies. The International Energy Agency put cumulative Gulf supply losses at 2.8bn barrels of oil and 60bn cubic metres of gas in its World Energy Outlook. Before the disruption, Asia received 80% of the oil and an even larger share of the LNG shipped through the Strait of Hormuz. The loss of supply buffers leaves Asian importers exposed to renewed disruption despite little change in crude futures. (IEA / Reuters)
Babcock nuclear and aviation work lifts margins despite flat full-year guidance. Babcock International (BAB.L) rose 9.4% as fiscal first-half underlying operating profit grew 13% YoY to £227m. Defence revenue rose 8.0%, and the group operating margin widened 50bps to 8.4%. Management retained its FY27 outlook and medium-term margin target of at least 9%. The £8.9bn backlog supports revenue, while new orders will determine how quickly the group can extend it. (Company / FactSet)
Traders' Corner
Our Technical View
Price was rejected at its previous price high resistance zone, printing a shooting star candlestick pattern during yesterday's session.
The RSI hovers only slightly above its neutral 50 level, lacking the strong overbought expansion typically required to sustain a resistance breakout.
Provided price remains capped below the shooting star high and previous price high resistance ceiling, we see a downward rotation toward lower support levels.
Our Technical View
Price violated its previous price low support zone with a prominent bearish candlestick during yesterday's session.
The RSI sits firmly in bearish territory and continues to fall.
Provided price remains capped below the violated support-turned-resistance ceiling, we see continued downward progression toward deeper structural lows.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


