Wealth Daily
Marvell and Lumentum Fall on US$115bn Deal
Today’s Must-Know News
Overnight Markets
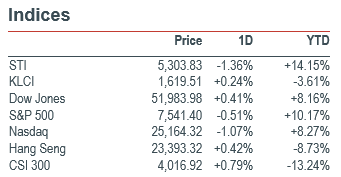
Market Movers: At the 2 November close, the S&P 500 fell 0.51% and the Nasdaq Composite lost 1.07%. Marvell (MRVL US) dropped 12.72% and Lumentum (LITE US) lost 18.59% after announcing an all-stock deal. The agreed 4.5 Marvell shares per Lumentum share implied a US$115bn enterprise value and a 23.9% premium at the unaffected 28 October prices. Monday’s fall in Marvell shares reduced the value of that offer. In Tokyo, Kioxia (285A.T) fell 15.78% in the first session after it forecast roughly flat quarterly revenue and profit despite strong data-centre demand. (AP / Marvell / Kioxia / Reuters) Lumentum (LITE US) is our Investment Opportunity.
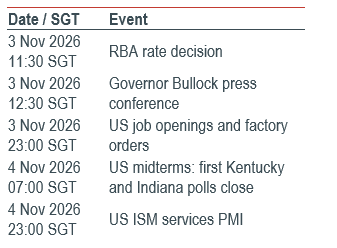
Macro: The US ISM manufacturing PMI rose to 55.50 from 54.50 as production accelerated. China’s private manufacturing PMI edged down to 52.0 from 52.1 as export orders grew at their slowest pace in three months. Economists expect the Reserve Bank of Australia to raise its cash rate by 25bps to 4.85% at 11:30 SGT on 3 November. Its new inflation forecasts will help investors judge whether another increase is likely. (ISM / Reuters / RBA / Economist poll)
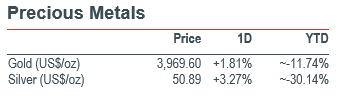
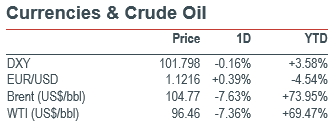
FICC: January Brent settled 7.63% lower at US$104.77/bbl and December WTI fell 7.36% to US$96.46/bbl as a draft peace proposal circulated after Qatari mediation. A resumption of oil flows through Hormuz still depends on an agreement. December gold rose 1.81% to US$3,969.60/oz and silver gained 3.27%. (Reuters / AP / Settlement data)
AI
• Marvell strikes US$115bn all-stock deal for Lumentum. Marvell (MRVL US) agreed to buy Lumentum (LITE US) in a transaction that implies US$115bn of enterprise value at unaffected 28 October prices. Each Lumentum share would receive 4.5 Marvell shares. Marvell fell 12.72% to US$171.41 and Lumentum lost 18.59% to US$684.40. The fixed ratio ties the value received by Lumentum holders to Marvell’s share price. (Joint release / Reuters / MRVL price / LITE price) Lumentum (LITE US) is our Investment Opportunity.
• Oracle seeks US$20bn for its AI build-out. Oracle (ORCL US) shares fell 8.76% to US$119.22 after Oracle outlined US$10bn each in common stock and bonds. The share sale would dilute existing holders. Oracle already had US$125.34bn of notes payable and other borrowings at August-end. Using equity alongside bonds limits the additional debt needed to expand its cloud infrastructure. (Reuters / Oracle filing / Market data)
• Palantir posts faster growth in US commercial sales. Palantir (PLTR US) reported the third-quarter revenue rose 96% YoY to US$2.31bn. US commercial revenue climbed 148% to US$984m, overtaking US government sales for the first time even as those rose 96% to US$953m. Shares traded at US$180.58 at 5:02pm New York time, 1.26% above the regular close. (Palantir / Market data)
• Onsemi adds power delivery for AI chips. Onsemi (ON US) agreed to buy voltage-regulator specialist Ferric for US$600m in cash plus up to US$175m tied to sales milestones. It raised its 2030 AI data-centre revenue target by US$500m to over US$3bn. Third-quarter revenue from that business rose 175% YoY, compared with 11% companywide. (Ferric agreement / onsemi results)
Americas
• Apple posts record September-quarter sales. Apple (AAPL US) revenue rose 12.0% YoY to US$114.5bn as iPhone sales set a September-quarter record and Services reached an all-time high. Diluted EPS increased 14% to US$2.10, including US$0.05 from tariff refunds. At 5:03pm New York time, shares traded at US$340.40, 0.61% above the regular close. (Apple / Axios / Market data)
• Marriott raises its room-revenue forecast. Marriott (MAR US) reported the third-quarter global revenue per available room rose 6.5% YoY in constant currency, led by 7.4% growth in the US and Canada. Marriott now expects full-year growth of 4.5–5.0%. Franchise and base management fees climbed 13% to US$1.34bn as occupancy, room rates and its footprint increased. Shares gained 4.26%. (Marriott / Market data)
• IDEXX Laboratories jumps on diagnostics demand. IDEXX Laboratories (IDXX US) shares climbed 21.85% to US$671.64 after third-quarter revenue grew 10% YoY to US$1.21bn and EPS rose 18% to US$4.01. Recurring companion-animal diagnostics revenue increased 11%. IDEXX raised the midpoint of its 2026 revenue outlook by US$32m as its installed base of analysers expanded. (IDEXX / AP / Market data)
• Tempus AI raises its precision-medicine sales forecast. Tempus AI (TEM US) posted the Third-quarter revenue grew 23% YoY to US$411.5m as oncology test volumes climbed 32% and data and applications revenue rose 33%. The company raised its full-year sales outlook to US$1.60–1.605bn and maintained its adjusted EBITDA forecast of about US$65m. Shares gained 8.67% to US$78.48. (Tempus AI / Market data)
• Kimberly-Clark completes Kenvue takeover. Kenvue holders receive US$3.50 in cash and 0.14625 Kimberly-Clark (KMB US) shares per share. Bringing Tylenol and Listerine alongside Huggies and Kleenex gives the combined group ten billion-dollar brands. Management reaffirmed a US$2.1bn run-rate synergy target, including US$1.9bn of cost savings expected in the first three years. (Kimberly-Clark)
• Blackstone and Canadian funds buy into LNG Canada. Blackstone (BX US) and its Canadian partners agreed to invest US$3.1bn for 49.9% of a Mitsubishi subsidiary holding 15% of the export project. Mitsubishi valued the stake being sold at about US$1.6bn. The balance would help fund a second phase intended to double the facility’s capacity. (Blackstone / Reuters)
• Estée Lauder lifts its outlook as margins recover. Estée Lauder (EL US) reported a 7% YoY rise in fiscal first-quarter sales to US$3.7bn, while organic sales rose 6%. Reported gross margin improved 230 basis points to 75.7%, helped by procurement savings, pricing and sales growth. Adjusted EPS more than doubled to US$0.72 from US$0.32. Shares nevertheless closed 4.08% lower. (Estée Lauder / Market data)
• Vertex raises its full-year revenue range. Vertex (VRTX US) reported a 12% YoY rise in third-quarter revenue to US$3.44bn, with growth of 16% outside the US and 10% at home. Cystic fibrosis medicines led sales, while gene therapy Casgevy generated US$99m against US$17m a year earlier. Vertex raised both ends of its 2026 revenue forecast by US$50m. (Vertex)
• Fox benefits from the World Cup and political advertising. Fox (FOXA US) reported a 22% YoY rise in fiscal first-quarter revenue to US$4.57bn. Advertising grew 47% as the men’s World Cup, election campaigns and streaming service Tubi brought in more revenue. Distribution revenue increased 9%. Adjusted EBITDA rose 54% to US$1.64bn despite higher sports rights and production costs. (Fox Corporation)
• PSEG separates nuclear market losses from operating earnings. PSEG (PEG US) posted the third-quarter net income fell 40% YoY to US$376m as the power business recorded mark-to-market and nuclear decommissioning trust losses. Operating EPS rose to US$1.15 from US$1.13 as nuclear generation increased. PSEG retained its full-year operating EPS range of US$4.28–4.40. (PSEG)
Greater China
• China Mobile awards AI server order to Dahua. Dahua said its subsidiary won an estimated RMB2.63bn share, including tax, of the AI computing tender run by China Mobile (0941.HK), against an earlier RMB2.05bn ceiling. Its allocation covers 4,096 of the 20,480 accelerator cards requested. The parties had yet to sign a contract, leaving the timing of supplier revenue open. (Dahua filing / Yicai) China Mobile (0941.HK) is our Core Recommendation.
• Bank of China falls after earnings. Bank of China (3988.HK) fell 4.64% to HK$5.86 in Hong Kong in its first session after results. Third-quarter attributable profit rose 6.36% YoY to RMB63.89bn on 4.3% operating income growth. Over nine months, net interest income rose 10.38% while net fee and commission income grew just 0.07%, concentrating growth in lending. (Bank of China / Market data)
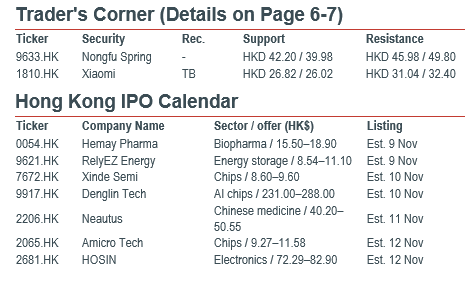
• Xiaomi EV deliveries lift its shares. Xiaomi (1810.HK) rose 6.12% to HK$28.10 in the first session after the company reported more than 50,000 October deliveries, its strongest month this year. About 336,000 vehicles reached customers in ten months, leaving roughly 214,000 to deliver in November and December to meet management’s full-year target of 550,000. (Reuters / Market data)
• China cuts the cost of financing share buybacks. The People’s Bank of China made its buyback and shareholder purchase lending facility permanent and cut the refinancing rate to 1% from 1.25%. Separately, 31 brokers and fund managers sought more than RMB100bn in one-year swaps, letting them raise funds against collateral for equity purchases. (PBOC policy / Swap notice)
Asia ex. China
• Kioxia falls on its December-quarter outlook. Kioxia (285A.T) closed 15.78% lower at ¥11,345 in the first Tokyo session after results. The NAND memory maker’s guidance implies ¥1.995tn of operating profit for the December quarter. That outlook disappointed investors despite half-year revenue of ¥4.25tn, up 436.8% YoY, as the memory cycle lifted sales to data centres. (Kioxia / Reuters / Market data)
• Tokyo Electron climbs on equipment demand. Shares of chipmaking equipment supplier Tokyo Electron (8035.T) rose 5.16% to ¥10,005 in the first session after its forecast. Management expects operating profit of ¥1.17tn for the year to March, up 87.1% YoY, on sales growth of 51.4%. Investment in advanced logic and memory chips is translating into stronger equipment demand. (Tokyo Electron / Reuters / Market data)
• Sumitomo Corporation raises its profit and dividend forecasts. Trading house Sumitomo Corporation (8053.T) raised its annual net profit forecast from ¥630bn to ¥670bn, about 12% above last year, and increased its proposed annual dividend from ¥40 to ¥44 per share. Strong gas trading, higher copper prices and earnings from aluminium processing helped fund the higher distribution. (Sumitomo Corporation / Reuters)
• Great Eastern’s investment losses overshadow insurance growth. Great Eastern (G07.SI) reported a 72% YoY fall in third-quarter net profit to S$102.9m on weaker investment valuations and a loss from selling part of its Indonesian business. Core insurance profit rose 6% to S$179.3m, while new business embedded value increased 14%, indicating that new policies became more valuable despite lower sales. (Great Eastern / The Business Times)
• Singapore factories expand at a slower pace. October’s manufacturing purchasing managers’ index fell to 51.4 from 51.7. Electronics, which accounts for about 40% of factory output, slipped to 52.5 from 52.9. Both readings stayed above the 50 growth threshold. Slower new-order growth and faster input-cost increases point to pressure on manufacturers’ margins. (The Straits Times / SIPMM)
EMEA and Others
• Alstom slashes margin and cash forecasts. Alstom (ALO.PA) fell 26.09% to €11.685 after German Coradia Max train projects ran into production and certification delays. The group cut its full-year adjusted operating margin target from about 6.5% to around 1% and now expects negative free cash flow of €1.5bn, increasing the challenge of achieving its €2bn deleveraging objective. (Alstom / Reuters / Market data)
• Ryanair advances despite higher fuel costs. Ryanair (RYA.IR) gained 5.24% to €24.10 as the airline announced an €800m buyback starting in February. First-half profit after tax fell 15% YoY to €2.15bn as unhedged fuel prices doubled and average fares fell 4%. Hedging covers 80% of current-year fuel needs at about US$67 a barrel, partly cushioning earnings. (Ryanair / Reuters / Market data)
• ADNOC brings AI into energy operations. The Abu Dhabi group agreed with OpenAI and G42 to deploy AI across its operations, investment and commercial decisions. Computing infrastructure in the UAE will run the models locally. The energy deal was one of four agreements announced with OpenAI, extending adoption beyond the emirate’s data centres. (Emirates News Agency / Reuters)
• Bavarian Nordic secures four years of UK vaccine orders. he UK Health Security Agency contracted Bavarian Nordic (BAVA.CO) for four years of scheduled deliveries of its mpox and smallpox vaccine, extending government demand beyond emergency purchases. The manufacturer also completed a DKK250m buyback, the first tranche of a plan for up to DKK750m. Shares gained 2.36% to DKK251.20. (Company release / Buyback notice / Market data)
Traders' Corner
Our Technical View
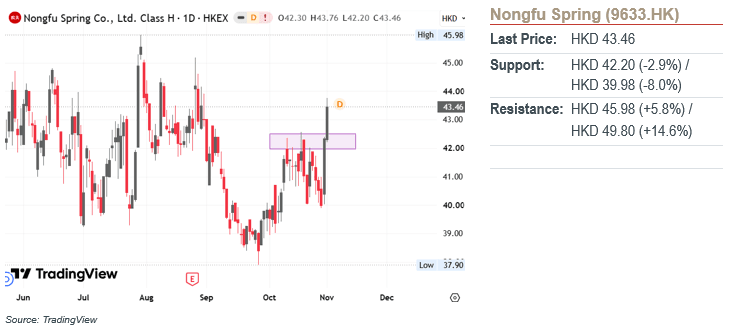
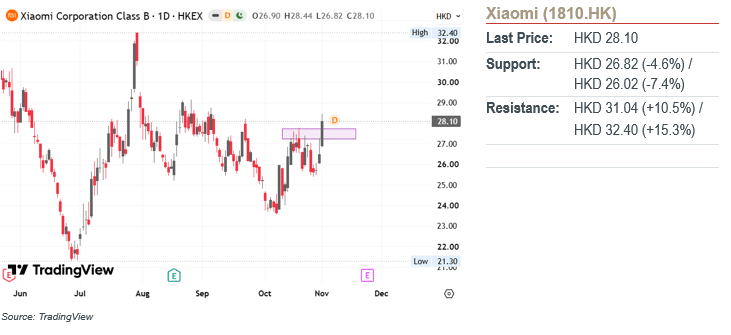
Price penetrated its recent swing high, confirming a high-conviction structural breakout and reinforcing the sequence of higher highs and higher lows.
The RSI is anchored in bullish territory and continues to slope upward with strong positive velocity.
As long as price remains defended above the newly converted breakout baseline, we see continued upward expansion toward higher targets.
Our Technical View
Price executed a high-conviction bullish continuation wave, penetrating its recent swing high following a successful breakout from a bull flag pattern.
The RSI has turned bullish and is sloping upward with strong positive velocity.
As long as price remains defended above the newly established breakout baseline, we see continued upward expansion toward higher targets.
Market Movers: At the 2 November close, the S&P 500 fell 0.51% and the Nasdaq Composite lost 1.07%. Marvell (MRVL US) dropped 12.72% and Lumentum (LITE US) lost 18.59% after announcing an all-stock deal. The agreed 4.5 Marvell shares per Lumentum share implied a US$115bn enterprise value and a 23.9% premium at the unaffected 28 October prices. Monday’s fall in Marvell shares reduced the value of that offer. In Tokyo, Kioxia (285A.T) fell 15.78% in the first session after it forecast roughly flat quarterly revenue and profit despite strong data-centre demand. (AP / Marvell / Kioxia / Reuters) Lumentum (LITE US) is our Investment Opportunity.
Macro: The US ISM manufacturing PMI rose to 55.50 from 54.50 as production accelerated. China’s private manufacturing PMI edged down to 52.0 from 52.1 as export orders grew at their slowest pace in three months. Economists expect the Reserve Bank of Australia to raise its cash rate by 25bps to 4.85% at 11:30 SGT on 3 November. Its new inflation forecasts will help investors judge whether another increase is likely. (ISM / Reuters / RBA / Economist poll)
FICC: January Brent settled 7.63% lower at US$104.77/bbl and December WTI fell 7.36% to US$96.46/bbl as a draft peace proposal circulated after Qatari mediation. A resumption of oil flows through Hormuz still depends on an agreement. December gold rose 1.81% to US$3,969.60/oz and silver gained 3.27%. (Reuters / AP / Settlement data)
AI
• Marvell strikes US$115bn all-stock deal for Lumentum. Marvell (MRVL US) agreed to buy Lumentum (LITE US) in a transaction that implies US$115bn of enterprise value at unaffected 28 October prices. Each Lumentum share would receive 4.5 Marvell shares. Marvell fell 12.72% to US$171.41 and Lumentum lost 18.59% to US$684.40. The fixed ratio ties the value received by Lumentum holders to Marvell’s share price. (Joint release / Reuters / MRVL price / LITE price) Lumentum (LITE US) is our Investment Opportunity.
• Oracle seeks US$20bn for its AI build-out. Oracle (ORCL US) shares fell 8.76% to US$119.22 after Oracle outlined US$10bn each in common stock and bonds. The share sale would dilute existing holders. Oracle already had US$125.34bn of notes payable and other borrowings at August-end. Using equity alongside bonds limits the additional debt needed to expand its cloud infrastructure. (Reuters / Oracle filing / Market data)
• Palantir posts faster growth in US commercial sales. Palantir (PLTR US) reported the third-quarter revenue rose 96% YoY to US$2.31bn. US commercial revenue climbed 148% to US$984m, overtaking US government sales for the first time even as those rose 96% to US$953m. Shares traded at US$180.58 at 5:02pm New York time, 1.26% above the regular close. (Palantir / Market data)
• Onsemi adds power delivery for AI chips. Onsemi (ON US) agreed to buy voltage-regulator specialist Ferric for US$600m in cash plus up to US$175m tied to sales milestones. It raised its 2030 AI data-centre revenue target by US$500m to over US$3bn. Third-quarter revenue from that business rose 175% YoY, compared with 11% companywide. (Ferric agreement / onsemi results)
Americas
• Apple posts record September-quarter sales. Apple (AAPL US) revenue rose 12.0% YoY to US$114.5bn as iPhone sales set a September-quarter record and Services reached an all-time high. Diluted EPS increased 14% to US$2.10, including US$0.05 from tariff refunds. At 5:03pm New York time, shares traded at US$340.40, 0.61% above the regular close. (Apple / Axios / Market data)
• Marriott raises its room-revenue forecast. Marriott (MAR US) reported the third-quarter global revenue per available room rose 6.5% YoY in constant currency, led by 7.4% growth in the US and Canada. Marriott now expects full-year growth of 4.5–5.0%. Franchise and base management fees climbed 13% to US$1.34bn as occupancy, room rates and its footprint increased. Shares gained 4.26%. (Marriott / Market data)
• IDEXX Laboratories jumps on diagnostics demand. IDEXX Laboratories (IDXX US) shares climbed 21.85% to US$671.64 after third-quarter revenue grew 10% YoY to US$1.21bn and EPS rose 18% to US$4.01. Recurring companion-animal diagnostics revenue increased 11%. IDEXX raised the midpoint of its 2026 revenue outlook by US$32m as its installed base of analysers expanded. (IDEXX / AP / Market data)
• Tempus AI raises its precision-medicine sales forecast. Tempus AI (TEM US) posted the Third-quarter revenue grew 23% YoY to US$411.5m as oncology test volumes climbed 32% and data and applications revenue rose 33%. The company raised its full-year sales outlook to US$1.60–1.605bn and maintained its adjusted EBITDA forecast of about US$65m. Shares gained 8.67% to US$78.48. (Tempus AI / Market data)
• Kimberly-Clark completes Kenvue takeover. Kenvue holders receive US$3.50 in cash and 0.14625 Kimberly-Clark (KMB US) shares per share. Bringing Tylenol and Listerine alongside Huggies and Kleenex gives the combined group ten billion-dollar brands. Management reaffirmed a US$2.1bn run-rate synergy target, including US$1.9bn of cost savings expected in the first three years. (Kimberly-Clark)
• Blackstone and Canadian funds buy into LNG Canada. Blackstone (BX US) and its Canadian partners agreed to invest US$3.1bn for 49.9% of a Mitsubishi subsidiary holding 15% of the export project. Mitsubishi valued the stake being sold at about US$1.6bn. The balance would help fund a second phase intended to double the facility’s capacity. (Blackstone / Reuters)
• Estée Lauder lifts its outlook as margins recover. Estée Lauder (EL US) reported a 7% YoY rise in fiscal first-quarter sales to US$3.7bn, while organic sales rose 6%. Reported gross margin improved 230 basis points to 75.7%, helped by procurement savings, pricing and sales growth. Adjusted EPS more than doubled to US$0.72 from US$0.32. Shares nevertheless closed 4.08% lower. (Estée Lauder / Market data)
• Vertex raises its full-year revenue range. Vertex (VRTX US) reported a 12% YoY rise in third-quarter revenue to US$3.44bn, with growth of 16% outside the US and 10% at home. Cystic fibrosis medicines led sales, while gene therapy Casgevy generated US$99m against US$17m a year earlier. Vertex raised both ends of its 2026 revenue forecast by US$50m. (Vertex)
• Fox benefits from the World Cup and political advertising. Fox (FOXA US) reported a 22% YoY rise in fiscal first-quarter revenue to US$4.57bn. Advertising grew 47% as the men’s World Cup, election campaigns and streaming service Tubi brought in more revenue. Distribution revenue increased 9%. Adjusted EBITDA rose 54% to US$1.64bn despite higher sports rights and production costs. (Fox Corporation)
• PSEG separates nuclear market losses from operating earnings. PSEG (PEG US) posted the third-quarter net income fell 40% YoY to US$376m as the power business recorded mark-to-market and nuclear decommissioning trust losses. Operating EPS rose to US$1.15 from US$1.13 as nuclear generation increased. PSEG retained its full-year operating EPS range of US$4.28–4.40. (PSEG)
Greater China
• China Mobile awards AI server order to Dahua. Dahua said its subsidiary won an estimated RMB2.63bn share, including tax, of the AI computing tender run by China Mobile (0941.HK), against an earlier RMB2.05bn ceiling. Its allocation covers 4,096 of the 20,480 accelerator cards requested. The parties had yet to sign a contract, leaving the timing of supplier revenue open. (Dahua filing / Yicai) China Mobile (0941.HK) is our Core Recommendation.
• Bank of China falls after earnings. Bank of China (3988.HK) fell 4.64% to HK$5.86 in Hong Kong in its first session after results. Third-quarter attributable profit rose 6.36% YoY to RMB63.89bn on 4.3% operating income growth. Over nine months, net interest income rose 10.38% while net fee and commission income grew just 0.07%, concentrating growth in lending. (Bank of China / Market data)
• Xiaomi EV deliveries lift its shares. Xiaomi (1810.HK) rose 6.12% to HK$28.10 in the first session after the company reported more than 50,000 October deliveries, its strongest month this year. About 336,000 vehicles reached customers in ten months, leaving roughly 214,000 to deliver in November and December to meet management’s full-year target of 550,000. (Reuters / Market data)
• China cuts the cost of financing share buybacks. The People’s Bank of China made its buyback and shareholder purchase lending facility permanent and cut the refinancing rate to 1% from 1.25%. Separately, 31 brokers and fund managers sought more than RMB100bn in one-year swaps, letting them raise funds against collateral for equity purchases. (PBOC policy / Swap notice)
Asia ex. China
• Kioxia falls on its December-quarter outlook. Kioxia (285A.T) closed 15.78% lower at ¥11,345 in the first Tokyo session after results. The NAND memory maker’s guidance implies ¥1.995tn of operating profit for the December quarter. That outlook disappointed investors despite half-year revenue of ¥4.25tn, up 436.8% YoY, as the memory cycle lifted sales to data centres. (Kioxia / Reuters / Market data)
• Tokyo Electron climbs on equipment demand. Shares of chipmaking equipment supplier Tokyo Electron (8035.T) rose 5.16% to ¥10,005 in the first session after its forecast. Management expects operating profit of ¥1.17tn for the year to March, up 87.1% YoY, on sales growth of 51.4%. Investment in advanced logic and memory chips is translating into stronger equipment demand. (Tokyo Electron / Reuters / Market data)
• Sumitomo Corporation raises its profit and dividend forecasts. Trading house Sumitomo Corporation (8053.T) raised its annual net profit forecast from ¥630bn to ¥670bn, about 12% above last year, and increased its proposed annual dividend from ¥40 to ¥44 per share. Strong gas trading, higher copper prices and earnings from aluminium processing helped fund the higher distribution. (Sumitomo Corporation / Reuters)
• Great Eastern’s investment losses overshadow insurance growth. Great Eastern (G07.SI) reported a 72% YoY fall in third-quarter net profit to S$102.9m on weaker investment valuations and a loss from selling part of its Indonesian business. Core insurance profit rose 6% to S$179.3m, while new business embedded value increased 14%, indicating that new policies became more valuable despite lower sales. (Great Eastern / The Business Times)
• Singapore factories expand at a slower pace. October’s manufacturing purchasing managers’ index fell to 51.4 from 51.7. Electronics, which accounts for about 40% of factory output, slipped to 52.5 from 52.9. Both readings stayed above the 50 growth threshold. Slower new-order growth and faster input-cost increases point to pressure on manufacturers’ margins. (The Straits Times / SIPMM)
EMEA and Others
• Alstom slashes margin and cash forecasts. Alstom (ALO.PA) fell 26.09% to €11.685 after German Coradia Max train projects ran into production and certification delays. The group cut its full-year adjusted operating margin target from about 6.5% to around 1% and now expects negative free cash flow of €1.5bn, increasing the challenge of achieving its €2bn deleveraging objective. (Alstom / Reuters / Market data)
• Ryanair advances despite higher fuel costs. Ryanair (RYA.IR) gained 5.24% to €24.10 as the airline announced an €800m buyback starting in February. First-half profit after tax fell 15% YoY to €2.15bn as unhedged fuel prices doubled and average fares fell 4%. Hedging covers 80% of current-year fuel needs at about US$67 a barrel, partly cushioning earnings. (Ryanair / Reuters / Market data)
• ADNOC brings AI into energy operations. The Abu Dhabi group agreed with OpenAI and G42 to deploy AI across its operations, investment and commercial decisions. Computing infrastructure in the UAE will run the models locally. The energy deal was one of four agreements announced with OpenAI, extending adoption beyond the emirate’s data centres. (Emirates News Agency / Reuters)
• Bavarian Nordic secures four years of UK vaccine orders. he UK Health Security Agency contracted Bavarian Nordic (BAVA.CO) for four years of scheduled deliveries of its mpox and smallpox vaccine, extending government demand beyond emergency purchases. The manufacturer also completed a DKK250m buyback, the first tranche of a plan for up to DKK750m. Shares gained 2.36% to DKK251.20. (Company release / Buyback notice / Market data)
Traders' Corner
Our Technical View
Price penetrated its recent swing high, confirming a high-conviction structural breakout and reinforcing the sequence of higher highs and higher lows.
The RSI is anchored in bullish territory and continues to slope upward with strong positive velocity.
As long as price remains defended above the newly converted breakout baseline, we see continued upward expansion toward higher targets.
Our Technical View
Price executed a high-conviction bullish continuation wave, penetrating its recent swing high following a successful breakout from a bull flag pattern.
The RSI has turned bullish and is sloping upward with strong positive velocity.
As long as price remains defended above the newly established breakout baseline, we see continued upward expansion toward higher targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


