Key Indices
Top Stories
Sector Initiate Coverage | Mechanical, Electrical And Plumbing (MEP)
- The MEP sector is entering a multi-year upcycle, underpinned by TNB’s RM90b grid investment roadmap, accelerating DC expansion, RE integration and semiconductor investments. Strong demand for substations, underground utilities and MEP fit-out underpins our projected 30% segment core earnings CAGR over 2025-28. We initiate coverage with OVERWEIGHT, viewing the recent valuation retracement to 15x 2027F PE as an attractive accumulation opportunity. Our top picks are MN Holdings (BUY/Target: RM4.62), HE Group (BUY/Target: RM1.38) and UUE Holdings (BUY/Target: RM0.95).
Company Results | Inari Amertron (INRI MK/BUY/RM2.06/Target: RM2.48)
- Inari’s 1QFY27 core net profit came in stronger at RM61.9m (+28% qoq, +13% yoy), accounting for 24%/23% of our/consensus full-year forecasts respectively. While FY26 was weighed by weaker RF volumes, we expect a recovery in FY27 as RF content increases and ChipFab volumes potentially double, supported by 1.6T applications and AI/DC capex. No change to earnings. Upgrade to BUY with an unchanged target price of RM2.48.
Company Results | Pecca Group (PECCA MK/HOLD/RM1.42/Target: RM1.35)
- Pecca’s 1QFY27 results came in below expectations, accounting for 18% of our forecast, due to softer demand from key automotive customers. We expect a modest earnings recovery over the coming quarters, with more meaningful growth likely to materialise after the launch of Perodua’s new model. Maintain HOLD with a lower target price of RM1.35 (from RM1.42).
Company Results | VSTECS (VST MK/BUY/RM1.30/Target: RM2.26)
- VSTECS’ 3Q26 earnings came in strongly on robust growth across all three business segments. We expect the growth momentum to extend into 4Q26, underpinned by resilient demand in the ICT distribution segment alongside continued public-sector spending. Maintain BUY with an unchanged target price of RM2.26.
What’s Inside
Company Results | Hume Cement Industries (HUME MK/BUY/RM2.56/Target: RM4.16)
- Hume reported a 1QFY27 net profit of RM64.4m (+5% yoy; +5% qoq). The sequential earnings growth was mainly attributed to strong cement sales volume but was partially dragged by lower ASPs and rising coal prices. Accounting for 26% of our FY27 earnings forecast, we deem the results to be within expectation. The group declared a higher first interim DPS of 7.0 sen, largely in line with our FY27 forecast of 13.8 sen. Maintain BUY with a target price of RM4.16.
Company Results | Kossan Rubber Industries (KRI MK/BUY/RM1.21/Target: RM1.31)
- Kossan reported stronger yoy revenue and core earnings in 3Q26. The earnings strength mainly stems from higher ASPs and better volume sales, besides a marginally stronger MYR/USD rate. For 4Q26-1H27, however, we expect a normalising earnings base as ASPs moderated 15-20% from 3Q26’s peak as the ongoing Iran war and raw material prices retraced. Kossan’s strong balance sheet and potentially better capital management, alongside cleanroom expansions are still key re-rating catalysts. Maintain BUY and target price of RM1.31.
Company Results | Sports Toto (SPTOTO MK/BUY/RM1.28/Target: RM1.42)
- SPTOTO’s 1QFY27 results came in below expectations, reflecting weaker STM operations due to lower ticket sales and higher prize payout. HR Owen performances saw slight improvement following cost rationalisation efforts. Overall, SPTOTO’s commendable dividend yield of 7.5-8.3% through FY27-29 and defensive business nature should provide moderate capital upside amid the current global market uncertainties. Maintain BUY with a lower target price of RM1.42.
Market Spotlight
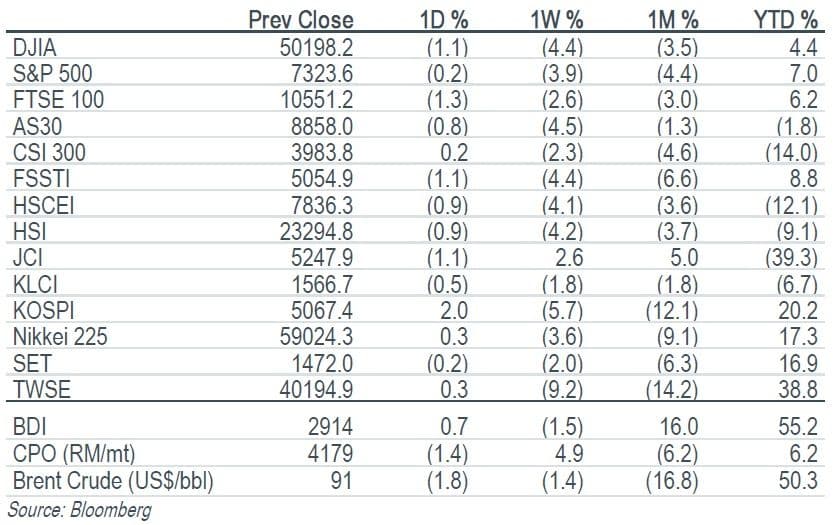
- The FBMKLCI fell 8.42pt to close at 1,566.73 yesterday following profit-taking in blue chips.
- Wall Street ended mixed in a choppy trading session on Wednesday, with the Nasdaq Composite in particular swinging between gains and losses as questions continued to swirl around Nvidia despite the chipmaker’s blowout quarterly results and guidance.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Genetec Technology | GENE MK
- Trading Buy Range: RM0.305-0.31
JS Solar Holding | JSSOLAR MK
- Trading Buy Range: RM0.225-0.23
Manforce Group | MFGROUP MK
- Trading Buy Range: RM0.315-0.32
Top Stories
Sector Initiate Coverage | Mechanical, Electrical And Plumbing (MEP)
- The MEP sector is entering a multi-year upcycle, underpinned by TNB’s RM90b grid investment roadmap, accelerating DC expansion, RE integration and semiconductor investments. Strong demand for substations, underground utilities and MEP fit-out underpins our projected 30% segment core earnings CAGR over 2025-28. We initiate coverage with OVERWEIGHT, viewing the recent valuation retracement to 15x 2027F PE as an attractive accumulation opportunity. Our top picks are MN Holdings (BUY/Target: RM4.62), HE Group (BUY/Target: RM1.38) and UUE Holdings (BUY/Target: RM0.95).
Company Results | Inari Amertron (INRI MK/BUY/RM2.06/Target: RM2.48)
- Inari’s 1QFY27 core net profit came in stronger at RM61.9m (+28% qoq, +13% yoy), accounting for 24%/23% of our/consensus full-year forecasts respectively. While FY26 was weighed by weaker RF volumes, we expect a recovery in FY27 as RF content increases and ChipFab volumes potentially double, supported by 1.6T applications and AI/DC capex. No change to earnings. Upgrade to BUY with an unchanged target price of RM2.48.
Company Results | Pecca Group (PECCA MK/HOLD/RM1.42/Target: RM1.35)
- Pecca’s 1QFY27 results came in below expectations, accounting for 18% of our forecast, due to softer demand from key automotive customers. We expect a modest earnings recovery over the coming quarters, with more meaningful growth likely to materialise after the launch of Perodua’s new model. Maintain HOLD with a lower target price of RM1.35 (from RM1.42).
Company Results | VSTECS (VST MK/BUY/RM1.30/Target: RM2.26)
- VSTECS’ 3Q26 earnings came in strongly on robust growth across all three business segments. We expect the growth momentum to extend into 4Q26, underpinned by resilient demand in the ICT distribution segment alongside continued public-sector spending. Maintain BUY with an unchanged target price of RM2.26.
What’s Inside
Company Results | Hume Cement Industries (HUME MK/BUY/RM2.56/Target: RM4.16)
- Hume reported a 1QFY27 net profit of RM64.4m (+5% yoy; +5% qoq). The sequential earnings growth was mainly attributed to strong cement sales volume but was partially dragged by lower ASPs and rising coal prices. Accounting for 26% of our FY27 earnings forecast, we deem the results to be within expectation. The group declared a higher first interim DPS of 7.0 sen, largely in line with our FY27 forecast of 13.8 sen. Maintain BUY with a target price of RM4.16.
Company Results | Kossan Rubber Industries (KRI MK/BUY/RM1.21/Target: RM1.31)
- Kossan reported stronger yoy revenue and core earnings in 3Q26. The earnings strength mainly stems from higher ASPs and better volume sales, besides a marginally stronger MYR/USD rate. For 4Q26-1H27, however, we expect a normalising earnings base as ASPs moderated 15-20% from 3Q26’s peak as the ongoing Iran war and raw material prices retraced. Kossan’s strong balance sheet and potentially better capital management, alongside cleanroom expansions are still key re-rating catalysts. Maintain BUY and target price of RM1.31.
Company Results | Sports Toto (SPTOTO MK/BUY/RM1.28/Target: RM1.42)
- SPTOTO’s 1QFY27 results came in below expectations, reflecting weaker STM operations due to lower ticket sales and higher prize payout. HR Owen performances saw slight improvement following cost rationalisation efforts. Overall, SPTOTO’s commendable dividend yield of 7.5-8.3% through FY27-29 and defensive business nature should provide moderate capital upside amid the current global market uncertainties. Maintain BUY with a lower target price of RM1.42.
Market Spotlight
- The FBMKLCI fell 8.42pt to close at 1,566.73 yesterday following profit-taking in blue chips.
- Wall Street ended mixed in a choppy trading session on Wednesday, with the Nasdaq Composite in particular swinging between gains and losses as questions continued to swirl around Nvidia despite the chipmaker’s blowout quarterly results and guidance.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Genetec Technology | GENE MK
- Trading Buy Range: RM0.305-0.31
JS Solar Holding | JSSOLAR MK
- Trading Buy Range: RM0.225-0.23
Manforce Group | MFGROUP MK
- Trading Buy Range: RM0.315-0.32
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


