Key Indices
Top Stories
Company Results | 99 Speed Mart Retail Holdings (99SMART MK/BUY/RM2.96/Target: RM4.00)
- 99SM’s 9M26 results met expectations. While SSSG slowed marginally qoq, growth was still robust across existing stores while new store openings have already reached 99SM’s full-year target. Margins also grew off better cost optimisations. Maintain BUY with an unchanged target price of RM4.00.
Company Results | Dialog Group (DLG MK/BUY/RM1.87/Target: RM2.95)
- 1QFY27 results were in line with expectations. We believe upstream earnings was lackluster considering favourable oil prices, as ongoing maintenance still cap volume upside from a Production Sharing Contract (PSC). As expected and highlighted by Royal Vopak, storage earnings are flattish qoq, but it will be sustainable. We anticipate the debut of Cendramas and Baram Junior Cluster (BJC; which had early first gas production) PSCs in upcoming 2QFY27 results. Maintain BUY with a target price of RM2.95.
Company Results | Hap Seng Plantations (HAPL MK/BUY/RM2.21/Target: RM3.05)
- HAPL's 9M26 core net profit of RM116.8m came in line with expectations, accounting for 70% of our full-year forecast. We expect a stronger performance in 4Q26 driven by seasonal peak production cycle and brought forward sales from this quarter. Maintain BUY and a target price of RM3.05, pegged to 12x 2027 PE.
Company Results | Mr D.I.Y. Group (M) (MRDIY MK/BUY/RM1.04/Target: RM1.50)
- 9M26 results missed expectations. SSSG contracted for the second quarter in a row while less favourable forex and product mix saw margins contract sequentially. Going forward, the group is likely to hike prices of certain products in response to the higher costs as well as the minimum wage increase. MRDIY has also trimmed its new store opening target, shifting its focus to refurbishming its older store base. Maintain BUY with a lower target price of RM1.50 (from RM1.65).
Company Results | Solarvest Holdings (SOLAR MK/BUY/RM3.51/Target: RM5.30)
- Solarvest’s 2QFY27 core net profit rose to RM26.3m (+40% yoy; +38% qoq), driven by higher progress billing of utility-scale EPCC jobs, as well as higher RE generation and an O&M earnings base. 2QFY27 net margin has normalised to 10%, within expectations. 1HFY27 net profit accounts for 39% of our full-year earnings, and is deemed in line with expectations as higher EPCC contribution will drive 2HFY27 earnings. We expect a potential 300-500MW CRESS win in 4Q26/1Q27. Maintain BUY. Target price: RM5.30.
What’s Inside
Company Results | Duopharma Biotech (DBB MK/BUY/RM1.08/Target: RM1.62)
- Duopharma’s 2Q26 earnings came above expectations, accounting for 87%/84% of our and consensus full-year forecasts. However, we remain cautious on persistent high input cost and a stronger US dollar, which could weigh on margins in the coming quarters. That said, Duopharma offers defensive, domestically-driven growth and bargain valuations at current share price. Maintain BUY with a target price of RM1.62.
Market Spotlight
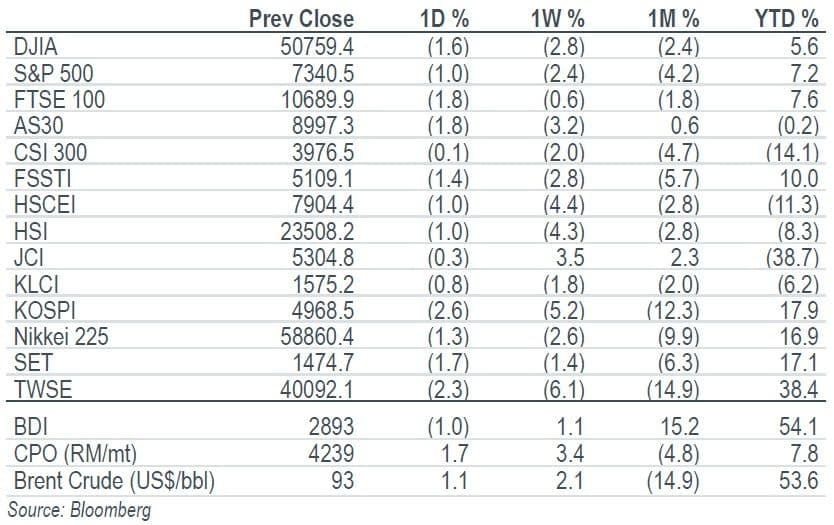
- The FBMKLCI dropped 12.88pt (-0.81%) to close at 1,575.15 yesterday as investors remained cautious over the uncertain global environment and due to the lack of fresh local catalysts.
- Wall Street ended lower on Tuesday, as investors displayed caution ahead of Nvidia’s much-anticipated quarterly results which could offer insight into both the outlook for the chip giant and the wider artificial intelligence trade.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Ecofirst Consolidated | ECOF MK
- Trading Buy Range: RM0.33-0.34
Pavilion REITs | PREIT MK
- Trading Buy Range: RM1.61-1.62
Ramssol Group | RAMSSOL MK
- Trading Buy Range: RM0.805-0.81
Top Stories
Company Results | 99 Speed Mart Retail Holdings (99SMART MK/BUY/RM2.96/Target: RM4.00)
- 99SM’s 9M26 results met expectations. While SSSG slowed marginally qoq, growth was still robust across existing stores while new store openings have already reached 99SM’s full-year target. Margins also grew off better cost optimisations. Maintain BUY with an unchanged target price of RM4.00.
Company Results | Dialog Group (DLG MK/BUY/RM1.87/Target: RM2.95)
- 1QFY27 results were in line with expectations. We believe upstream earnings was lackluster considering favourable oil prices, as ongoing maintenance still cap volume upside from a Production Sharing Contract (PSC). As expected and highlighted by Royal Vopak, storage earnings are flattish qoq, but it will be sustainable. We anticipate the debut of Cendramas and Baram Junior Cluster (BJC; which had early first gas production) PSCs in upcoming 2QFY27 results. Maintain BUY with a target price of RM2.95.
Company Results | Hap Seng Plantations (HAPL MK/BUY/RM2.21/Target: RM3.05)
- HAPL's 9M26 core net profit of RM116.8m came in line with expectations, accounting for 70% of our full-year forecast. We expect a stronger performance in 4Q26 driven by seasonal peak production cycle and brought forward sales from this quarter. Maintain BUY and a target price of RM3.05, pegged to 12x 2027 PE.
Company Results | Mr D.I.Y. Group (M) (MRDIY MK/BUY/RM1.04/Target: RM1.50)
- 9M26 results missed expectations. SSSG contracted for the second quarter in a row while less favourable forex and product mix saw margins contract sequentially. Going forward, the group is likely to hike prices of certain products in response to the higher costs as well as the minimum wage increase. MRDIY has also trimmed its new store opening target, shifting its focus to refurbishming its older store base. Maintain BUY with a lower target price of RM1.50 (from RM1.65).
Company Results | Solarvest Holdings (SOLAR MK/BUY/RM3.51/Target: RM5.30)
- Solarvest’s 2QFY27 core net profit rose to RM26.3m (+40% yoy; +38% qoq), driven by higher progress billing of utility-scale EPCC jobs, as well as higher RE generation and an O&M earnings base. 2QFY27 net margin has normalised to 10%, within expectations. 1HFY27 net profit accounts for 39% of our full-year earnings, and is deemed in line with expectations as higher EPCC contribution will drive 2HFY27 earnings. We expect a potential 300-500MW CRESS win in 4Q26/1Q27. Maintain BUY. Target price: RM5.30.
What’s Inside
Company Results | Duopharma Biotech (DBB MK/BUY/RM1.08/Target: RM1.62)
- Duopharma’s 2Q26 earnings came above expectations, accounting for 87%/84% of our and consensus full-year forecasts. However, we remain cautious on persistent high input cost and a stronger US dollar, which could weigh on margins in the coming quarters. That said, Duopharma offers defensive, domestically-driven growth and bargain valuations at current share price. Maintain BUY with a target price of RM1.62.
Market Spotlight
- The FBMKLCI dropped 12.88pt (-0.81%) to close at 1,575.15 yesterday as investors remained cautious over the uncertain global environment and due to the lack of fresh local catalysts.
- Wall Street ended lower on Tuesday, as investors displayed caution ahead of Nvidia’s much-anticipated quarterly results which could offer insight into both the outlook for the chip giant and the wider artificial intelligence trade.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Ecofirst Consolidated | ECOF MK
- Trading Buy Range: RM0.33-0.34
Pavilion REITs | PREIT MK
- Trading Buy Range: RM1.61-1.62
Ramssol Group | RAMSSOL MK
- Trading Buy Range: RM0.805-0.81
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


