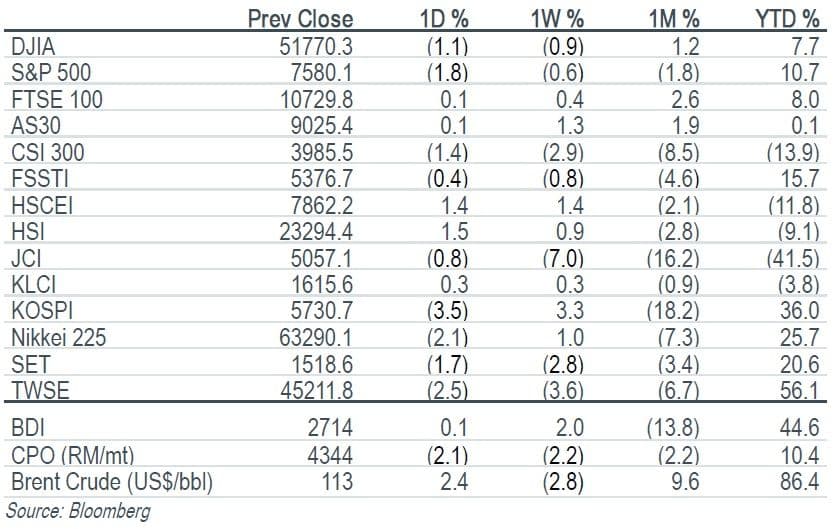
Key Indices
Top Stories
Sector Update | Banking
- Sep 26 loan growth accelerated on stronger business lending and approvals, while deposit growth held steady. Asset quality improved, although LLC eased further. Maintain OVERWEIGHT. We expect sector earnings to grow by a decent 6% in 2027.
Company Results | IGB REIT (IGBREIT MK/BUY/RM2.72/Target: RM2.92)
- 3Q26 results were in line with expectations, with a DPU of 3.51 sen declared. Management maintained its midsingle-digit reversion guidance for 2027, and we believe this is conservative as MVS is seeing reversion well above 5%. Historically, IGB REIT has mostly exceeded its reversion guidance. Maintain BUY with a lower target price of RM2.92 as we increase our cost of equity assumption and roll over our valuation base to 2027. IGB REIT currently offers 5.4-5.6% yields for 2026-27.
Company Update | Pekat Group (PEKAT MK/BUY/RM2.93/Target: RM3.60)
- A 150MW CRESS win is highly probable by Dec 26, as we believe Pekat can capture blue-sky 2GW of CRESS projects over the next three years. As such, we lift our 2028 net profit forecasts by 25% to capture CRESS win potential. We expect the completion of main board transfer by end-Nov 26. Maintain BUY with a higher SOTPbased fair value of RM3.60/share, assuming a 500MW CRESS win. A blue-sky fair value of RM6.30/share pencils in 2GW of CRESS assets.
Company Update | Solarvest Holdings (SOLAR MK/BUY/RM4.31/Target: RM5.30)
- We expect earnings to peak in FY29 as management drives ROE to an impressive 15.5% (from 10%) against the doubling of its orderbook to RM5b. We raise our FY29 net profit forecasts by 29% to RM200m, in line with market. We also lift our target price to RM5.30/share, capturing 500MW CRESS asset ownership. Our blue-sky fair value is RM7.50/share assuming 2GW CRESS ownership. Maintain BUY; target price: RM5.30.
What’s Inside
Company Results | SkyeChip (SKYECHIP MK/HOLD/RM2.69/Target: RM2.93)
- Skyechip’s 6MFY27 results are within our and consensus expectations. SkyeChip’s established silicon IP and custom ASIC businesses remain the key earnings drivers, while its expansion into AI silicon and Arm-based compute platforms could provide a second leg of growth from 2029-30 onwards. Following a 205% surge since our initiation and from its IPO price of RM0.88, we believe the current share price has largely priced in SkyeChip’s near-term growth prospects. Maintain HOLD. Target price: RM2.93.
Market Spotlight
- The FBMKLCI rose 4.44pt and closed at 1,615.60 last Friday.
- US stocks were lower after the close on Friday, as losses in the technology, industrials and basic materials sectors led shares lower.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Affin Bank | ABANK MK
- Trading Buy Range: RM2.04-2.05
Carimin Petroleum | CARIP MK
- Trading Buy Range: RM0.40-0.405
TMC Life Sciences | TMCL MK
- Trading Buy Range: RM0.43-0.435
Top Stories
Sector Update | Banking
- Sep 26 loan growth accelerated on stronger business lending and approvals, while deposit growth held steady. Asset quality improved, although LLC eased further. Maintain OVERWEIGHT. We expect sector earnings to grow by a decent 6% in 2027.
Company Results | IGB REIT (IGBREIT MK/BUY/RM2.72/Target: RM2.92)
- 3Q26 results were in line with expectations, with a DPU of 3.51 sen declared. Management maintained its midsingle-digit reversion guidance for 2027, and we believe this is conservative as MVS is seeing reversion well above 5%. Historically, IGB REIT has mostly exceeded its reversion guidance. Maintain BUY with a lower target price of RM2.92 as we increase our cost of equity assumption and roll over our valuation base to 2027. IGB REIT currently offers 5.4-5.6% yields for 2026-27.
Company Update | Pekat Group (PEKAT MK/BUY/RM2.93/Target: RM3.60)
- A 150MW CRESS win is highly probable by Dec 26, as we believe Pekat can capture blue-sky 2GW of CRESS projects over the next three years. As such, we lift our 2028 net profit forecasts by 25% to capture CRESS win potential. We expect the completion of main board transfer by end-Nov 26. Maintain BUY with a higher SOTPbased fair value of RM3.60/share, assuming a 500MW CRESS win. A blue-sky fair value of RM6.30/share pencils in 2GW of CRESS assets.
Company Update | Solarvest Holdings (SOLAR MK/BUY/RM4.31/Target: RM5.30)
- We expect earnings to peak in FY29 as management drives ROE to an impressive 15.5% (from 10%) against the doubling of its orderbook to RM5b. We raise our FY29 net profit forecasts by 29% to RM200m, in line with market. We also lift our target price to RM5.30/share, capturing 500MW CRESS asset ownership. Our blue-sky fair value is RM7.50/share assuming 2GW CRESS ownership. Maintain BUY; target price: RM5.30.
What’s Inside
Company Results | SkyeChip (SKYECHIP MK/HOLD/RM2.69/Target: RM2.93)
- Skyechip’s 6MFY27 results are within our and consensus expectations. SkyeChip’s established silicon IP and custom ASIC businesses remain the key earnings drivers, while its expansion into AI silicon and Arm-based compute platforms could provide a second leg of growth from 2029-30 onwards. Following a 205% surge since our initiation and from its IPO price of RM0.88, we believe the current share price has largely priced in SkyeChip’s near-term growth prospects. Maintain HOLD. Target price: RM2.93.
Market Spotlight
- The FBMKLCI rose 4.44pt and closed at 1,615.60 last Friday.
- US stocks were lower after the close on Friday, as losses in the technology, industrials and basic materials sectors led shares lower.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Affin Bank | ABANK MK
- Trading Buy Range: RM2.04-2.05
Carimin Petroleum | CARIP MK
- Trading Buy Range: RM0.40-0.405
TMC Life Sciences | TMCL MK
- Trading Buy Range: RM0.43-0.435
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


