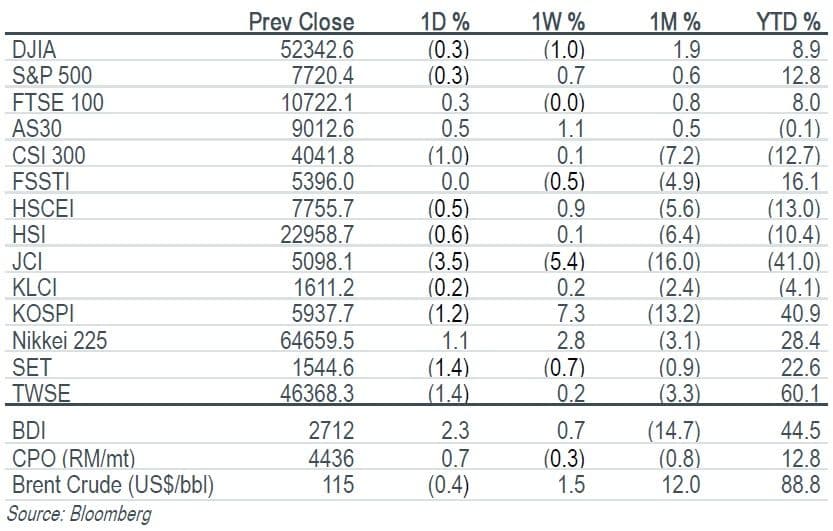
Key Indices
Top Stories
Sector Update | Oil & Gas
- Ageing OSVs are becoming a more critical issue due to a lack of incentives for newbuild orders and fleet replacement. However, vessel age limit is also gradually fading in relevance for oil majors including Petronas, prioritising conditional assessments instead. Another shifting trend is ESG-focused, ie the increasing acceptance of alternative fuels and next generation hybrid designs over conventional models. We see non-rated players like Keyfield, Alam Maritim, Lianson Fleet and Perdana Petroleum as standouts Maintain sector MARKET WEIGHT.
Company Update | KIP REIT (KIP MK/BUY/RM0.865/Target: RM1.11)
- KIP REIT’s focus will be on organic growth, having achieved its AUM target of RM2.0b. KIPMall Setapak could achieve 20-25% higher rental rates for new tenants, while AEI for Masai Mall is expected to generate ROI of 10%. Maintain BUY with a lower target price of RM1.11 as we increase our cost of equity assumption and roll over our valuation base to FY27. KIP REIT is one of our top picks, offering attractive yields of 8.6% and 9.0% for FY27 and FY28.
What’s Inside
Company Reults | Axis REIT (AXRB MK/BUY/RM1.78/Target: RM2.04)
- Axis REIT 3Q26 results were below our expectation due to higher financing cost, while we expect DPU to catch up in 4Q26 with an eventual recognition of consequential-loss insurance proceeds by year-end. Overall occupancy was flat qoq at 93% in 3Q26 and is expected to improve to 96-97% by year-end. We trim our earnings forecasts by 2-4% for 2026-28F due to a higher-than-expected financing cost. Maintain BUY with a lower target price of RM2.04.
Company Update | SD Guthrie (SDG MK/BUY/RM5.77/Target: RM8.30)
- SDG is selling 1,623 acres of freehold oil palm land in Bukit Kerayong, Klang, to a JV with YTL Power International and Bumi Assets for RM933.6m, 5% above independent valuation and 15.6x book value. SDG keeps a 30% stake in the JV, which will build a light-to-medium industrial park. The sale brings a one-off gain of RM586m (8.5 sen/share) on completion in 1Q27, and RM744m of the proceeds will repay debt. Maintain BUY. Target price: RM8.30.
Market Spotlight
- The FBMKLCI took a breather yesterday, sliding 2.71pt to close at 1,611.16 following mild profit-taking in blue chips, in-line with weakness across the region.
- US stocks were lower after the close on Thursday, as losses in the technology, basic materials and consumer services sectors led shares lower.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Ann Joo Resources | AJR MK
- Trading Buy Range: RM0.495-0.50
KPJ Healthcare | KPJ MK
- Trading Buy Range: RM2.45-2.50
Eversendai Corporation | EVSD MK
- Trading Buy Range: RM0.245-0.25
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


