Analyst
Wendy Chen Zhiyi
wendy.chen@uobkh.comOvernight Markets
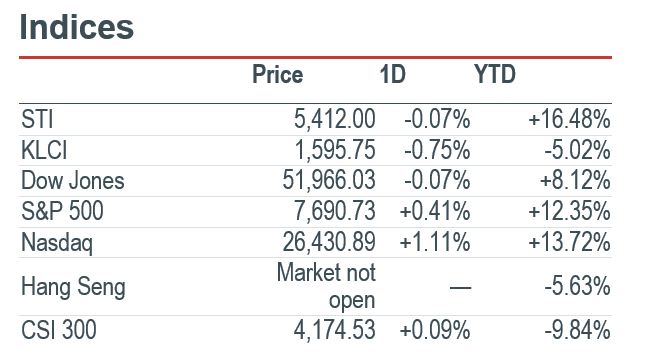
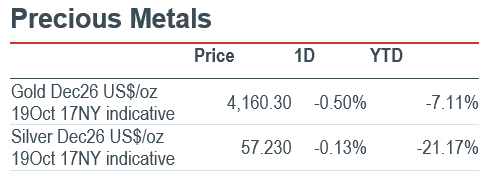
Market Movers: Amazon (AMZN US) rose 4.98% in Monday’s 19 October US session, as Morgan Stanley made it a top pick. Separately, AWS announced TorchNeuron, designed to simplify moving PyTorch workloads onto Trainium chips; release is planned for 20 October. Nvidia (NVDA US) gained 1.38% as AI startup Modal said it would adopt Vera CPUs alongside rival processors. The S&P 500 rose 0.41% and Nasdaq gained 1.11%. In Australia, Cleanaway (CWY AU) jumped 20.24% after agreeing to EQT’s A$9.3bn enterprise-value takeover at A$3.095 per share, less further dividends. Completion remains conditional. Easier software migration and agent infrastructure support AI adoption; takeover approvals remain a separate execution risk. (Reuters / Amazon / Reuters / EQT / Market data / Market data / Market data / Market data / Market data) Amazon (AMZN US) and Nvidia (NVDA US) are our Core Recommendations.
Macro: China’s 3Q GDP grew 4.5% YoY, up from 4.3% in the second quarter and above a 4.4% forecast. Quarter-on-quarter growth accelerated to 1.2% from 0.9%. September industrial output rose 5.5% YoY versus August’s 5.2%, while retail sales increased 1.1% versus 0.4%. January–September fixed-asset investment fell 7.2% YoY and property investment dropped 20.6% YoY. Better headline growth masks persistent domestic-demand and property weakness, limiting the evidence for a broad recovery. (NBS / DPA)
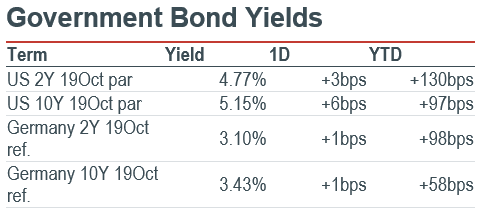
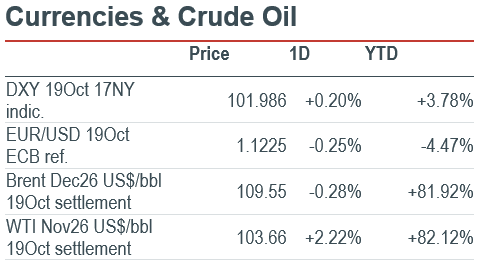
FICC: November WTI settled 2.22% higher at US$103.66/bbl on 19 October, ahead of 20 Oct expiry in thin trading. More liquid December WTI fell 0.5%, while December Brent eased 0.28% to US$109.55. The expiring contract’s rise does not signal broad oil strength. The US 10-year par yield rose 6bps to 5.15%, lifting discount rates. (Reuters / US Treasury)
AI
Amazon (AMZN US) lowers the software barrier to Trainium. Amazon announced TorchNeuron, which it says enables existing PyTorch code to run on Trainium2/3 with one configuration change. Its planned open-source release could reduce migration friction, although adoption remains unproven. Shares gained 4.98% on Monday after Morgan Stanley named Amazon a top pick and raised its target to US$350 from US$335. (Amazon / Reuters / Motley Fool / Market data) Amazon (AMZN US) is our Core Recommendation.
Nvidia (NVDA US) wins a new customer for Vera CPUs. Modal plans to add Nvidia’s Vera CPUs for AI agents. Early tests doubled completed work versus currently available Intel/AMD chips, Modal said; it retains a mixed fleet and newer rivals could narrow the gap. Revenue exceeded 15 times its year-earlier level. Nvidia gained 1.38% Monday. The customer win broadens its opportunity beyond GPUs. (Reuters / Market data) Nvidia (NVDA US) is our Core Recommendation.
Anthropic and Nscale reportedly discuss US$45bn of computing capacity. Bloomberg reported talks for a second computing facility at Nscale’s Monarch campus in West Virginia. Reuters could not independently verify the report; neither company immediately commented and no completed contract was established. The proposed commitment could expand Claude’s capacity, while exposing counterparties to construction, power and financing risks. (Reuters)
- Microsoft (MSFT US) adds controls for agents operating inside companies. Project Perception’s expansion lifts discovery to 60 local-agent types, adding 35. Announced controls can restrict permissions, require human approval or stop execution as risk changes; Guardian Agents investigate and contain threats within human-set policies. The framework addresses an enterprise-adoption obstacle: allowing agents useful access without surrendering control. Commercial uptake remains to be demonstrated. (Microsoft) Microsoft (MSFT US) is our Core Recommendation.
Americas
Alphabet (GOOGL US) loses its Supreme Court patent-policy appeal. The court declined an appeal concerning a policy that makes patents older than six years more likely to escape administrative validity review. The dispute involves VirtaMove’s server-software patent. This refusal to hear Google’s policy challenge does not establish infringement. It preserves a procedural obstacle for technology companies seeking to challenge older patents. (Reuters) Alphabet (GOOGL US) is our Trading Buy.
Tesla (TSLA US) renews scrutiny of board continuity and Musk’s incentives. Tesla seeks three-year board terms for Musk, Robyn Denholm and JB Straubel. Its proxy reports US$158.4bn for Musk’s 2025 performance award, covering about 423.7m restricted shares; none of its 12 tranches was earned. This is award value, not cash paid. Dilution and governance warrant scrutiny against retention benefits. Shares gained 3.76% Monday. (Reuters / Market data)
Apple (AAPL US) invites the press to a new product event. The Los Angeles “Pro and tell” event is scheduled for 29 October, 01:00 SGT. Bloomberg-reported expectations include touchscreen OLED MacBook Pro models; specifications, pricing and availability remain unconfirmed. A substantial redesign could stimulate replacement demand and improve product mix, but customer acceptance and eventual pricing will determine its commercial impact. (9to5Mac)
Johnson & Johnson (JNJ US) extends Tremfya evidence. New FUZION results show combined fistula remission rising from 28% at week 24 to 35% at week 48 in the original 100mg-every-eight-weeks arm. The later analysis includes dose escalations, limiting unchanged-dose comparisons. The extension supports treatment positioning in a difficult complication; clinical progress alone does not establish an earnings uplift. (Johnson & Johnson) Johnson & Johnson (JNJ US) is our Core Recommendation.
Reported certification milestone could unlock Boeing (BA US) deliveries. Reuters reported that US officials expect to announce FAA certification of the MAX 10; the agency had not commented. Nearly 1,500 orders account for about 30% of Boeing’s 737 backlog. Approval could unlock deliveries and cash collection, but the report is not official confirmation. Production execution remains a separate risk. (Reuters)
KKR (KKR US) agrees to sell Infinity Transportation to Ares. The agreed sale values the railcar lessor at US$2.9bn enterprise value. Infinity manages roughly 50,000 railcars serving over 350 North American lessees. First-quarter 2027 closing remains conditional on regulatory and customary approvals. KKR would recycle capital, while the Ares funds gain long-lived assets whose returns depend on leasing demand, utilisation and financing costs.
Greater China
Hansoh broadens Roche oncology alliance. Hansoh Pharma (3692.HK) announced a second Roche collaboration Monday covering two preclinical antibody-drug conjugates and additional targets. Terms include US$400m upfront, US$110m on the first anniversary and potentially over US$15bn of milestones plus royalties. Hansoh retains Greater China rights. The funding validates its platform, but most headline value depends on successful development and commercialisation. (Hansoh / Reuters)
MiniMax cuts the cost of its latest agent model. MiniMax (0100.HK) launched M3.1 Flash Monday, claiming nearly triple its predecessor's inference speed and 70% lower agent-task costs. API charges per million tokens are US$0.15 for input, US$0.60 for output and US$0.015 for cached input. Cheaper coding and agent workflows could support adoption and intensify competition; the company-reported improvements do not establish serving profitability. (MiniMax / Reuters)
METiS signs delivery-platform deal with Lilly. METiS TechBio (7666.HK) announced a tissue-targeted drug-delivery collaboration with Eli Lilly (LLY US) Monday. Terms include an upfront payment in the low tens of millions of US dollars, potentially US$1.1bn in milestones and single-digit royalties on annual net sales. Lilly's development capabilities complement METiS's AI-assisted lipid platform, but substantial receipts depend on clinical and commercial success. (METiS TechBio / Reuters) Eli Lilly (LLY US) is our Core Recommendation.
China opens active-ETF channel while reinforcing market safeguards. CSRC chairman Wu Qing said Monday the regulator would approve 18 actively managed ETFs and strengthen market safeguards, including scrutiny of offshore leveraged products tied to mainland shares. Shanghai's exchange confirmed active-ETF approvals, adding to 943 ETFs with RMB3.35tn of assets at September-end. This expands fund managers' distribution opportunities, although approvals do not guarantee new inflows. (CSRC / Shanghai Stock Exchange / Reuters)
Asia ex. China
Cleanaway jumps after agreeing EQT takeover. Cleanaway (CWY AU) jumped 20.24% to A$2.97 at Monday's close after agreeing a binding EQT Infrastructure VI takeover. The A$3.095-per-share cash offer, reduced by further distributions, values the business at about A$9.3bn including debt. Shareholder, court and regulatory approvals remain outstanding. The residual discount to the offer reflects execution and timing risks in taking the Australian waste-management group private. (EQT / Reuters / Market data)
Challenger rallies on Daiichi proposal and stronger sales. Challenger (CGF AU) gained 19.29% to A$11.75 at Monday's close after disclosing TAL's non-binding A$11.80 offer for the remaining 79.5%. The proposal arrived after Friday's close and requires diligence and other conditions. Monday's FY27 first-quarter sales of A$4.4bn rose 52% YoY. Stronger annuity demand supports the franchise, but negotiations may not produce a binding deal. (Challenger / Challenger results / Reuters / Market data)
Singapore expands scrutiny of haze-linked businesses. Singapore said Monday it would consider additional legal, regulatory and economic measures against haze-linked companies, including financing and government benefits. SGX has questioned seven agricultural firms, including Wilmar and First Resources, about possible fire links. Banks must assess environmental and legal risks under MAS supervision. Financing and compliance costs could rise, but inquiries do not establish liability. (Ministry of Home Affairs / The Straits Times)
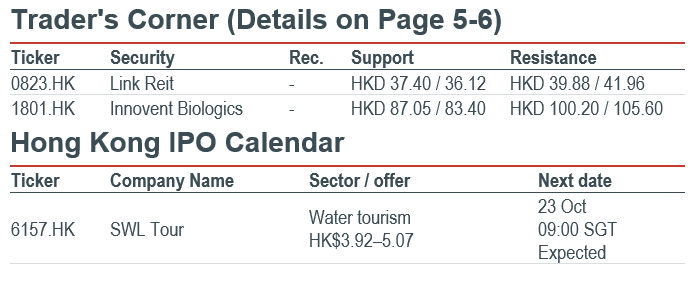
Mi Material launches Singapore IPO. Mi Material launched its Singapore IPO Monday at S$1.80, with S$157.9m net proceeds supporting research and production expansion. First-half revenue grew 109.8% YoY. The public offer closes at 12:00 SGT on 26 October 2026; trading is expected at 14:00 SGT on 28 October 2026. The packaging-materials supplier's capacity execution will determine how effectively fresh capital converts into earnings. (Mi Material / The Business Times)
EMEA and Others
Barclays defends private-credit accounting. Barclays (BARC LN) fell 3.50% to 417.5p at Monday's close on reported BoE scrutiny of private-credit accounting. Separately, Barclays defended its £15bn exposure and disclosed £300m of marked-to-market loan swaps against £1.5bn notional assets. Most private-credit exposure sits in its banking book. Capital treatment remains an investor concern, but the examination is not a finding of misstatement. (Reuters / Reuters / Market data)
Merck buys Silence's RNA-drug platform. Merck KGaA (MRK GY) agreed Monday to buy Silence Therapeutics for US$1.3bn equity value, or US$20 per ADS, a 130% premium to Friday's close; enterprise value is US$1.1bn. It gains gene-silencing technology and divesiran, preparing for late-stage blood-cancer trials. The pipeline expands, but clinical and commercial risks remain, and the transaction is subject to customary closing conditions. (Silence / SEC / Reuters)
Traders' Corner
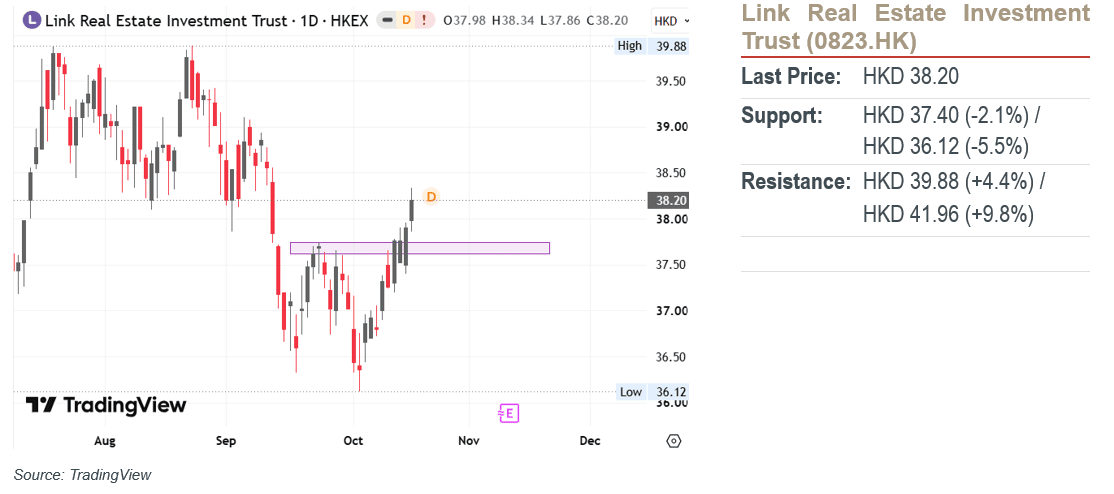
Our Technical View
Price penetrated its recent price high.
This structural breakout establishes a clean polarity flip, converting the former overhead resistance ceiling into an active dynamic support floor.
The RSI has crossed and continues to slope upward above its neutral 50-midline with positive velocity.
As long as price remains supported above the newly converted baseline, we see continued upward expansion toward higher supply targets.
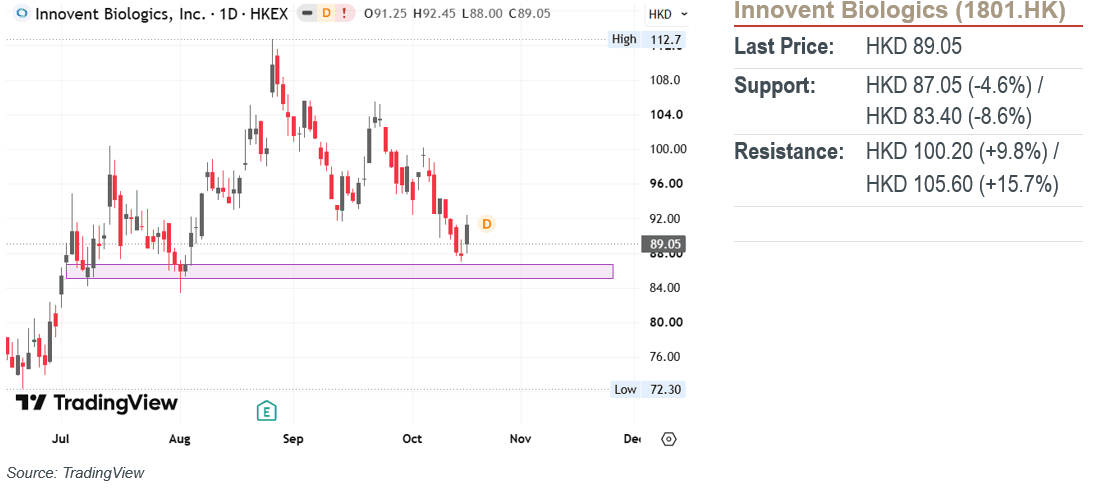
Our Technical View
Price initiated a rebound near its previous support zone.
The RSI is turning upward from near oversold territory, signaling an inflection in sell-side velocity and a relief of extreme downside pressure.
However, structural confirmation of a tactical trend reversal hinges on upcoming daily closing price action; a decisive bullish daily candle close tomorrow is required to validate the support defense.
Upon confirmation, we will favor a continued bullish rebound targeting upper supply overhead zones.
Market Movers: Amazon (AMZN US) rose 4.98% in Monday’s 19 October US session, as Morgan Stanley made it a top pick. Separately, AWS announced TorchNeuron, designed to simplify moving PyTorch workloads onto Trainium chips; release is planned for 20 October. Nvidia (NVDA US) gained 1.38% as AI startup Modal said it would adopt Vera CPUs alongside rival processors. The S&P 500 rose 0.41% and Nasdaq gained 1.11%. In Australia, Cleanaway (CWY AU) jumped 20.24% after agreeing to EQT’s A$9.3bn enterprise-value takeover at A$3.095 per share, less further dividends. Completion remains conditional. Easier software migration and agent infrastructure support AI adoption; takeover approvals remain a separate execution risk. (Reuters / Amazon / Reuters / EQT / Market data / Market data / Market data / Market data / Market data) Amazon (AMZN US) and Nvidia (NVDA US) are our Core Recommendations.
Macro: China’s 3Q GDP grew 4.5% YoY, up from 4.3% in the second quarter and above a 4.4% forecast. Quarter-on-quarter growth accelerated to 1.2% from 0.9%. September industrial output rose 5.5% YoY versus August’s 5.2%, while retail sales increased 1.1% versus 0.4%. January–September fixed-asset investment fell 7.2% YoY and property investment dropped 20.6% YoY. Better headline growth masks persistent domestic-demand and property weakness, limiting the evidence for a broad recovery. (NBS / DPA)
FICC: November WTI settled 2.22% higher at US$103.66/bbl on 19 October, ahead of 20 Oct expiry in thin trading. More liquid December WTI fell 0.5%, while December Brent eased 0.28% to US$109.55. The expiring contract’s rise does not signal broad oil strength. The US 10-year par yield rose 6bps to 5.15%, lifting discount rates. (Reuters / US Treasury)
AI
Amazon (AMZN US) lowers the software barrier to Trainium. Amazon announced TorchNeuron, which it says enables existing PyTorch code to run on Trainium2/3 with one configuration change. Its planned open-source release could reduce migration friction, although adoption remains unproven. Shares gained 4.98% on Monday after Morgan Stanley named Amazon a top pick and raised its target to US$350 from US$335. (Amazon / Reuters / Motley Fool / Market data) Amazon (AMZN US) is our Core Recommendation.
Nvidia (NVDA US) wins a new customer for Vera CPUs. Modal plans to add Nvidia’s Vera CPUs for AI agents. Early tests doubled completed work versus currently available Intel/AMD chips, Modal said; it retains a mixed fleet and newer rivals could narrow the gap. Revenue exceeded 15 times its year-earlier level. Nvidia gained 1.38% Monday. The customer win broadens its opportunity beyond GPUs. (Reuters / Market data) Nvidia (NVDA US) is our Core Recommendation.
Anthropic and Nscale reportedly discuss US$45bn of computing capacity. Bloomberg reported talks for a second computing facility at Nscale’s Monarch campus in West Virginia. Reuters could not independently verify the report; neither company immediately commented and no completed contract was established. The proposed commitment could expand Claude’s capacity, while exposing counterparties to construction, power and financing risks. (Reuters)
- Microsoft (MSFT US) adds controls for agents operating inside companies. Project Perception’s expansion lifts discovery to 60 local-agent types, adding 35. Announced controls can restrict permissions, require human approval or stop execution as risk changes; Guardian Agents investigate and contain threats within human-set policies. The framework addresses an enterprise-adoption obstacle: allowing agents useful access without surrendering control. Commercial uptake remains to be demonstrated. (Microsoft) Microsoft (MSFT US) is our Core Recommendation.
Americas
Alphabet (GOOGL US) loses its Supreme Court patent-policy appeal. The court declined an appeal concerning a policy that makes patents older than six years more likely to escape administrative validity review. The dispute involves VirtaMove’s server-software patent. This refusal to hear Google’s policy challenge does not establish infringement. It preserves a procedural obstacle for technology companies seeking to challenge older patents. (Reuters) Alphabet (GOOGL US) is our Trading Buy.
Tesla (TSLA US) renews scrutiny of board continuity and Musk’s incentives. Tesla seeks three-year board terms for Musk, Robyn Denholm and JB Straubel. Its proxy reports US$158.4bn for Musk’s 2025 performance award, covering about 423.7m restricted shares; none of its 12 tranches was earned. This is award value, not cash paid. Dilution and governance warrant scrutiny against retention benefits. Shares gained 3.76% Monday. (Reuters / Market data)
Apple (AAPL US) invites the press to a new product event. The Los Angeles “Pro and tell” event is scheduled for 29 October, 01:00 SGT. Bloomberg-reported expectations include touchscreen OLED MacBook Pro models; specifications, pricing and availability remain unconfirmed. A substantial redesign could stimulate replacement demand and improve product mix, but customer acceptance and eventual pricing will determine its commercial impact. (9to5Mac)
Johnson & Johnson (JNJ US) extends Tremfya evidence. New FUZION results show combined fistula remission rising from 28% at week 24 to 35% at week 48 in the original 100mg-every-eight-weeks arm. The later analysis includes dose escalations, limiting unchanged-dose comparisons. The extension supports treatment positioning in a difficult complication; clinical progress alone does not establish an earnings uplift. (Johnson & Johnson) Johnson & Johnson (JNJ US) is our Core Recommendation.
Reported certification milestone could unlock Boeing (BA US) deliveries. Reuters reported that US officials expect to announce FAA certification of the MAX 10; the agency had not commented. Nearly 1,500 orders account for about 30% of Boeing’s 737 backlog. Approval could unlock deliveries and cash collection, but the report is not official confirmation. Production execution remains a separate risk. (Reuters)
KKR (KKR US) agrees to sell Infinity Transportation to Ares. The agreed sale values the railcar lessor at US$2.9bn enterprise value. Infinity manages roughly 50,000 railcars serving over 350 North American lessees. First-quarter 2027 closing remains conditional on regulatory and customary approvals. KKR would recycle capital, while the Ares funds gain long-lived assets whose returns depend on leasing demand, utilisation and financing costs.
Greater China
Hansoh broadens Roche oncology alliance. Hansoh Pharma (3692.HK) announced a second Roche collaboration Monday covering two preclinical antibody-drug conjugates and additional targets. Terms include US$400m upfront, US$110m on the first anniversary and potentially over US$15bn of milestones plus royalties. Hansoh retains Greater China rights. The funding validates its platform, but most headline value depends on successful development and commercialisation. (Hansoh / Reuters)
MiniMax cuts the cost of its latest agent model. MiniMax (0100.HK) launched M3.1 Flash Monday, claiming nearly triple its predecessor's inference speed and 70% lower agent-task costs. API charges per million tokens are US$0.15 for input, US$0.60 for output and US$0.015 for cached input. Cheaper coding and agent workflows could support adoption and intensify competition; the company-reported improvements do not establish serving profitability. (MiniMax / Reuters)
METiS signs delivery-platform deal with Lilly. METiS TechBio (7666.HK) announced a tissue-targeted drug-delivery collaboration with Eli Lilly (LLY US) Monday. Terms include an upfront payment in the low tens of millions of US dollars, potentially US$1.1bn in milestones and single-digit royalties on annual net sales. Lilly's development capabilities complement METiS's AI-assisted lipid platform, but substantial receipts depend on clinical and commercial success. (METiS TechBio / Reuters) Eli Lilly (LLY US) is our Core Recommendation.
China opens active-ETF channel while reinforcing market safeguards. CSRC chairman Wu Qing said Monday the regulator would approve 18 actively managed ETFs and strengthen market safeguards, including scrutiny of offshore leveraged products tied to mainland shares. Shanghai's exchange confirmed active-ETF approvals, adding to 943 ETFs with RMB3.35tn of assets at September-end. This expands fund managers' distribution opportunities, although approvals do not guarantee new inflows. (CSRC / Shanghai Stock Exchange / Reuters)
Asia ex. China
Cleanaway jumps after agreeing EQT takeover. Cleanaway (CWY AU) jumped 20.24% to A$2.97 at Monday's close after agreeing a binding EQT Infrastructure VI takeover. The A$3.095-per-share cash offer, reduced by further distributions, values the business at about A$9.3bn including debt. Shareholder, court and regulatory approvals remain outstanding. The residual discount to the offer reflects execution and timing risks in taking the Australian waste-management group private. (EQT / Reuters / Market data)
Challenger rallies on Daiichi proposal and stronger sales. Challenger (CGF AU) gained 19.29% to A$11.75 at Monday's close after disclosing TAL's non-binding A$11.80 offer for the remaining 79.5%. The proposal arrived after Friday's close and requires diligence and other conditions. Monday's FY27 first-quarter sales of A$4.4bn rose 52% YoY. Stronger annuity demand supports the franchise, but negotiations may not produce a binding deal. (Challenger / Challenger results / Reuters / Market data)
Singapore expands scrutiny of haze-linked businesses. Singapore said Monday it would consider additional legal, regulatory and economic measures against haze-linked companies, including financing and government benefits. SGX has questioned seven agricultural firms, including Wilmar and First Resources, about possible fire links. Banks must assess environmental and legal risks under MAS supervision. Financing and compliance costs could rise, but inquiries do not establish liability. (Ministry of Home Affairs / The Straits Times)
Mi Material launches Singapore IPO. Mi Material launched its Singapore IPO Monday at S$1.80, with S$157.9m net proceeds supporting research and production expansion. First-half revenue grew 109.8% YoY. The public offer closes at 12:00 SGT on 26 October 2026; trading is expected at 14:00 SGT on 28 October 2026. The packaging-materials supplier's capacity execution will determine how effectively fresh capital converts into earnings. (Mi Material / The Business Times)
EMEA and Others
Barclays defends private-credit accounting. Barclays (BARC LN) fell 3.50% to 417.5p at Monday's close on reported BoE scrutiny of private-credit accounting. Separately, Barclays defended its £15bn exposure and disclosed £300m of marked-to-market loan swaps against £1.5bn notional assets. Most private-credit exposure sits in its banking book. Capital treatment remains an investor concern, but the examination is not a finding of misstatement. (Reuters / Reuters / Market data)
Merck buys Silence's RNA-drug platform. Merck KGaA (MRK GY) agreed Monday to buy Silence Therapeutics for US$1.3bn equity value, or US$20 per ADS, a 130% premium to Friday's close; enterprise value is US$1.1bn. It gains gene-silencing technology and divesiran, preparing for late-stage blood-cancer trials. The pipeline expands, but clinical and commercial risks remain, and the transaction is subject to customary closing conditions. (Silence / SEC / Reuters)
Traders' Corner
Our Technical View
Price penetrated its recent price high.
This structural breakout establishes a clean polarity flip, converting the former overhead resistance ceiling into an active dynamic support floor.
The RSI has crossed and continues to slope upward above its neutral 50-midline with positive velocity.
As long as price remains supported above the newly converted baseline, we see continued upward expansion toward higher supply targets.
Our Technical View
Price initiated a rebound near its previous support zone.
The RSI is turning upward from near oversold territory, signaling an inflection in sell-side velocity and a relief of extreme downside pressure.
However, structural confirmation of a tactical trend reversal hinges on upcoming daily closing price action; a decisive bullish daily candle close tomorrow is required to validate the support defense.
Upon confirmation, we will favor a continued bullish rebound targeting upper supply overhead zones.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


