Key Indices
Top Stories
Company Results | Maxis (MAXIS MK/BUY/RM3.50/Target: RM4.20)
- Maxis recorded strong 3Q26 results, with net profit reported at RM447m (+9% yoy; +3% qoq) on the back of cost discipline and a higher service and enterprise revenue base. This brought 9M26 net profit to RM1,300m, which beat expectations. Maxis declared a higher third interim DPS of 4.5 sen/share. We raise 2026 earnings forecasts by 2% to reflect a lower-than-expected earnings drag from DNB. Maintain BUY with a DCF-based target price of RM4.20. The stock offers a 5.3% dividend yield.
Company Results | Public Bank (PBK MK/HOLD/RM4.90/Target: RM5.20)
- Public Bank’s 3Q26 results were marginally below expectations due to higher-than-expected credit cost. Maintain HOLD with a lower target price of RM5.20, down from RM5.45 after earnings revision.
Company Update | MISC (MISC MK/BUY/RM8.01/Target: RM9.50)
- Having Yinson as a partner will: a) add value to MISC, considering how Yinson had added value to its clients and collaborative partners in the past, and b) grant MISC’s FPSO business immediate access into the Africa region, where MISC previously did not have presence. This collaboration/value-add proposition extends to the non-FPSO business as well. For now, the incremental earnings is expected to be small at 1.4% of 2027 earnings. Retain BUY, target price of RM9.50.
Company Update | Yinson Holdings (YNS MK/BUY/RM2.26/Target: RM2.50)
- The privatisation price of RM2.50 is the best deal yet, reflecting an EV/EBITDA multiple that aligns with RCPS. MISC will treat YNS like an associate, but the timing of MISC’s entry is impeccable - it will gradually reduce blended financing costs over time, and also address the possibility of YNS securing three new FPSOs (Tangkulo, Albacora and ZabaZaba). We assume that third time will be the charm, and advocate shareholders to support. Retain BUY; revised target price of RM2.50.
Market Spotlight
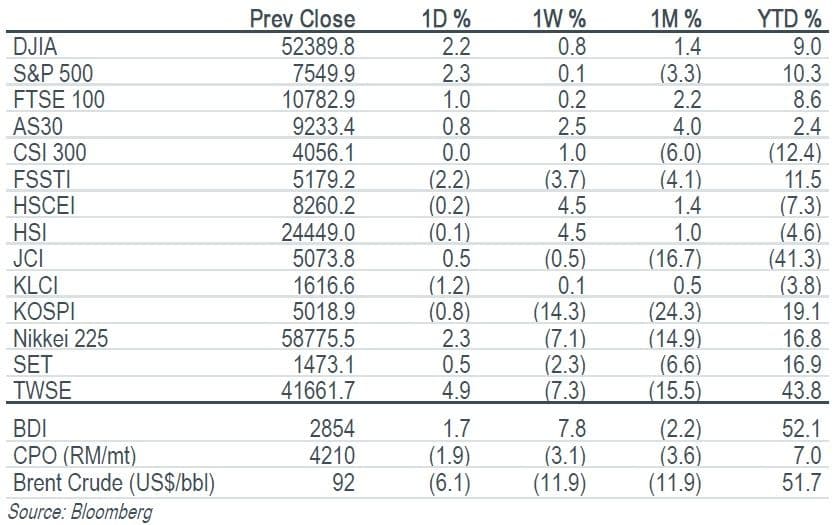
- The FBMKLCI continued to slide by 19.28pt to close at 1,616.58 last Friday amid persistent selling pressure across index counters.
- US stocks were mixed after the close on Friday, as gains in the technology, industrials and consumer goods sectors led shares higher while losses in the consumer services, financials and healthcare sectors led shares lower.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Ancom Nylex | ANCOMNY MK
- Trading Buy Range: RM0.835-0.84
Favelle Favco | FAVCO MK
- Trading Buy Range: RM1.50-1.53
Power Root | PWRT MK
- Trading Buy Range: RM1.18-1.19
Top Stories
Company Results | Maxis (MAXIS MK/BUY/RM3.50/Target: RM4.20)
- Maxis recorded strong 3Q26 results, with net profit reported at RM447m (+9% yoy; +3% qoq) on the back of cost discipline and a higher service and enterprise revenue base. This brought 9M26 net profit to RM1,300m, which beat expectations. Maxis declared a higher third interim DPS of 4.5 sen/share. We raise 2026 earnings forecasts by 2% to reflect a lower-than-expected earnings drag from DNB. Maintain BUY with a DCF-based target price of RM4.20. The stock offers a 5.3% dividend yield.
Company Results | Public Bank (PBK MK/HOLD/RM4.90/Target: RM5.20)
- Public Bank’s 3Q26 results were marginally below expectations due to higher-than-expected credit cost. Maintain HOLD with a lower target price of RM5.20, down from RM5.45 after earnings revision.
Company Update | MISC (MISC MK/BUY/RM8.01/Target: RM9.50)
- Having Yinson as a partner will: a) add value to MISC, considering how Yinson had added value to its clients and collaborative partners in the past, and b) grant MISC’s FPSO business immediate access into the Africa region, where MISC previously did not have presence. This collaboration/value-add proposition extends to the non-FPSO business as well. For now, the incremental earnings is expected to be small at 1.4% of 2027 earnings. Retain BUY, target price of RM9.50.
Company Update | Yinson Holdings (YNS MK/BUY/RM2.26/Target: RM2.50)
- The privatisation price of RM2.50 is the best deal yet, reflecting an EV/EBITDA multiple that aligns with RCPS. MISC will treat YNS like an associate, but the timing of MISC’s entry is impeccable - it will gradually reduce blended financing costs over time, and also address the possibility of YNS securing three new FPSOs (Tangkulo, Albacora and ZabaZaba). We assume that third time will be the charm, and advocate shareholders to support. Retain BUY; revised target price of RM2.50.
Market Spotlight
- The FBMKLCI continued to slide by 19.28pt to close at 1,616.58 last Friday amid persistent selling pressure across index counters.
- US stocks were mixed after the close on Friday, as gains in the technology, industrials and consumer goods sectors led shares higher while losses in the consumer services, financials and healthcare sectors led shares lower.
Tehnical Analysis
FBMKLCI, FCPO & FKLI Index Outlook
Traders’ Corner
Ancom Nylex | ANCOMNY MK
- Trading Buy Range: RM0.835-0.84
Favelle Favco | FAVCO MK
- Trading Buy Range: RM1.50-1.53
Power Root | PWRT MK
- Trading Buy Range: RM1.18-1.19
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


